

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
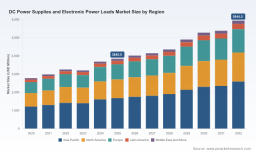
PW Consulting: Worldwide DC Power Supplies & Electronic Power Loads Market to Expand from USD 3,845.5 Million in 2025 to USD 5,944.5 Million by 2032 at a 6.42% CAGR

Worldwide DC Power Supplies and Electronic Power Loads Market: Strategic Insights for 2026 Decision-Makers
Executive summary
PW Consulting’s latest market intelligence on Worldwide DC Power Supplies and Electronic Power Loads positions senior executives to make higher-confidence decisions in 2026. Our analysis shows the market continuing its steady expansion from a 2025 base of approximately USD 3,845.5 million to a materially larger opportunity by the end of the 2026–2032 forecast window — driven by an underlying compound annual growth rate of 6.42%. That macro trajectory masks faster pockets of innovation (high-voltage, bidirectional/regenerative systems, SiC/GaN-enabled designs) and uneven supply-side pressures that will define winners and laggards over the next 18–36 months.
Epoxy Cast Dry-type Transformer (≤35KV) Market
Why this report matters in 2026
- Practical timing: 2026 is a pivot year — product roadmaps, capacity investment, and procurement strategies set now will determine cost and lead-time performance through the next hardware cycle.
- Risk-to-reward squeeze: Component inflation, raw material export controls, and regulatory actions are compressing margins and complicating sourcing while demand for higher-efficiency power electronics continues to rise.
- Decision utility: The research converts market-level forecasts into actionable scenarios for procurement, R&D prioritization, go-to-market segmentation, and M&A targeting without disclosing the granular segment tables that subscribers will access in the full report.
Key market dynamics shaping 2026 strategy
Three structural forces are simultaneously accelerating product innovation and elevating supply risk across DC power supplies and electronic loads:
Worldwide Museum Software Market
- Technology-led demand: The move to higher power density and efficiency—driven by EV traction systems, power-hungry AI/data-center infrastructure, and advanced industrial automation—has escalated adoption of SiC MOSFETs, GaN topologies, and bidirectional/regenerative load architectures. These technology shifts favor suppliers that can integrate advanced semiconductors and thermal management into compact, high-reliability assemblies.
- Supply-chain stressors: Recent policy and market actions — such as expanded export controls on certain rare-earth magnets and U.S. measures addressing processed critical minerals — have created new sourcing constraints. Simultaneously, price increases for components like tantalum capacitors and MLCCs (reported increases in Q1 2026) and higher MOSFET/IGBT pricing and lead times are impacting BOM economics and schedule predictability for both OEMs and test-equipment manufacturers.
- Product differentiation and modularity: Demand for modular, software-defined power supplies and electronic loads (including 1U high-voltage platforms, rack-scalable regens, and VPX-aligned modules for defense/aerospace) is rising. Buyers prioritize systems that simplify integration, shorten validation cycles, and support firmware-driven feature upgrades.
Competitive landscape: capabilities and strategic postures
The market is characterized neither by monopoly nor fragmentation; incumbents and fast-follower specialists coexist. The competitive field includes legacy power-supply manufacturers, precision test vendors, and newer specialists focused on high-power, bidirectional, or high-density designs. Key strategic positions to note:
Electric Bike NMC Battery Market
- TDK-Lambda (TDK Corporation) — breadth and system depth: Leverages wide product breadth across programmable and standard DC supplies plus high-density DC-DC converters to serve industrial, semiconductor, and medical segments. Strength: global channel reach and R&D scale.
- Keysight Technologies — precision and test-ecosystem leadership: Focused on precision programmable supplies and advanced electronic loads for R&D and production test. Strength: integration with high-value ATE and measurement workflows used by semiconductor and power-device developers.
- Chroma ATE Inc. — regenerative and EV test focus: Emphasizes high-performance electronic loads and bidirectional/regenerative capabilities for EVs, batteries, and renewable systems. Strength: deep systems know-how for automated test and battery simulation.
- XP Power and Mean Well — differentiated product cost-performance plays: XP Power drives high-efficiency compact designs (including SiC/GaN adoption) for industrial/medical use, while Mean Well targets value-driven, wide-input products for automation and manufacturing customers.
- EA Elektro-Automatik, Advanced Energy, Magna-Power Electronics — power-dense and high-power system specialists: These firms compete on high-power programmable supplies, rack solutions, and thermal/packaging innovations suitable for automotive, industrial, and semiconductor fab testbeds.
- Module- and component-focused players (Vicor, Delta, Murata, Acopian, B&K Precision) — enabling blocks and quick-ship fills: Provide high-density DC-DC modules, converters, and benchtop/test units that feed larger system OEMs and contract manufacturers.
Recent product moves (for example, introductions of high-voltage 1U DC supplies, VPX-aligned DC/DC modules for aerospace, and new-generation programmable solutions targeted at automotive and new-energy testing) confirm the pace of innovation and vendors’ efforts to capture fast-growing adjacencies.
Strategic implications for 2026 corporate planning
Executives must translate the macro growth trajectory and the competitive snapshot into concrete actions. We highlight five priorities that should be in every 2026 plan for suppliers, OEMs, and strategic buyers:
- Design for supply resilience: Act now to qualify second- and third-source suppliers for key passives, power semiconductors, and magnetics. Consider inventory cushions for long-lead items and negotiate collaborative demand-forecasting arrangements with strategic suppliers.
- Targeted product bets: Allocate R&D spend to SiC/GaN-enabled power stages, compact thermal management, and bidirectional/regenerative features that are demonstrably monetizable in EV and data-center test markets. Prioritize software APIs and telemetry for higher-margin recurring revenue (service, calibration, firmware subscriptions).
- Commercial strategies that capture premium demand: For those with precision- or high-power capabilities, pursue vertical value plays (test-to-system bundles) and performance-based contracts where customers pay for delivered throughput or power-conversion efficiency gains.
- Regional and policy-aware sourcing: Map your supply chain exposure to export-control regimes and critical-mineral policies. Localized manufacturing and assembly, or at least buffered subassembly strategies, can mitigate regulatory and transport risks.
- M&A and partnership discipline: The market’s growth and mid-level concentration create opportunities to acquire complementary capabilities (e.g., regenerative load technology, high-voltage modules, or software/IP). Target deals that accelerate time-to-market for SiC/GaN and bidirectional systems rather than scale-only consolidations.
Operational metrics we recommend for 2026
To convert strategy into accountable execution, monitor a concise set of KPIs:
- Supplier risk index (weighted by lead-time and single-source exposure for top 20 components)
- R&D time-to-deploy for SiC/GaN-enabled platforms (months)
- Revenue mix from software/recurring services as a percent of product revenue
- Average order lead time and on-time delivery to key test/OEM customers
- Gross margin delta attributable to component cost shifts and hedging actions
What the full report delivers — practical content (preview)
PW Consulting’s full Worldwide DC Power Supplies and Electronic Power Loads Market report transforms the macro outlook into deployable insight: rigorous historical and forecast market sizing (2020–2032), segmentation by product family and end market, supply-chain exposure maps, vendor scorecards, detailed competitor profiles, and playbooks for procurement and product leadership. Importantly for strategists, the report contains scenario analyses that quantify the P&L and ROI implications of alternate supply-risk and technology-adoption paths. To honor the “trailer” principle of this briefing, segmented tables and the granular company-by-company quantitative rankings are reserved for subscribers and report purchasers.
How to use the report for 2026 decision cycles
- Board-level planning: Use the market-size trajectory and scenario outputs to stress-test capex and M&A assumptions during annual planning cycles.
- Product roadmap prioritization: Apply the supplier risk and component-cost scenarios to re-score product initiatives by time-to-market and margin resilience.
- Procurement negotiations: Leverage the supply-chain maps and price-trend analyses to structure multi-year supplier commitments, options, and inventory pooling agreements.
- Go-to-market refresh: Tailor channel and direct-sales motions based on the vendor scorecards and the identified high-growth subsegments (detailed in the subscriber report).
Final perspective and next steps
The DC power supplies and electronic power loads market offers a clear growth runway, but 2026 will be the year that separates strategic foresight from tactical reaction. Companies that proactively shore up supply chains, invest in SiC/GaN-enabled platforms, and convert product performance into recurring revenue streams will capture disproportionate upside as the market scales. Conversely, firms that wait for component prices and lead times to normalize risk margin erosion and lost design-wins.
PW Consulting’s full report provides the granular segmentation, vendor benchmarking, and scenario modeling necessary to operationalize the guidance above. For access to the complete dataset, supplier scorecards, and tailored advisory engagements to translate these findings into a 90–180 day execution plan, visit the PW Consulting research portal or contact our industry practice lead for a brief walk-through.
For detailed analysis of this topic, please visit the official page: Worldwide DC Power Supplies and Electronic Power Loads Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com