

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting Forecast: Worldwide Poly Ferric Chloride Market to Expand at a 5.51% CAGR

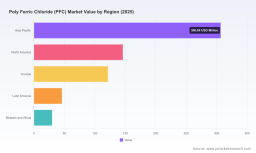
Worldwide Poly Ferric Chloride (PFC) Market: Strategic Outlook for 2026 Decision-Making
PW Consulting’s newest market study on the Worldwide Poly Ferric Chloride (PFC) market is designed as an operational playbook for executives preparing critical 2026 choices. The PFC market is no longer a niche chemicals story — it sits at the intersection of urban water infrastructure renewals, industrial decarbonization programs, and evolving global trade and regulatory regimes. Our report synthesizes a multi-year historical view (2020–2025) with a forward-looking forecast period (2026–2032) to convert ambiguity into executable options.
Worldwide Wireless Smart Lamp Market
Executive snapshot
Between 2020 and 2025 the global PFC market expanded from approximately USD 510 million to USD 650 million, reflecting steady demand growth through municipal and industrial channels and episodic supply-side interruptions. Looking forward, our base-case projection anticipates the market reaching roughly USD 945.5 million by 2032, underpinned by a compound annual growth rate (CAGR) of 5.51% across the 2026–2032 forecast window. These headline metrics frame the strategic choices companies will confront in 2026: invest, consolidate, diversify procurement, or reposition product portfolios.
Worldwide 1,2,6-Hexanetriol Market
Why this report matters for 2026 decisions
- Decision-ready intelligence: The report marries quantitative forecasting with qualitative scenario analysis so commercial leaders can translate a 5.5% mid-single-digit growth trajectory into revenue, margin, and capacity planning.
- Risk-to-reward mapping: We identify which near-term shocks (raw-material price volatility, trade actions, regulatory gating) are transient and which will reconfigure supply chains over the medium term.
- Competitive playbook: Practical vendor benchmarking and capability matrices enable procurement and product teams to prioritize partners and target competitive gaps that matter for 2026 procurement cycles.
Market trajectory and structural drivers
The overall growth profile is solid but non-linear. Growth through 2020–2025 reflected a mix of steady municipal capex and pockets of industrial demand; disruptions in 2022–2023 highlighted the sensitivity of PFC production to raw-material and utility inputs. On the supply side, players face concentrated cost drivers — hydrochloric acid and iron feedstocks — alongside energy and logistics constraints. On the demand side, rising urban population, stricter effluent limits, and expanded industrial water reuse programs are persistent tailwinds.
Worldwide Snap-off Knife Market
Crucially for 2026 planning, the market is moderately fragmented: the three-largest suppliers account for just over one-fifth of global production, while the five-largest are responsible for roughly one-third. That concentration profile implies meaningful room for regional producers to defend share, while also leaving strategic space for M&A and scale-driven cost reductions among larger players.
Key dynamics shaping 2026 strategy
- Raw-material volatility and procurement posture: Historical episodes in 2022–2023 showed hydrochloric acid and ferric chloride spot prices can spike materially following supply disruptions. Procurement teams should adopt multi-tier sourcing and proactively hedge exposure to feedstock cycles — spot-only procurement will be increasingly risky.
- Regulatory and trade headwinds: Regulatory regimes such as REACH require robust registration and data packages for imports, elevating the bar for non-local suppliers. Trade measures — including duties impacting certain import corridors — create incentives for near-shoring or tariff mitigation strategies.
- Product differentiation and R&D: New higher-purity and specialized PFC grades are emerging, aimed at advanced wastewater and reuse markets. Suppliers investing in application-specific formulations and stability/solubility improvements will command pricing premia in targeted industrial segments.
- Capex and capacity alignment: Recent capacity increases by established players have a two-fold strategic implication: they signal confidence in medium-term demand, but they also require disciplined offtake agreements and geographic distribution strategies to avoid cycle-driven oversupply.
Competitive landscape: what to watch in 2026
The PFC ecosystem combines multi-national incumbents with regional specialists. Our competitive analysis focuses on capability, route-to-market, product breadth, and strategic moves that directly affect 2026 positioning.
- Kemira Oyj (Helsinki): A global water-chemicals provider with integrated R&D and broad municipal and industrial channels. Kemira’s recent European capacity expansion signals a readiness to capture incremental municipal and industrial tenders. For customers, Kemira represents scale, regulatory compliance assurance, and advanced technical services.
- Feralco AB (Halmstad): A European iron-coagulant specialist with deep presence in drinking water and sludge management. Feralco’s strength is application-level expertise and regional regulatory know-how that eases market access for utilities subject to stringent safety standards.
- SNF Group (France): Renowned for polymer and coagulant technology, SNF’s complementary product set allows bundled offerings — a tactical advantage in large water-treatment projects where single-vendor coordination reduces integration risk.
- USALCO LLC (Baltimore): A North American player focused on potable and wastewater segments with domestic manufacturing advantages — particularly relevant where trade measures or logistics bottlenecks raise landed-costs of imports.
- Chinese suppliers (representative firms): Several leading Chinese producers continue to supply global markets at scale. Their competitiveness is shaped by feedstock access and export logistics; however, regulatory barriers and trade duties in certain jurisdictions alter their relative attractiveness for 2026 procurement decisions.
Two recent developments are illustrative: (1) an established European supplier expanded coagulant capacity in 2023, reflecting anticipated municipal project flows; (2) a Chinese producer launched a high-purity grade in 2022 targeted at advanced wastewater streams. These moves underscore a bifurcation: scale investments to serve high-volume municipal demand, and product innovation to serve high-margin, performance-sensitive industrial niches.
Core contents of the PW Consulting report (practical, actionable elements)
- Quantitative forecast model (2026–2032) with scenario toggles for raw-material shocks, tariff regimes, and regulatory tightening.
- Demand-by-use-case mapping (municipal, industrial reuse, paper & pulp, specialty) with adoption curves and addressable-market estimates by channel (note: the report contains the full segmentation tables and underlying assumptions).
- Supply-chain heat maps showing production nodes, logistics bottlenecks, and critical single-source exposures.
- Supplier capability matrices and commercial scorecards to support RFP design and supplier shortlisting.
- Regulatory compliance playbook (REACH, export controls, customs classifications) and a checklist for importers and in-region manufacturers.
- Procurement strategies — from fixed-price multi-year offtakes to indexed spot-mix — with modeled P&L impacts under the most likely 2026 scenarios.
- M&A and partnership roadmaps, including valuation heuristics and integration risks specific to PFC assets.
Strategic recommendations for executives preparing 2026 plans
- Design multi-scenario procurement contracts: Move away from pure spot exposure. Blend indexed contracts, capacity reservations, and local supply options to limit volatility in feedstock-driven cost lines.
- Prioritize product portfolio sophistication: Allocate R&D and commercial focus to differentiated grades that address reuse and stricter effluent standards. These segments show above-average willingness to pay for performance and technical support.
- Regionalize where tariffs or regulation raise entry costs: For markets subject to import duties or onerous registration regimes, near-shore manufacturing or licensed local partnerships will be less costly than attempting to compete on landed price alone.
- Use capacity signals as a sourcing lens: Track announced expansions and new-grade launches to anticipate pricing cycles. Where suppliers commit capex, secure offtake or co-development arrangements to lock favorable terms.
- Build a compliance-first GTM approach: Design product dossiers and safety data packages proactively; regulatory delays are a predictable cause of missed RFPs and lost market share in 2026.
- Evaluate M&A selectively for scale and tech: Given the market’s moderate fragmentation, targeted acquisitions can accelerate access to new geographies or proprietary formulations — but only when integration plans preserve technical capabilities and regulatory compliance.
How to use the report in boardroom and procurement cycles
Translate the report’s scenarios into the three documents that matter for 2026:
- Capital-expenditure justification — link forecast demand to capacity and payback models under both conservative and aggressive demand scenarios.
- Procurement policy — specify contract forms, indexation clauses, and supplier KPIs calibrated to feedstock risk sensitivity.
- Commercial strategy brief — align sales incentives and pricing templates to segments where product differentiation yields premium capture.
Access and next steps
This release is a strategic preview: it demonstrates the analytical depth and operational frameworks within PW Consulting’s full Worldwide PFC Market report. For procurement leaders, product strategists, and corporate development teams set to finalize 2026 plans, the full report contains the actionable segmentation, supplier benchmarking, and the downloadable model that operationalizes the scenarios summarized here. Those ready to convert insight into a concrete 2026 playbook should consult the complete study for the segment-level tables, modeled contract templates, and supplier scorecards.
PW Consulting continues to monitor raw-material and regulatory signals that will pivot near-term supply-cost dynamics. For bespoke advisory — including model customization, supplier diligence, or transaction support tied to the PFC market — our specialists are available to convert the research into transaction-ready outcomes.
For detailed analysis of this topic, please visit the official page: Worldwide Poly Ferric Chloride (PFC) Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com