

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Worldwide Industrial Control Automation Small PLC Market to Expand at 5.85% CAGR Through 2032, Report Finds

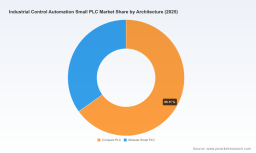
Worldwide Industrial Control Automation Small PLC Market — Strategic Outlook for 2026 Decision-Makers
PW Consulting’s latest market intelligence on the Worldwide Industrial Control Automation Small PLC market is designed for C-suite executives, product strategists, procurement leads, and systems integrators preparing capital, sourcing, and technology decisions in 2026. Built on a 2020–2025 historical base and a 2026–2032 forecast horizon, our analysis anchors on rigorous bottom-up modeling and primary validation. At a macro level, the small PLC market sits on a steady growth trajectory — with a compound annual growth rate of 5.85% and a 2025 market base of approximately USD 4.52 billion—projected to exceed USD 6.7 billion by 2032. This briefing summarizes the strategic value of the full report and highlights the practical levers leaders should prioritize in 2026, while reserving granular segment and share detail for subscribers and report purchasers.
LV Electric Panels Market
What the Report Delivers — Operationally Actionable Intelligence
-
Strategic market sizing and scenario planning: detailed, auditable forecasts built from installed-base tracking, vendor shipment data, and end-market consumption modeling. Scenarios include accelerated automation adoption, semiconductor supply shocks, and regulatory-driven retrofit cycles.
Worldwide Acrylic Binders Market -
Vendor benchmarking and playbooks: qualitative and quantitative scorecards across technical capability, security posture, channel strength, service footprint, and roadmap transparency. The report maps vendor advantages for machine builders, OEMs, and brownfield retrofit programs.
Worldwide Machine Learning in Education Market -
Procurement and sourcing checklist: an actionable RFP template, TCO model calibrated for small-PLC lifecycles (hardware, firmware maintenance, spare parts, and integration costs), and supplier negotiation levers for 2026 purchasing rounds.
-
Technical adoption guides: recommended architectures for compact and modular small-PLC deployments, integration patterns for IIoT/MES connectivity, and migration paths to enable motion control, safety, and energy management without wholesale system replacements.
-
Risk and compliance playbook: firmware lifecycle management, cybersecurity incident response protocols, and regulatory alignment guidance tailored to the latest advisories and energy-efficiency mandates.
-
Go-to-market motions: channel segmentation and partnership strategies for vendors and integrators targeting opportunities across discrete manufacturing, food & beverage, packaging, and machine building.
Why This Matters for 2026 Decisions
-
Capital allocation needs to be precise. With a predictable multi-year growth path and steady CAGR, 2026 is a pivotal year to prioritize investments in modular control platforms that scale with production requirements. Our TCO models show that choices made at procurement materially affect lifecycle costs and upgrade flexibility over a 7–10 year horizon.
-
Cybersecurity is now a procurement criterion. Following multiple advisories affecting small PLC lines, buyers must require secure boot, cryptographic firmware signing, encrypted communications, and defined update cadences as non-negotiables. The report provides contract language and technical checks to enforce that baseline.
-
Supply chain resilience influences vendor selection. Ongoing investments into semiconductor capacity globally and strategic government incentives are reducing risk, but near-term component tightness and geopolitical diversification will persist. Our scenarios offer hedging strategies—dual-sourcing prioritization, local stocking policies, and modular hardware designs that reduce dependence on single IC footprints.
-
Labor dynamics and sustainability mandates are accelerating adoption. Labor shortages and energy-efficiency regulations are increasing demand for small PLCs equipped with integrated motion control, power monitoring, and predictive maintenance capabilities—features that materially improve asset utilization and regulatory compliance.
Competitive Landscape — Who Matters and Why
The market combines entrenched global automation leaders, specialist OEMs, and nimble innovators. Buyers should evaluate suppliers along three vectors: platform breadth (hardware + software + services), openness (standards support and interoperability), and agility (product cadence and customization).
-
Global integrators and broad-portfolio leaders — companies such as Siemens, Rockwell Automation, Schneider Electric, Mitsubishi Electric and ABB — remain influential due to deep channel networks, broad product portfolios, and enterprise-grade support. Recent product refreshes and compact PLC introductions from these vendors underscore a push to simplify machine-level automation while embedding stronger connectivity and safety features.
-
PC-based and high-performance control specialists — Beckhoff and select European players — are advancing real-time control frameworks that appeal to high-precision machine builders seeking deterministic performance and richer HMI integration.
-
Cost-focused and integrated HMI vendors — Unitronics, Delta, and several Asia-based vendors — continue to compete on price-to-function value for OEMs and SMEs, often bundling PLC and HMI in compact form factors to reduce integration overhead.
-
Modular I/O and open-architecture proponents — WAGO, Phoenix Contact, and others — differentiate on interoperability and fieldbus/IIoT flexibility that simplifies brownfield upgrades.
Recent product developments validate these dynamics: a major vendor announced a next-generation intelligent logic controller in early 2026 with expanded function capacity and enhanced security; another expanded its micro-controller line in late 2025 emphasizing connectivity and simplified machine integration. Trade-show reveals in 2025 showcased AI-assist features and PC-based control evolution—indicating vendor roadmaps emphasize connectivity, security, and motion capabilities.
Strategic Playbook for 2026
-
Prioritize modularity and upgradeability over lowest-cost hardware. Select controllers with headroom for I/O expansion and software licensing that enables safe incremental upgrades.
-
Mandate security metrics in procurement: secure boot, signed firmware, role-based access, and demonstrable vulnerability disclosure policies.
-
Require standards compliance and open protocols (e.g., Ethernet-based industrial protocols and common fieldbuses) to future-proof integration with IIoT and MES layers.
-
Establish a two-tier sourcing strategy for critical components: maintain strategic spare inventories and pre-qualified second-source vendors to mitigate supply disruptions.
-
Incentivize vendors for sustainability: require energy-monitoring features and support for power-optimization profiles that align with corporate decarbonization targets.
-
Embed lifecycle clauses in contracts: defined firmware support windows, end-of-life notifications, and rights to security patches.
-
Leverage pilot programs: deploy compact PLC pilots to capture operational metrics (OEE uplift, labor-hours saved, and energy savings) and build internal business cases before scaling.
Risk Scenarios & Mitigation
-
Semiconductor supply shock: mitigate via design-for-component-flexibility, qualified alternates, and buffer inventory strategies.
-
Cybersecurity incident affecting field deployments: execute predefined incident response playbooks (network segmentation, device quarantine, forensic captures) and demand vendor cooperation clauses in SLAs.
-
Regulatory tightening on energy or emissions: fast-track retrofits with controllers that provide built-in power telemetry and demand-response capabilities.
-
Accelerated consolidation among vendors: maintain competitive RFQ processes and preserve migration paths to avoid lock-in risk.
How Leaders Use This Report in 2026
-
Board-level prioritization: translate market momentum and vendor roadmaps into capital allocation and M&A scouting for adjacent control technologies.
-
Procurement and supply chain: employ the report’s TCO and sourcing templates to standardize specifications across global plants and reduce fragmentation.
-
Product and R&D: align feature roadmaps with market demand for security, motion control, and IIoT readiness—using prioritized use-cases and quantified adoption curves from the report’s scenario analysis.
-
Systems integrators and OEMs: use vendor scorecards and channel maps to select partners with the right mix of product features, support footprint, and integration tools.
Next Steps — Where to Find the Full Intelligence
This briefing outlines the strategic contours of PW Consulting’s full Worldwide Industrial Control Automation Small PLC Market report. The comprehensive study includes detailed regional and vertical segmentation, vendor market shares and pricing benchmarks, product roadmaps, and downloadable procurement templates that are intentionally withheld from this preview to preserve the investigative value of the full deliverable.
For access to the complete dataset, vendor scorecards, and the downloadable playbooks and models that support rapid 2026 decision-making, please visit PW Consulting’s report page or contact our advisory team for a tailored briefing and licensing options.
For detailed analysis of this topic, please visit the official page: Worldwide Industrial Control Automation Small PLC Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com