

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Worldwide Smart Zero Gravity Bed Market to Top USD 3,975.76 Million by 2032, Growing at an 11.85% CAGR

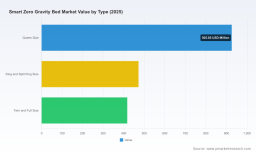
Worldwide Smart Zero Gravity Bed Market — Strategic Preview for 2026: Why C-Suites and Investors Must Recalibrate Now
PW Consulting’s latest market study on the Worldwide Smart Zero Gravity Bed Market (base year 2025; forecast 2026–2032) delivers a focused strategic lens for leadership teams preparing decisions in 2026. With the market expanding at a compound annual growth rate (CAGR) of 11.85% through the forecast horizon, the sector has moved decisively from niche therapeutic applications toward mainstream consumer and institutional adoption. Our analysis shows a market that roughly doubled in scale over the recent five-year window and is now positioned to approach a fourfold expansion by 2032 — a structural shift demanding proactive product, go-to-market, and regulatory strategies.
Worldwide Smartphone Screens Market
Why this preview matters for 2026 decision cycles
-
Momentum is predictable but not uniform: The industry’s average growth trajectory (CAGR 11.85%) masks pockets of rapid innovation and induced demand driven by integrated smart features, telehealth-enabled care pathways, and reimbursement clarity. Companies that align investments with these inflection points will capture disproportionate share.
Worldwide Email List Cleaning Service Market -
Concentration offers both threat and opportunity: Market concentration metrics indicate a moderately consolidated sector — the top three players control a meaningful but non-dominant share, and the top five widen that influence. This creates an environment where scale advantages coexist with white-space opportunities for focused entrants and specialized OEMs.
Battery Operated Mobile Power Market -
Regulatory and reimbursement dynamics are now operational drivers: Updated durable medical equipment (DME) policies and coverage rules require manufacturers and channel partners to embed compliance and clinical evidence into product design and commercial models. Execution on these fronts is becoming as important as product ergonomics.
Market trajectory at a glance (strategic highlights)
Our top-line market sizing traces the transition from early adoption to structural growth. Measured against our 2025 baseline, the market grew meaningfully from the 2023 vintage and is forecast to nearly double by the end of the 2026–2032 period. This expansion is being powered by three concurrent forces: technology convergence (embedded sensors, AI-driven sleep management, and connected actuation), shifting care delivery models (home-first rehabilitation and remote monitoring), and consumerization of sleep health. For 2026 strategic planning, executives should treat these forces as investment priorities rather than speculative trends.
Actionable intelligence embedded in the report
-
Scenario-based revenue models: Our report supplies base, upside, and downside scenarios to stress-test capital allocation, pricing experiments, and channel investments. These models incorporate sensitivity to reimbursement policy shifts and component supply volatility.
-
Go-to-market playbooks: Detailed route-to-market matrices for OEMs, contract manufacturers, and retailers — including recommendations on channel mixes, partnership archetypes, and margin structures tailored to different strategic objectives (premium brand growth, volume play, clinical/evidence-led sales).
-
Product feature roadmap templates: Prioritized product requirements for three strategic archetypes (clinical-first, premium consumer, and cost-optimized volume) that map engineering effort to measurable commercial outcomes.
-
Regulatory & reimbursement mapping: A practical compliance checklist and stakeholder map referencing recent CMS guidance on hospital beds as DME (including HCPCS considerations), and operational implications for ordering, documentation, and supplier accreditation.
-
Supply chain and cost benchmarking: Component sourcing strategies, outsourcing thresholds, and contingency planning for actuator and electronics constraints that can compress margins if unaddressed.
-
M&A and partnership playbook: Deal-screening criteria, integration risk matrices, and valuation multipliers calibrated to current market dynamics and consolidation patterns.
Competitive landscape — what the leading players reveal
Our competitive analysis focuses on firms that illustrate the strategic archetypes shaping the market. Each company’s positioning offers lessons for incumbents and newcomers alike.
-
SonderCare (London, Ontario) — Represents the clinical-first archetype: premium home hospital solutions emphasizing therapeutic positioning (including zero gravity), catering to long-term care and recovery settings. Their playbook demonstrates how clinical credibility and specialized features enable higher ASPs and clinical channel access, but also require persistent evidence generation and service capabilities.
-
Ergomotion (Santa Barbara, CA) — The volume-engineering and retail-supply leader: a global supplier of adjustable bases with deep relationships across mattress OEMs and mass retail channels. Their recent 20th anniversary and showroom investments underscore the value of brand-agnostic, scalable manufacturing and retailer enablement as routes to durable distribution advantages.
-
Leggett & Platt (U.S. adjustable beds division) — Industrial-scale OEM with an emphasis on modular platforms, programmable presets, and integration-ready architectures. Their scale plays to supplier leverage and channel breadth; the strategic takeaway is that modularity plus robust distribution can lock in preferred supplier status with large retailers and healthcare systems.
-
Tempur-Pedic — Premium consumer integration leader: combines advanced bases (smart features, snore response, Sleeptracker-AI) with a premium mattress franchise. Their success highlights the commercial premium available to companies that fuse sleep data platforms with ergonomics and an elevated retail experience.
-
Hebei Chibang Medical Equipment — A manufacturing-led competitor focused on hospital and post-operative segments, demonstrating how cost-efficient electronics integration and regulatory alignment can win institutional tenders in emerging markets.
-
Zero-G Beds (India) — Regional OEM and homecare specialist, illustrating that localized manufacturing and medical-grade features can create defensible positions in large, underserved domestic markets.
These profiles point to three critical competitive playbooks: platform scale + channel depth; clinical differentiation + service; and regional manufacturing + regulatory fit. Winning companies will combine two or more of these playbooks with clear investment sequencing.
Regulatory and reimbursement dynamics — from noise to strategic signal
-
Coverage pathways: Medicare Part B continues to cover hospital beds as durable medical equipment when clinical criteria are met, with HCPCS codes and documentation requirements driving supplier compliance and billing workflows. Manufacturers that design traceable clinical positioning features and provider-ready documentation lower adoption friction.
-
Medical necessity and ordering: Recent CMS clarification emphasizes face-to-face practitioner evaluation and demonstrable inability to meet positioning needs with ordinary bedding. This increases the importance of clinician education, point-of-care evidence kits, and training programs for channel partners.
-
Market segment drivers: Product designs addressing elderly care, post-operative recovery, and long-term care show the strongest alignment with reimbursement criteria. However, consumer demand for sleep health and home wellness expands total addressable market beyond purely reimbursable channels.
Strategic recommendations for 2026 planning
-
Invest in modular architectures now: Prioritize engineering that separates clinical modules (actuation, pressure management, articulating frames) from consumer-smart layers (sensors, AI). This enables faster regulatory iterations and multiple go-to-market plays without full redesigns.
-
Embed evidence generation into product development: Short, targeted clinical studies that demonstrate positioning benefits (pressure redistribution, circulation) will accelerate adoption in clinical channels and strengthen reimbursement claims.
-
Forge distribution partnerships with clear roles: Retailers, DME suppliers, and health systems require differentiated commercial models. Consider hybrid partnerships that combine retail reach with clinical referral programs and bundled service offerings.
-
Mitigate supply risk through dual-sourcing and design for substitution: Actuator and electronics availability are strategic chokepoints; design choices that allow supplier substitution without losing feature parity preserve margin and launch timelines.
-
Price for value, not cost: As smart features proliferate, pricing should reflect measured clinical or quality-of-life outcomes. Demonstrable benefits justify premium positioning while enabling participation in reimbursable channels where appropriate.
-
Evaluate M&A for capability infusion: Bolt-on deals that bring telehealth platforms, clinical evidence pipelines, or regional manufacturing can be more accretive than broad horizontal consolidation at current valuation multiples.
What the full report delivers (operational content)
PW Consulting’s comprehensive report contains detailed methodology notes, quarterly-trended market sizing (historical 2020–2025 and forecast 2026–2032), supplier benchmarking, price and cost models, channel maps, regulatory checklists, and prioritized strategic initiatives for each corporate archetype. It includes scenario-based financial models, sensitivity analysis for component costs and reimbursement shifts, and an M&A compendium with transaction rationale and integration risk scoring. The document is intentionally dense with executable checklists and templates designed for rapid adoption by product, commercial, and corporate development teams.
Next steps — for executives who need to act in 2026
-
Use the report’s scenario suite to stress-test your 2026 budget and roadmap against reimbursement tightening and component price swings.
-
Schedule a strategy workshop with PW Consulting to translate the playbooks into a 90–180 day implementation plan (product, regulatory, and channel milestones).
-
Engage our M&A advisory to validate inorganic options mapped to your strategic gaps — whether capability, geographic presence, or platform acceleration.
PW Consulting’s preview establishes the strategic contours you need to decide in 2026: the market is large, growing at a sustained double-digit CAGR, and split across distinct competitive archetypes. The levers of success are now well understood — but their execution requires discipline across product architecture, clinical evidence, channel orchestration, and supply chain resilience.
Learn more
This release serves as a concise strategic preview. For full market tables, detailed segment analysis, competitor scorecards, and the operational playbooks described above, access the complete Worldwide Smart Zero Gravity Bed Market report on the PW Consulting portal or contact our advisory desk to arrange a briefing tailored to your organization’s strategic objectives.
For detailed analysis of this topic, please visit the official page: Worldwide Smart Zero Gravity Bed Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com