

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Worldwide Wood Briquettes Market to Expand at 7.35% CAGR — From USD 925.4 Million in 2025 to USD 1,520.34 Million by 2032

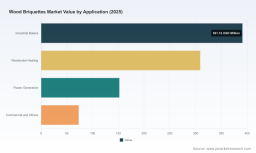
Worldwide Wood Briquettes Market: Strategic Imperatives for 2026 — PW Consulting Intelligence Brief
As policymakers tighten carbon targets and energy buyers re-optimize fuel baskets for resilience and emissions reduction, wood briquettes have moved from niche to mainstream in the global low‑carbon fuel mix. PW Consulting’s new Worldwide Wood Briquettes Market study — anchored on a 2025 base and projecting through 2032 — synthesizes five years of historical dynamics (2020–2025) and a robust forward view (2026–2032). The market is forecast to continue growing at a compound annual growth rate (CAGR) of approximately 7.35% over the forecast window, expanding materially from mid‑2020s scale into the early 2030s. This briefing highlights the strategic value of the full report for corporate decision‑makers preparing capital allocation, commercial strategy, and regulatory readiness in 2026.
Construcion Machinery Slip Rings Market
Market at a glance: trajectory and strategic meaning
Our topline sizing shows a clear, multi‑year acceleration: the global wood briquettes market passed important adoption thresholds during the early 2020s and, per our modeling, is poised to roughly double in size across the coming decade. That pace is consistent with commodity substitution dynamics, policy support for biomass where lifecycle emissions criteria are met, and ongoing demand for dispatchable, storable solid biomass for both residential heating and industrial boilers.
Bulk Density Testers Market
- Why the numbers matter for 2026: a market growing in the high single digits annually creates both scale opportunities (volume efficiencies, fixed‑cost dilution in manufacturing) and new competitive pressures (price convergence, product differentiation).
- Investment timing: capacity additions and feedstock contracts executed in 2026 will affect sourcing economics and market share through the end of the decade; actors who move early to secure feedstock and certifications will capture disproportionate value.
Drivers and dynamics shaping choices
Several converging forces create a window of strategic opportunity — and risk — for 2026 planning:
Worldwide Liquid Optically Clear Adhesive (LOCA) Market
- Policy and standards: Regional renewable energy directives now attach lifecycle greenhouse gas thresholds and sustainability criteria to solid biomass. Compliance is non‑negotiable for market access in major markets; firms must evidence substantial GHG savings against fossil baselines and align to relevant national incentive programs.
- Quality and certification: Premium product classes governed by recognized standards (for ash, fines and combustion performance) sustain a price premium and broader market acceptance among residential and commercial buyers. Certification programs and lab testing have become a commercial gatekeeper.
- Feedstock and input economics: Sawmill residues and wood chips remain the dominant feedstock. Their local availability and logistics economics drive plant siting, export flows and margins. Buyers and producers must lock feedstock contracts or pursue vertical integration to avoid seasonal tightness.
- Channel bifurcation: The market bifurcates into premium, certified products for households/retail and higher‑volume industrial grades for boilers and co‑firing. Each channel demands different packaging, distribution and service models.
Supply landscape: fragmentation, specialisation and what it means
The competitive structure remains relatively fragmented. The concentration of the top three and top five firms is modest by global fuel market standards, which signals an open field for scale plays and consolidate‑or‑specialize strategies. For 2026 planners this implies two parallel pathways:
- Grow scale through targeted acquisitions and capacity expansion to harvest manufacturing economies and secure long‑term feedstock; or
- Double down on premium differentiation — certification, traceability, and branded retail channels — to protect margins where scale is less decisive.
Key industry players illustrate these strategic choices:
- Lignetics International (USA) — well positioned in branded residential fuel and specialty compressed logs; their model demonstrates the power of customer facing brand equity and distribution partnerships in mature North American retail channels.
- Binderholz GmbH (Austria) — recently announced capacity expansion at its Austrian facilities to meet higher regional demand, underscoring the strategic value of proximate feedstock and integrated sawmill‑to‑fuel operations.
- Pfeifer Group (Austria) — offers RUF‑type briquettes as part of a broader renewable wood energy portfolio; integration across product families reduces sales friction for industrial buyers seeking single‑vendor solutions.
- Holzindustrie Torgau (Germany) — the company’s recent update to DINplus certification exemplifies how certification renewals can open higher‑margin channels and shorten procurement cycles with institutional buyers.
- Südruss Holz and Bear Mountain Forest Products — examples of firms that leverage manufacturing quality and material selection (e.g., dense hardwoods) to produce long‑burning residential products with strong niche loyalty.
- Jay Khodiyar Industries (India) — a case of export‑oriented production where cost competitiveness and logistics networks enable participation in global boiler fuel markets.
Operational and regulatory risks to manage in 2026
- Lifecycle GHG compliance: meeting regional emissions savings thresholds is now a commercial requirement in many purchasing tenders. Firms must be ready to provide robust carbon accounting and supply chain traceability.
- Certification bottlenecks: testing and certifying new product lines can introduce weeks to months of delay; proactive certification roadmaps are a low‑cost way to accelerate market access.
- Feedstock volatility and logistics: while residual streams are widespread, local bottlenecks (seasonality, competing uses) can spike delivered costs. Securing multi‑year supply agreements and investing in buffer inventory or co‑location with sawmills reduces exposure.
- Price pressure on commoditised grades: commoditised industrial briquettes face margin compression unless paired with long‑term offtake or value‑added services (e.g., bundled logistics, ash management services).
Concrete strategic imperatives for 2026 decision‑makers
Our analysis translates into a focused playbook for executives preparing budgets and business plans for 2026:
- Prioritise certification and carbon proof points. Allocate capex and process resources to secure recognised certifications and independent lifecycle verification — this unlocks public incentive programs and institutional buyers.
- Secure feedstock via contracts and vertical integration. Use 2026 to lock medium‑term supplies with index‑linked pricing or pursue minority stakes in sawmills to stabilize feedstock margins.
- Consider bolt‑on M&A in key regional hubs. Given the market’s low top‑three concentration, targeted acquisitions can quickly scale capacity and expand geographic reach without confronting entrenched global incumbents.
- Differentiate through product and channel segmentation. Invest in premium, low‑ash product lines for retail and service contracts for industrial clients to preserve margin even as commoditised volumes grow.
- Embed scenario planning and stress tests into capital allocation. Run 3‑5 scenarios covering feedstock price spikes, tighter lifecycle thresholds, and rapid demand swings in winter seasons to stress-solve capacity utilization and working capital needs.
Commercial playbook: near‑term wins to longer‑term positioning
Actions that can be executed within 6–18 months versus those that require multi‑year commitment should be sequenced to capture optionality:
- 6–12 months (quick wins): accelerate certification renewals, negotiate offtake agreements with industrial boiler operators, and pilot branded retail packs with selected distributors.
- 12–36 months (capacity & contracts): expand production lines where feedstock is secured, formalise export logistics for target markets, and implement traceability systems aligned with regional regulatory requirements.
- 36+ months (transformational): evaluate vertical integration into forestry residues, invest in densification and automation technologies, and build carbon project pipelines to monetise lifecycle improvements.
What is contained in the full PW Consulting report
The complete Worldwide Wood Briquettes Market report is a hands‑on, decision‑oriented deliverable designed for corporate strategy, M&A teams, and procurement leads. It includes:
- A transparent market sizing and forecast model (2020–2032) with scenario toggles for feedstock and policy shocks.
- Segmented demand drivers and channel economics by product type and application (methodology and assumptions provided; core split tables are reserved for the full report to preserve commercial exclusivity).
- Comprehensive competitor profiles, recent developments and capability heatmaps to inform partnership or acquisition targets.
- Practical playbooks — step‑by‑step checklists for certification, feedstock contracting, plant siting, and export compliance.
- Risk matrices and financial return templates that quantify payback under alternative pricing and policy scenarios.
- Supplier and technology vendor directory, plus a curated list of due diligence questions for feedstock and logistics providers.
Why firms should prioritise obtaining the full report for 2026 planning
The market momentum we measure creates a narrow window where operational moves — certification, feedstock contracts, targeted capacity additions — have outsized effects on medium‑term economics. Our detailed models and playbooks turn industry signals into executable steps. For leadership teams deciding where to allocate capital in 2026, the combination of growth, policy tightening and supply fragmentation raises a simple truth: strategic clarity now converts into durable advantage later.
PW Consulting’s Worldwide Wood Briquettes Market report delivers the calibrated insight required to convert that window into measurable competitive outcomes — from pricing and procurement to M&A and product strategy. For executives building resilient, low‑carbon fuel businesses in 2026, the full report is the operational handbook you will consult throughout the year.
For detailed analysis of this topic, please visit the official page: Worldwide Wood Briquettes Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com