

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Worldwide Marine Satellite Internet System Market Poised to Grow at a Robust 11.22% CAGR Through 2032, New Insight Report Finds

Worldwide Marine Satellite Internet System Market: Strategic Imperatives for 2026 — PW Consulting Preview
PW Consulting releases a new, executive-focused preview of our Worldwide Marine Satellite Internet System Market research — a practical, decision-grade briefing designed to orient boardrooms, procurement teams, and maritime operators as they set 2026 connectivity strategy. This preview highlights high-conviction, data-driven insights from our full study (base year 2025; forecast 2026–2032) while reserving proprietary, line-item granularity for the full report. Our objective: demonstrate the analytical depth you need to act, while guiding you to the full dataset and toolset that underpin confident capital and operational choices.
Travel Risk Management Tools Market
Macro view: growth, scale and structural shifts
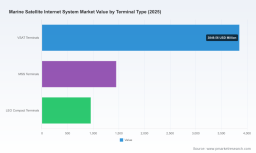
The marine satellite internet market is now large, growing, and reconfiguring quickly. Using a bottom-up approach validated against vendor financials, operator interviews and observed vessel deployments, PW Consulting estimates the market at approximately USD 6.25 billion in 2025 and projects a continuation of robust expansion in 2026 and beyond — driven by hybrid multi-orbit architectures, crew welfare demands, vessel digitalization, and new regulatory requirements. Our modeled compound annual growth rate for the forecast period is 11.22%, producing a materially larger addressable market by 2032.
Worldwide Dental Piezoelectric Ultrasonic Units Market
Two structural forces underpin this growth. First, multi-orbit service architectures (GEO HTS, MEO/LEO constellations and resilient narrowband overlays) are converging into commercially packaged solutions that meet both operational uptime targets and crew experience expectations. Second, the buyer base is shifting: beyond traditional cruise and merchant shipping needs, offshore energy, government/defence, and new leisure segments are adopting differentiated service mixes that prioritize low-latency, cybersecurity and lifecycle economics.
Green Methanol Fuel for Marine Market
Why 2026 is a strategic inflection point
-
Capital allocation timing: Several commercially significant satellite assets and terminals are entering service across 2025–2026 windows. Early 2026 procurement decisions will determine which fleets secure prioritized capacity, phased terminal upgrades, or multi-provider contracts — all with multiyear lock-in implications.
-
Operational modernization: Shipyards and fleet operators scheduling phased retrofits in 2026 must reconcile power, HVAC and antenna-mounting constraints for new flat-panel and bonded VSAT systems. Our report provides pragmatic engineering guidelines and TCO comparisons to avoid costly rework.
-
Regulatory and sovereignty risk: Spectrum policy updates and national digital-sovereignty assertions (notably ongoing FCC spectrum modernization and EU digital-network initiatives) change licensing risk and compliance obligations for multi-national fleets. Operators who revisit contractual language and contingency routing in 2026 will reduce exposure.
What the full report delivers — practical, executable content
-
Decision frameworks: Buyer-centric decision matrices that map mission profiles (e.g., high-availability merchant, latency-sensitive cruise ops, pole-to-pole government) to recommended service architectures and procurement levers.
-
Provider scorecards: Comparative vendor assessments across availability, latency, global reach, product roadmap risk, commercial flexibility and cybersecurity posture — allowing rapid shortlisting for RFPs.
-
TCO and migration models: Capex-vs-opex calculators that capture terminal amortization, airtime tiering, VSAT vs LEO hybridization, power/energy costs and expected bandwidth consumption curves by vessel class.
-
Scenario planning and stress tests: Three scenario paths (baseline growth, accelerated LEO densification, and regulatory-constrained fragmentation) with corresponding supplier, technical and commercial contingencies.
-
Deployment playbooks: Step-by-step templates covering on-board civil works, power provisioning, antenna siting, commissioning checklists, and integration with onboard IT and cyber defenses.
-
Regulatory matrix: A jurisdictional catalog of licensing, lawful interception, and safety-service requirements (including maritime distress systems) to support compliance planning for international voyages.
-
Case studies and suppliers’ war-gaming: Real-world fleet migration examples, supplier negotiation archetypes, and contract clause templates designed to preserve bandwidth flexibility and multi-provider redundancy.
Competitive landscape — strategic positions and tactical takeaways
The market is multi-layered: satellite network operators, terminal manufacturers, integrators and managed-service providers each play distinct roles. Our market concentration analysis shows that leading incumbents retain significant influence, but the supplier mix is shifting as LEO entrants and hybrid integrators gain traction. Below we summarize the strategic posture of the core players featured in the full report — a distillation of observed strategies, recent product developments, and commercial implications for buyers.
-
Viasat (Inmarsat Maritime) — Positioning: multi-orbit bonded connectivity and enterprise-grade VSAT. Strategic implication: Viasat’s NexusWave approach (now extended with new maritime terminals) targets customers that prioritize end-to-end managed services with bonded GEO/LEO throughput; attractive to operators needing predictable SLAs across high-traffic routes.
-
SpaceX Starlink Maritime — Positioning: low-latency LEO capacity with flat-panel maritime terminals and disruptive pricing models. Strategic implication: Starlink is a high-performance option for latency-sensitive operations and crew welfare use-cases, but operators must manage fleet-level regulatory and redundancy considerations.
-
Iridium Communications — Positioning: pole-to-pole narrowband and resilient safety services (including maritime distress systems). Strategic implication: Iridium remains the safety backbone for global distress, and hybrid solutions that combine Iridium safety services with broadband LEO/GEO data links are increasingly common.
-
Marlink — Positioning: managed hybrid networks integrating GEO and LEO services with a cybersecurity layer. Strategic implication: Marlink is appealing to customers seeking single-pane-of-glass management and extended professional services for fleet digitalization.
-
Speedcast — Positioning: global managed VSAT and integration for maritime and offshore. Strategic implication: Speedcast targets reliability-focused fleets and large tender operations where network optimization and operational continuity are priority requirements.
-
KVH Industries — Positioning: terminal OEM with integrated airtime offerings. Strategic implication: KVH remains a strong choice for standardized HTS VSAT installations where OEM-as-integrator simplifies procurement and lifecycle support.
-
Intelsat — Positioning: GEO/hybrid VSAT solutions with enterprise network services. Strategic implication: Intelsat’s heritage in wide-area maritime networking supports operators requiring predictable, scaled GEO capacity with hybrid augmentation.
-
Eutelsat Group (with OneWeb) — Positioning: GEO and MEO/LEO hybrid offerings via OneWeb. Strategic implication: Offers alternative multi-orbit resiliency that can reduce single-point supplier dependency, particularly for operators in regulated environments seeking EU-aligned providers.
-
Hughes Network Systems (EchoStar) — Positioning: enterprise-grade terminals and transportable LEO solutions. Strategic implication: New ruggedized LEO transportables enable rapid deployments and serve as contingency in mobilization scenarios, including offshore support and emergency response.
-
Intellian Technologies — Positioning: maritime antenna and terminal OEM. Strategic implication: As terminals and flat-panel systems proliferate, antenna OEMs shape installation complexity and power profiles — a key procurement criterion.
-
NSSLGlobal, Satcom Global, IEC Telecom, AST Networks — Positioning: specialized integrators and regional managed-service providers. Strategic implication: These providers are frequently chosen for regional expertise, bespoke contract structures, and close operational support on complex routes.
Recent vendor-level moves validate several of our report’s themes: network bonding and terminal refresh cycles (leading OEMs launching new maritime terminals), LEO terminal certification for mobile use-cases, and hybrid vendor selection patterns by fleet operators. For example, NexusWave terminal launches and ruggedized LEO transportables introduced in late 2025 reflect supplier readiness to compete on both capacity and deployability.
Operational constraints and regulatory reality
Three non-negotiable operational factors are central to any 2026 procurement or upgrade plan:
-
Power and ship-architecture impact: Modern maritime terminals (flat-panel phased array and bonded VSAT kits) have non-trivial power footprints and require dedicated siting and cooling considerations. Our deployment templates quantify expected power envelopes and mitigation options for retrofit scenarios.
-
Safety and backup obligations: The maritime distress and safety landscape (including established global distress services) mandates integrating narrowband safety services into any broadband strategy — an imperative for compliance and insurance risk management.
-
Spectrum, data sovereignty and lawful access: Evolving spectrum policy and national sovereignty measures change where and how traffic can be routed, and they affect contract clauses for lawful interception, taxation and service continuity.
How boards and procurement teams should act in 2026
-
Audit your connectivity stack now: Quantify current network performance, failure modes, and upgrade windows. Use our TCO model to test alternative procurement levers before issuing RFPs.
-
Design for hybrid resilience: Mandate multi-orbit and multi-provider architectures in new contracts; require clear failover SLAs and testable attendance procedures to avoid single-vendor dependencies.
-
Embed regulatory contingencies: Ensure contracts include clauses for spectrum and routing changes, and define procedures for lawful-interception compliance across jurisdictions.
-
Prioritize power and retrofit readiness: Factor terminal energy consumption and antenna siting into dry-docking schedules to minimize downtime and retrofit rework.
-
Lean on managed-service partners: For fleets without in-house satellite networking expertise, select integrators who offer end-to-end SLA-backed service with clear escalation matrices.
About the full PW Consulting study and next steps
The full Worldwide Marine Satellite Internet System Market report (base year 2025, forecast 2026–2032) contains the underlying data series, regional and application splits, vendor revenue estimates, contract-level case studies, and the procurement templates described above. The preview intentionally omits granular sub-segment tables and line-item regional breakdowns to preserve the value of the comprehensive dataset and analytical tooling included in the complete publication.
PW Consulting’s report is designed to be directly actionable for 2026 planning cycles: it combines independent market-sizing (including our 11.22% forecast CAGR), supplier benchmarking, TCO tools and regulatory playbooks so commercial leaders can move quickly from strategy to implementation without rework.
To access the full dataset, vendor scorecards, TCO calculators and deployment playbooks — and to schedule a briefing with our senior maritime connectivity analysts — please visit the PW Consulting report page.
PW Consulting — helping maritime leaders translate orbit-level change into board-level certainty.
For detailed analysis of this topic, please visit the official page: Worldwide Marine Satellite Internet System Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com