

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Worldwide Embedded Systems Market Reaches USD 126,500 Million in 2025, Set to Grow at 6.85% CAGR Through 2032

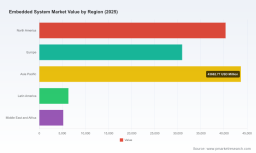
Worldwide Embedded System Market — 2026 Strategic Brief
PW Consulting's new market research, published as our 2026 Strategic Brief on the Worldwide Embedded System Market, synthesizes five years of historical performance and a seven-year outlook into a focused, decision-ready narrative for executives, product leaders, and procurement teams. This briefing highlights the macro trajectory — and the practical choices companies must make in 2026 — while reserving the detailed segment tables, vendor share matrices, and regional allocations for the full report download.
Worldwide Stainless Steel Retaining Ring Market
Executive summary
The embedded systems market has moved from recovery into an era of sustained expansion. Our analysis shows the addressable market growing from approximately USD 89,450 Million in 2020 to USD 126,500 Million in the base year 2025, and continuing along a compound annual growth rate of about 6.85% across the forecast window. By modelled scenarios, the market crosses important strategic thresholds in the late 2020s as edge AI, connected mobility, and industrial digitization materially redefine product requirements and supply chain priorities.
Worldwide CRM and Customer Experience Implementation Services Market
Two structural traits stand out: first, the market remains fragmented — the leading three vendors account for under one fifth of industry revenue and the top five hold less than a third — creating opportunity for specialization and scale plays. Second, growth is being driven by a convergence of software-defined capabilities with demand for long-life, certifiable hardware in safety-critical applications. These twin trends create strategic levers that can be exploited by product companies, silicon vendors, tier-1 integrators and investors alike.
Worldwide Cloud Management Tools Market
What the PW Consulting report delivers (practical contents)
- Forward-looking market sizing and scenario analysis: multiple demand scenarios to stress-test 2026–2032 investment plans.
- Go-to-market intelligence: purchaser personas and procurement cycles by end-market (detailed breakdowns available in full report).
- Supply-chain and cost modelling: actionable guidance to mitigate raw material and memory-price volatility, including hedging and inventory strategies.
- Security & compliance playbook: steps to meet emerging regulatory obligations, including SBOM governance and vulnerability management workflows.
- Technology adoption maps: migration pathways for legacy MCU platforms to edge-AI-capable SoCs, and vendor evaluation checklists for long-life availability and safety certifications.
- Vendor and ecosystem assessments: qualitative profiles and strategic positioning of major silicon and platform providers, plus a matrix of partnership fits for OEMs and system integrators.
- Practical templates: procurement RFP language, supplier audit checklists, SWaP-C (size, weight, power, cost) evaluation templates, and skills-gap hiring frameworks.
Note: consistent with our "teaser" approach, the public brief intentionally highlights strategic conclusions while reserving granular tables and proprietary modelling inputs — regional splits, application-level numeric breakdowns, and vendor market shares — for clients who access the full report.
Industry dynamics shaping 2026 decisions
- Regulatory acceleration: The EU Cyber Resilience Act (with a multi-year transition) elevates cybersecurity and SBOM obligations across hardware and software in the European market. Companies selling into or sourcing from the EU must embed secure-development lifecycles and vulnerability handling into product roadmaps now — delaying compliance will create market-access risk.
- Standards and engineering discipline: The 2026 updates to ISO/IEC/IEEE 12207 align systems/software engineering expectations with quality management practices. This strengthens the business case for investing in model-based systems engineering and toolchains that produce auditable development artefacts.
- Component supply pressures: Memory (LPDDR4X/LPDDR5X) and other commodity pressures remain material as semiconductor capacity is reallocated to high-demand AI workloads. Expect price and lead-time volatility into 2027; procurement teams must adopt multi-sourcing, early-buy, and design-flexibility strategies.
- Safety and functional compliance: ISO 26262, IEC 61508 and related sector standards continue to dictate product architecture and verification overhead in automotive and industrial categories — pushing companies toward proven platforms and certified stacks rather than bespoke, high-risk designs.
- Talent constraints & toolchain evolution: The finite pool of experienced embedded engineers is accelerating adoption of AI-assisted development, higher-level design frameworks, and pre-certified software stacks to shorten time-to-market while reducing headcount strain.
Competitive landscape — who matters and why
The embedded systems arena is populated by a mix of global silicon leaders, specialized microcontroller houses, and emergent AI-accelerator providers. Our qualitative assessment in the report highlights several strategic archetypes among the leading vendors:
- Platform consolidators : Firms with broad portfolios of processors, long-life availability commitments and established OEM relationships lead on total addressable reach. These vendors are the default partners for programs that require lifecycle guarantees and broad ecosystem support.
- Domain specialists : Semiconductor companies that focus on automotive or industrial-grade solutions compete on functional safety, in-vehicle networking, and secure element capabilities. Their advantage is deep domain know-how and certification pipelines.
- AI accelerators and edge compute innovators : GPU-accelerated and NPU-enabled platforms are reshaping what “embedded” can do at the edge. These players attract OEMs pursuing advanced perception, ADAS, and high-throughput inference in constrained thermal envelopes.
- Connectivity and analog strength : Vendors offering power management, analog front-ends and connectivity stacks remain indispensable to product integrators who must balance energy budgets and reliable data transport.
Representative vendors profiled in the research include, without limitation:
- Intel Corporation — long-life embedded processors, SoCs and edge-AI platforms tailored for industrial and automotive applications.
- Texas Instruments — deep analog and MCU portfolio with power-management leadership for embedded control systems.
- NXP Semiconductors — secure microcontrollers and connectivity solutions with a strong automotive and industrial footprint.
- STMicroelectronics — broad MCU family (including STM32), sensors and automotive-grade power solutions with an active ecosystem.
- Renesas Electronics — focused embedded SoCs and microcontrollers for automotive and infrastructure customers.
- Qualcomm — wireless chipset and edge-AI platforms for IoT and mobile-embedded use cases.
- Infineon, Microchip, Analog Devices, Samsung, Broadcom, NVIDIA, AMD — each included for their strategic roles in power semiconductors, analog/DSP, memory/display integration, networking, and GPU/NPU-enabled edge compute.
The report includes concise strategic profiles for each named company, assessing strengths, go-to-market motions, and partnership fit for OEMs. Recent market activity — from product launches at Embedded World to acquisitions that combine MCU SDKs with commercial Linux distributions — is also catalogued and assessed for disruption potential.
Strategic implications and recommended actions for 2026
Across the executive agenda, we recommend five priority actions:
- Embed regulatory compliance into product roadmaps: Treat the Cyber Resilience Act and updated engineering standards as gating criteria for new product launches. Allocate resources to SBOM tooling, secure-SDLC training, and third-party vulnerability triage.
- Operationalize component risk management: Implement dynamic bill-of-materials (BOM) risk scoring, lock critical memory buys for core programs, and qualify alternative silicon paths early in development to avoid late-stage redesigns.
- Prioritize platform re-use and certified stacks: Choose platforms with established safety- and security-certification trajectories to shorten verification cycles and reduce total cost of compliance for safety-critical markets.
- Adopt hybrid talent strategies: Combine targeted hiring with AI-assisted development tools and partner with specialist integrators to bridge embedded-systems skill gaps without ballooning headcount costs.
- Design for modularity and upgradeability: Architect systems that allow field-level software upgrades, secure boot chains, and modular edge-AI accelerators so product lifecycles can be extended while preserving certification baselines.
Why this brief matters — and what you’ll find in the full PW Consulting report
For 2026 planning cycles, the core strategic questions are no longer about if embedded systems will adopt AI and connectivity — they already have — but about how to make that transition profitable, compliant, and resilient. PW Consulting’s full report provides the granular decision support teams need: downloadable scenario models, supplier scorecards, application-level adoption curves, and a detailed vendor-share appendix.
We intentionally publish this strategic brief to surface the high-impact insights while preserving the bespoke analytical assets that underpin procurement negotiations, M&A diligence, and platform selection. If your 2026 plan hinges on embedded systems outcomes — whether you are an OEM, a silicon vendor, a systems integrator, or an investor — the full report will materially shorten your path from strategy to executable programs.
Next steps
- For immediate guidance, request PW Consulting's executive summary and procurement playbooks to align your 2026 roadmap with our scenarios.
- Schedule a tailored briefing with our embedded systems practice to walk through vendor fit-for-purpose assessments and cost-impact modelling.
- Access the full report to obtain proprietary tables, regional & application breakdowns, vendor market shares, and downloadable forecasting models.
PW Consulting stands ready to help you convert the embedded systems market’s complexity into a competitive advantage. Contact our advisory team to arrange a briefing and obtain the full Worldwide Embedded System Market report.
For detailed analysis of this topic, please visit the official page: Worldwide Embedded System Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com