

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Worldwide Microbial Fuel Cell Market Set to Reach USD 37.23 Million by 2032

Worldwide Microbial Fuel Cell Market — Strategic Preview for 2026 Decisions
As companies recalibrate energy and wastewater strategies for the post-pandemic decarbonization era, microbial fuel cells (MFCs) have moved from niche research curiosities to pragmatic options in select industrial and municipal contexts. PW Consulting’s forthcoming Worldwide Microbial Fuel Cell Market report (base year 2025) synthesizes five years of historical data and provides a rigorous forecast through 2032. At a compound annual growth rate of approximately 11.25% over the forecast window, the global market more than doubles in size from the 2025 baseline—clear evidence that the technology is entering a commercialization phase that demands executive attention in 2026.
Wireless HART Gateways Market
Why 2026 Is a Pivotal Year for Corporate Strategy
Several converging forces make 2026 a decision point for industrial water managers, utility strategists, technology investors and equipment OEMs:
Worldwide Mobile Service Integrator Market
- Technology readiness is improving: continuous-flow reactor benchmarks and modular products have moved performance and deployment risk from pure R&D to structured pilot and early commercial projects.
- Regulatory pressure and sustainability commitments are sharpening: jurisdictions that mandate energy-efficient wastewater treatment are creating a window for pilot-to-scale transitions.
- Supply-chain and cost dynamics are crystallizing around a small set of critical materials—primarily electrode substrates—making procurement strategies and supplier partnerships strategic priorities.
For decision-makers who must allocate capital for 2026 projects, the key question is not whether MFCs are interesting, but where and how to deploy them to capture early revenue, de-risk scale-up and build intellectual and service-based differentiation.
Worldwide Anti-Odor Agent Market
What the PW Consulting Report Delivers (Practical, Decision-Ready)
The report is structured around actionable modules designed to support board-level and operational decisions, and includes:
- Transparent market model and financial templates: integrated topline and unit economics models that let users stress-test scenarios across technology variants, feedstocks and plant scales.
- Scenario-driven forecasts (2026–2032): base, upside and constrained cases aligned with policy trajectories, capital availability and material cost curves.
- Go-to-market playbooks: channel strategies for water utilities, industrial OEMs and service providers, including partnership archetypes and contracting models.
- Technology and performance benchmarking: power-density and COD-removal baselines for continuous-flow reactors and modular units, with clear criteria for vendor selection.
- Supply-chain and cost-mapping: a bill-of-materials approach that highlights critical cost levers and procurement strategies to protect margins during scale-up.
- Competitive intelligence: in-depth company profiles, capability matrices and strategic moves for the active commercial players in the space.
- Implementation checklists and KPI templates: practical metrics for pilot acceptance, O&M regimes and lifecycle costing to guide procurement and performance-based contracting.
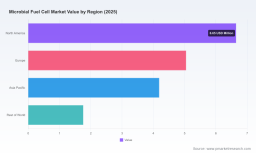
Notice: the report purposefully reserves granular regional and application-level splits and full company financials for the subscriber edition—this preview is designed to surface strategic insight while inviting deeper analysis via the full deliverable.
Market Dynamics and Policy Context
MFC adoption is being driven by three structural dynamics:
- Energy recovery economics. In plants treating high-strength industrial wastewater, MFCs can convert biochemical energy into usable electricity and reduce overall treatment energy intensity—an increasingly compelling proposition as utilities adopt circular economy targets.
- Technology performance improvements. Recent benchmarking shows advanced MFC configurations achieving meaningful power densities in continuous-flow wastewater reactors (up to benchmark levels observed in public-sector tests), enabling longer duty cycles and more predictable outputs (U.S. Department of Energy, Bioenergy Technologies Office Report, June 2023).
- Regulatory tailwinds. Energy-efficiency mandates for urban wastewater treatment in major jurisdictions are raising compliance costs for legacy technologies and opening procurement pathways for lower-energy secondary treatment alternatives (European Commission directives and analogous national regulations).
That said, two pragmatic constraints temper optimism. First, electrode substrates and assembly quality remain cost levers—carbon fabric materials command a premium on a per-area basis, and their pricing variability influences unit economics and rollout cadence (for example, commercial listings for carbon cloth electrodes indicate a mid-range price band that must be factored into procurement models). Second, operational realities such as electrode fouling and biofouling control currently limit many systems to pilot-scale, sub-kilowatt deployments in routine practice; eliminating these barriers is a core focus of near-term R&D and O&M innovation (industry market assessments, 2024).
Competitive Landscape — Strategic Profiles of Active Players
The emerging commercial ecosystem is a mix of specialist cleantech companies and established water-tech integrators. PW Consulting’s analysis highlights distinct strategic postures among the most active names:
- Aquacycl Ltd. (Didcot, UK) — Specializes in bioelectrochemical reactors targeted at high-strength industrial effluents. Strengths: reactor engineering, energy-recovery focus, and integration pathways with anaerobic and aerobic treatment trains. Strategic implication: attractive partner for licensors or industrial decarbonization pilots.
- Plant-e B.V. (Wageningen, Netherlands) — Commercializing plant-integrated MFC systems that harvest electricity from root-zone organics. Strengths: unique IP in plant-microbial interfaces and low-footprint installations for urban green infrastructure. Strategic implication: niche urban and rooftop deployments; partnership opportunities with landscape architects and smart-city integrators.
- Microbenergy S.L. (Valladolid, Spain) — Markets modular BEE-BOX® units aimed at decentralized wastewater and off-grid power. Strengths: modularity, ease of deployment and clear retrofit propositions. Strategic implication: productization model suited to remote or distributed industrial sites and disaster-relief deployments.
- Nijhuis Saur Industries (Doetinchem, Netherlands) — Integrator offering membrane-free bioelectrochemical systems for COD removal and energy production. Strengths: established scale-up capability in water treatment engineering and client relationships with utilities. Strategic implication: potential channel for rapid commercial uptake through turnkey projects.
Collectively, the competitive field shows early specialization rather than commoditization: companies are differentiating by target feedstock, system architecture and service models. Market concentration remains moderate; opportunity exists for M&A and strategic partnerships that combine technology IP with distribution scale.
Strategic Imperatives for 2026
For executives planning capex, procurement or investment allocations in 2026, PW Consulting recommends a focused set of actions:
- Prioritize pilots where economics are demonstrably favorable—high-strength, consistent feedstocks and sites with on-site energy needs reduce integration complexity and accelerate payback.
- Secure supply-chain optionality for electrode materials and bipolar plates. Given price sensitivity in the BOM, early volume purchasing agreements or joint-development contracts with suppliers can protect margins and timelines.
- Invest in fouling-mitigation and maintenance protocols as a product feature—operations cost and uptime will determine total cost of ownership more than peak power metrics alone.
- Design commercial offers around performance guarantees and service subscriptions rather than pure capex sales; utilities prefer predictable O&M and verifiable compliance with energy and effluent metrics.
- Develop cross-sector partnerships—pair MFC solutions with anaerobic digestion, photovoltaic arrays or resource-recovery modules to create bundled value propositions that are compelling to procurement committees.
Key Questions Executives Should Put to Vendors and Pilot Teams
As part of vendor selection and pilot scoping, executives should insist on clear answers to the following:
- What are the steady-state power-density and COD-removal metrics in continuous-flow operation, and over what timeframe were they validated? (Use independent third-party validation where possible.)
- How do you manage electrode fouling and what is the expected maintenance cadence and cost profile during year 1–5?
- What supplier agreements exist for critical electrodes and membranes, and how much price and delivery risk is transferred to the customer?
- Can the system be integrated into existing control and SCADA platforms, and what cybersecurity provisions are included for remote monitoring?
- What contractual structures do you offer—performance contracts, energy-sharing arrangements, or traditional equipment sale—and how are risks apportioned?
Note: many MFC deployments in the market today remain at pilot-scale, with routine commercial installations still emerging. PW Consulting’s report documents current deployment ceilings and provides frameworks to evaluate readiness for scale in specific use cases.
How PW Consulting Supports Implementers in 2026
Our advisory work combines the market model and technical diligence to shorten the path from pilot to profitable deployment. Typical engagements include:
- Vendor selection and RFP design incorporating technical KPIs, lifecycle costing and service-level obligations.
- Financial modelling for hybrid projects that stack MFC output with other renewable assets and waste-to-energy streams.
- Procurement strategy for electrode and core-component sourcing, including supplier qualification and bundled procurement options.
- Pilot design and commercialization roadmaps that translate lab metrics into operationally realistic performance targets.
Next Steps and Where to Access the Full Analysis
This briefing intentionally highlights strategic takeaways and the operational questions that should drive 2026 decisions without disclosing the granular regional and application splits, company-level financials and the full set of sensitivity tables contained in the subscriber edition. PW Consulting’s full Worldwide Microbial Fuel Cell Market report includes detailed regional and application forecasting, downloadable spreadsheet models, extended vendor due-diligence appendices and customer-case studies that map directly to procurement, engineering and investment workstreams.
To obtain the full report and model pack, or to commission a tailored advisory project focused on MFC commercialization, contact PW Consulting. Our team will help you translate market momentum into executable 12–36 month strategies that balance risk, cost and impact.
For detailed analysis of this topic, please visit the official page: Worldwide Microbial Fuel Cell Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com