

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Worldwide Elapegademase-lvlr Drugs Market Poised to Grow at 8.5% CAGR During 2026–2032

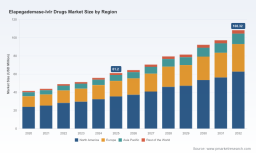
PW Consulting Releases Strategic Brief: Worldwide Elapegademase-lvlr Drugs Market — A Decision-Grade Roadmap for 2026
PW Consulting today publishes a strategic industry briefing accompanying our full report, Worldwide Elapegademase-lvlr Drugs Market. Built for executive teams, corporate strategy groups, and investors, this briefing translates our proprietary market model into the immediate actions that matter for 2026. It spotlights why elapegademase-lvlr (Revcovi) remains a high-priority asset in rare-disease portfolios, and how commercial, clinical, regulatory, and manufacturing vectors will determine value creation as the market transitions beyond orphan exclusivity.
Inverter Systems Market
Why this market matters in 2026
-
Compelling growth trajectory: Our consolidated model shows the global elapegademase-lvlr market expanding materially from a 2020 baseline, reaching an estimated USD 61.2 Million in our base year (2025) and continuing to grow into the forecast window. By 2032 the market is projected to exceed USD 108 Million — a multi-year expansion consistent with an 8.5% compound annual growth rate across the 2026–2032 forecast window.
Electronically Controlled Food Dehydrator Market -
Post-exclusivity inflection: Revcovi’s regulatory exclusivity dynamics create a clear strategic inflection in late 2025 and into 2026, shifting the competitive and reimbursement landscapes and elevating the importance of supply-chain resilience, pricing discipline, and payer engagement.
TWS Headphone SoC Market -
High concentration, singular incumbent: The market remains highly concentrated around the incumbent manufacturer. Our concentration metrics underline a near-monopoly structure today — an important contextual factor for any entrant, partner or investor considering exposure to this therapy segment.
Market dynamics you can’t ignore
-
Supply chain fragility: We documented episodes of manufacturing delay and product shortage that materially affected availability. These interruptions drove rapid operational responses from the incumbent and payers, and created measurable short-term patient-access constraints. For any commercial strategy in 2026, contingency manufacturing capacity and secondary sourcing are not optional.
-
Regulatory timing and exclusivity cliffs: The orphan-drug exclusivity window governing current market access has been a central driver of commercial dynamics. As exclusivity considerations ease, stakeholders should expect accelerated interest from both biosimilar and alternate-approach developers; 2026 is the year to model multiple competitive-entry timelines and price-pressure scenarios.
-
Reimbursement and treatment economics: The therapy’s positioning within orphan-drug reimbursement pathways has enabled stable uptake for the indicated patient groups. However, as volume grows and new entrants potentially appear, payers will revisit value propositions and may impose tighter coverage guardrails, particularly in high-cost acute administration settings.
-
Safety and label constraints: The product profile includes specific contraindications that shape patient eligibility and pathway fragmentation. These clinical boundaries must be embedded into patient-access models and channel design.
What our report contains — and why it matters
-
Robust financial model: A full-year historical series and a multi-scenario forecast (2026–2032) that combine top-down market drivers with bottom-up treatment adoption assumptions. The model is scenario-enabled so teams can stress-test outcomes against pricing moves, supply shocks, or accelerated competitor entry.
-
Commercial playbooks: Actionable channel and distribution strategies tailored to hospital and specialty pharmacy settings, including patient-support program design, payer negotiation frameworks, and ED/infusion-site optimization templates.
-
Regulatory and policy tracker: A timeline of exclusivity, approval pathways, and reimbursement levers — together with stakeholder maps and talking points for engagement with regulators and national payers in prioritized jurisdictions.
-
Supply-chain and manufacturing risk assessment: Heatmaps, mitigation options, and an investment matrix for onshore vs. offshore capacity, second-source strategies, and fill/finish contingencies informed by recent shortage events.
-
Due-diligence and M&A toolkit: Valuation frameworks, synergy-checklists, and commercial integration playbooks to support inorganic strategies — whether pursuing bolt-on manufacturing, capability acquisition, or licensing partnerships.
-
Primary research intelligence: Confidential interviews with treating physicians, hospital pharmacy directors, and payer medical directors that reveal real-world constraints and adoption drivers not visible in public filings.
Competitive landscape — focal notes for 2026
-
Incumbent leadership: The market is currently led by the originator organization, whose global commercialization of the PEGylated recombinant enzyme underpinning Revcovi remains the dominant revenue source. Our analysis assesses their strategic levers — lifecycle management, supply augmentation, and payer contracting — and where their capabilities create barriers to entry.
-
Entry dynamics: The combination of orphan labeling, concentrated manufacturing know-how, and limited eligible patient populations raises the cost and complexity for new entrants. Still, the post-exclusivity window creates a defined horizon for competitive threat modelling — a window in which strategic entrants, contract manufacturers, or biosimilar developers may accelerate activity.
-
Recent operational signals: Publicly available regulatory and supply datasets show discrete instances of product shortage and subsequent resupply over 2022–2023. These events have real economic implications for hospitals, specialty pharmacies, and payers — and they elevate the strategic value of contingency plans and inventory strategies in 2026.
How to use the report for 2026 decision-making
-
Build adaptive financial plans: Use our scenario-ready revenue model to create short, medium and long cases — explicitly modelling exclusivity sunset, price compression, and conversion rates from alternative therapies. This enables capital allocation decisions that are robust to downside supply and pricing shocks.
-
Prioritize supply resilience investments: Allocate capex and contract capacity to reduce single-point-of-failure risks. Our mitigation ladder ranks interventions by cost, lead time and effectiveness, helping procurement and operations teams sequence investments in 2026.
-
Accelerate payer engagement: Engage national and regional payers with real-world evidence packages and cost-offset analyses early in 2026. Our payer playbooks include concrete message maps and evidence tiers that materially improve coverage outcomes in rare-disease contexts.
-
Design patient-centric distribution: Re-evaluate channel mixes for hospital infusion versus specialty pharmacy fulfillment to optimize adherence, reduce administration burden, and protect revenue in constrained supply scenarios.
-
Prepare for competitive entry: Maintain an intelligence program that tracks both biosimilar pipelines and alternative modality programs targeting the same indication. Our competitive-alert framework flags triggers that should move a board to action — e.g., a manufacturing partnership announcement or a pivotal trial readout.
Recommended 90‑day sprint for leadership teams
-
Week 1–4: Run the report’s “stress-test” scenario. Recalibrate revenue, cash-flow, and pricing models under three defined competitive and supply scenarios.
-
Week 5–8: Convene a cross-functional supply resilience workshop using our heatmap templates; prioritize quick wins that close highest-probability failure modes.
-
Week 9–12: Deploy an accelerated payer evidence package to top accounts and begin negotiations for updated reimbursement terms tied to outcomes or access metrics.
Limitations and the PW Consulting advantage
-
What we disclose here is intentionally high-level. The goal of this briefing is to present the strategic contours and compel operational follow-through. We have deliberately withheld granular segmentation figures and jurisdictional percentages to preserve the commercial value of the full report and its underlying models.
-
What we provide in the full deliverable is different: the complete dataset (historical and forecast by year), proprietary patient-penetration assumptions, channel mix sensitivity, a named-stakeholder contact map for prioritized markets, and executable templates. These assets transform the strategic insights above into board-level decisions and operational plans for 2026.
Final word — why act now
The market’s growth fundamentals are clear: a sustained expansion driven by established clinical demand and a therapy profile that has secured durable reimbursement pathways. Yet, 2026 marks a pivot — the moment when exclusivity dynamics, manufacturing constraints, and payer scrutiny converge to create both risk and opportunity. Executives who combine early supply resilience investments, disciplined pricing strategies, and targeted payer engagement will preserve market share and unlock upside in the medium term.
PW Consulting’s Worldwide Elapegademase-lvlr Drugs Market report is designed to be the operational playbook that turns these insights into prioritized actions. For teams planning 2026 budgets, manufacturing scopes, or M&A activity, the full report contains the decision-grade models and tactical blueprints necessary to execute with confidence.
For detailed analysis of this topic, please visit the official page: Worldwide Elapegademase-lvlr Drugs Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com