

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Tris (Clorisopropyl) Phosphate Market Set to Expand at 4.82% CAGR to 2032, 2025-Based Report Reveals

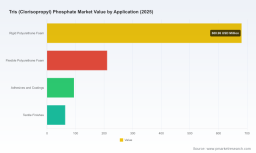
Tris (Clorisopropyl) Phosphate (TCPP) Market: Strategic Imperatives for 2026 — Preview of PW Consulting’s Definitive Industry Report
As companies prepare budgets and strategic roadmaps for 2026, the Tris (Clorisopropyl) Phosphate (TCPP) market deserves elevated attention. PW Consulting’s forthcoming market research report (base year 2025, historical coverage 2020–2025, forecast period 2026–2032) synthesizes macro supply-demand dynamics, regulatory trajectories, and competitive moves to deliver practical guidance for procurement, product strategy, and M&A decision‑making. This briefing highlights the report’s high‑value takeaways and explains how our analysis supports confident actions in 2026 — while reserving the granular, segment‑level data and proprietary models for authorized report access.
Carrier-Free Masterbatch Market
Why TCPP matters to corporate strategy in 2026
-
Durable growth backdrop. The global TCPP market has shown steady expansion through the last five years and, under our baseline scenario, is projected to continue growing at a mid-single‑digit pace (modeled CAGR 4.82% for 2026–2032). Our top‑level sizing places the market at USD 1,050 Million in 2025 and anticipates progressive growth toward our 2032 projection in the report.
Wind Power Lightning Protection System Market -
Structural exposure to feedstock economics. Production economics are concentrated in a few feedstocks — notably propylene oxide, phosphorus oxychloride and chlorine — which account for the majority of manufacturing cost. Volatility or supply constraints in these inputs translate rapidly into tightness across the TCPP value chain and have direct implications for contract negotiation, hedging and local sourcing decisions.
Pesticide Grade 1,2,4-Triazole Market -
Regulation and trade are reshaping sourcing logic. TCPP is under heightened regulatory scrutiny in major jurisdictions; REACH registrants have publicly self‑classified TCPP as Carcinogen Category 2, and trade measures (including U.S. tariffs and trade remedy findings) have introduced material import risk and cost differentials. These developments are accelerating the move toward qualification of alternative suppliers and greater onshore capacity planning in key end‑use geographies.
What this report delivers — practical content for immediate use
-
Robust market sizing and scenario forecasts: a verified topline series (2020–2025) and three forward scenarios (baseline, downside regulatory shock, and accelerated substitution) through 2032, rooted in our proprietary demand drivers and input‑cost models.
-
Value chain and cost‑build analysis: stepwise margin modeling that quantifies feedstock exposure and identifies the levers available to downstream formulators and foam manufacturers to stabilize cost of goods sold.
-
Regulatory playbooks and compliance pathways: actionable templates for REACH/TSCA documentation, timelines for likely restriction events, and decision matrices for compliance investment vs. supply diversification.
-
Supplier matrix and commercial diligence tools: an evaluated universe of producers, specialty houses and distributors with supplier risk scores, capability maps (grade, formulation support, certifications), and negotiation checklists adapted to the current tariff and trade remedy landscape.
-
Go‑to‑market and product prioritization guides: segment‑level opportunity mapping (rigid vs. flexible foam and polymer formulations), EV battery enclosure foam use cases, and commercialization sequences that protect margin while meeting fast‑evolving spec and safety requirements.
-
M&A and partnerships heatmap: targets by strategic rationale (capacity, technology, distribution) together with valuation sensitivity to regulatory and tariff scenarios — useful for private equity and corporates evaluating consolidation or regional entry.
-
Procurement playbook for 2026: tender timing, clause templates for tariff and antidumping pass‑through, and recommended inventory and safety stock bands under different supply disruption intensities.
Competitive landscape — what leading players are doing and why it matters
The market is composed of global specialty chemical groups, regional producers, and a network of distributors and trading houses. Market concentration is meaningful but not dominant — the top three producers do not fully control the sector, and the top five account for a clear but incomplete majority of commercial share. This structure creates both competitive tensions and openings for agile entrants.
-
Integrated global leaders: Companies with vertically integrated phosphorus or halogen feedstocks and broad flame‑retardant portfolios are prioritizing higher‑value applications and formulation packages. Their strategic playbook is to protect margin via value‑added formulation, compliance investments, and targeted product lines (for example, flame retardant packages tailored for EV battery enclosure foams).
-
Specialty additives and co‑development partners: System houses and specialty producers emphasize co‑development with foam makers, offering customized packages and regulatory support. These companies convert product credibility into longer commercial lifecycles and higher switching costs for customers.
-
Large regional capacity and price players: Several manufacturers in Asia supply broad grade ranges and compete on scale and cost. They are important for volume markets but face increasing friction from trade measures and customer requirements for documentation and compliance.
-
Distributors and traders: Global and regional distributors perform the critical role of bridging quality assurance, logistics and small‑lot supply — particularly important in markets where tariffs or antidumping duties amplify the value of a compliant, documented supply chain.
Recent industry activity sharpens these strategic themes: new product launches for EV‑specific foam formulations, partnership expansions to shore up transatlantic and transpacific supply, and entrants marketing high‑compliance grades targeted at North American and European buyers. These moves validate our assessment that product differentiation and regulatory readiness will determine commercial winners in 2026.
Regulation, trade and risk — the unavoidable constraints
-
Regulatory reclassification has real commercial consequences. The industry is already adapting to elevated classification under REACH frameworks, and this is increasing the cost and time to market for suppliers that lack robust compliance documentation.
-
Trade remedies and tariffs have altered landed economics. Import duties and affirmative trade determinations in major markets materially change supplier competitiveness and are pushing buyers to re‑evaluate total landed cost rather than invoice price alone.
-
Substitution risk. Parallel regulatory action on related phosphate esters has heightened interest in alternatives, forcing producers to accelerate innovation in both formulation and non‑halogenated solutions. We model substitution risk explicitly in our downside scenarios.
Actionable recommendations for 2026 decision‑makers
-
Prioritize supplier qualification and documentation. Mandate REACH/TSCA dossier review and certificate libraries from all Tier‑1 suppliers; make compliance a gating item in RFPs rather than a checkbox for awarded vendors.
-
Design dual‑track sourcing strategies. Combine a quality‑focused long‑term partner with regional, cost‑flexible suppliers for spot coverage. Where tariff exposure is material, plan for local or near‑market production partnerships.
-
Lock feedstock exposure through layered hedging and strategic contracts. Given the share of feedstock in production cost, buyers should require transparency on feedstock sourcing and integrate feedstock pass‑through protections into contracts.
-
Invest selectively in product differentiation. For foam formulators, secure partnerships with suppliers offering EV‑grade packages and system integration support; for chemical producers, invest in higher‑purity grades and documented compliance to expand into automotive and electronics applications.
-
Use regulatory events as negotiation leverage. Anticipated restrictions create windows where compliant suppliers can capture share at premium prices. Buyers should time procurement and contracts to these windows to avoid forced emergency purchases at elevated prices.
-
Prepare an M&A playbook that prices regulatory downside. In valuation work, stress‑test targets for scenario outcomes including trade remedy persistence and possible restrictions under REACH/TSCA.
How PW Consulting’s models turn insight into decisions
Our report provides the quantitative scaffolding behind the recommendations above: a consolidated topline series from 2020 through 2025, forward projections to 2032 under multiple scenarios (baseline CAGR 4.82%), and an integrated set of tools for procurement stress‑testing, supplier risk scoring, and deal valuation. We blend microeconomic cost‑builds with macro trade and regulatory scenarios to deliver clear, auditable outputs that procurement, business unit leaders, and M&A teams can act on immediately.
Next steps — using this intelligence in 2026
-
For procurement teams: request the supplier matrix and procurement playbook to redesign 2026 tenders.
-
For product and innovation leaders: access the formulation and application opportunity maps to prioritize development pipelines.
-
For corporate development and finance: use our M&A heatmap and valuation stress tests to fingerprint high‑value targets and set bid ranges.
PW Consulting’s full Tris (Clorisopropyl) Phosphate Market report contains the complete dataset, granular segmentation, supplier scorecards, pricing models and scenario outputs necessary to operationalize the guidance summarized here. This release is intended as a decision‑grade preview: we demonstrate the analytical rigor and actionable orientation you will receive, while preserving our proprietary granularity for subscribers and clients. To obtain the full report and the model files (USD, revenue unit: Million), or to commission a tailored workshop to apply the findings directly to your 2026 plans, please visit our report page or contact PW Consulting.
For detailed analysis of this topic, please visit the official page: Tris (Clorisopropyl) Phosphate Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com