

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Packaging Outserts & Inserts Market to Grow from USD 4,624.9 Million in 2025 to USD 6,954.1 Million by 2032 at a 6.0% CAGR

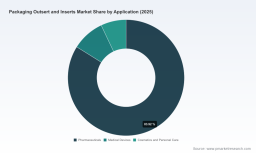
Packaging Outsert and Inserts Market — Strategic Preview for 2026: Key Imperatives from PW Consulting’s New Study
PW Consulting’s latest market intelligence brief — the Packaging Outsert and Inserts Market report (base year 2025) — synthesizes five-year historical performance and a forward-looking forecast to 2032, delivering a concise strategic playbook for business leaders navigating the supplier, innovation, regulatory, and cost pressures that will define 2026. The market demonstrated sustained expansion through 2020–2025, reached an estimated USD 4,624.9 Million in 2025, and is projected to continue its upward trajectory in 2026 and beyond, underpinned by a modeled mid-single-digit compound annual growth rate (CAGR) of 6.0% over the forecast horizon.
Smart Community Solutions Market
Why this report matters to decision-makers in 2026
- Actionable market context: The study converts aggregate growth and demand signals into priority actions—capacity planning, supplier selection, and product roadmaps—so procurement, packaging engineering, and regulatory affairs teams can align tactical moves to a predictable market cadence.
- Regulatory inflection points: With major EPR (Extended Producer Responsibility) regimes expanding in the U.S. and the EU’s Packaging and Packaging Waste Regulation coming into effect, packaging owners must reconcile compliance timelines with sourcing and design changes. Our report ties regulatory milestones to incremental cost and supply interventions.
- Cost and input-risk visibility: Paperboard and pulp cost volatility has a measurable impact on unit economics for outserts and inserts. The brief models sensitivity scenarios so teams can stress-test supplier contracts, hedging options, and design-for-cost trade-offs.
- Competitive benchmarking: We distill vendor capabilities into decision-oriented diagnostics that support make-or-buy, nearshoring, and supplier consolidation choices in markets where the top-tier suppliers account for a relatively small share of total industry sales.
Report scope and practical deliverables
This study is designed as an operational resource, not just a high-level overview. Key practical inclusions are:
Frozen Fruit Bar Market
- A validated topline market model (historical 2020–2025 and forecast 2026–2032) that quantifies demand growth under alternate macro-economic and regulatory scenarios, including sensitivity to material cost swings and regulatory compliance costs.
- Scenario-based cost models that let users populate their own input assumptions (paperboard, pulp, digital printing premiums, automation CAPEX and labor shifts) to calculate unit cost and margin impact across different production strategies.
- Supply-chain heatmaps and risk matrices showing where capacity constraints, raw-material exposure, and regulatory-driven redesign risk are most likely to appear—presented as decision triggers for sourcing and capital allocation.
- A vendor capability framework and scorecard templates for evaluating suppliers on regulatory compliance (cGMP/ISO), print quality, fold and conversion technology, digital printing readiness, and scale economics.
- Implementation-ready playbooks: procurement negotiation checklists, sample KPI dashboards for packaging operations, and a phased sustainability roadmap to meet emerging EPR and recycled-content obligations.
Market structure and competitive dynamics
The outsert and inserts sector remains fragmented: our concentration analysis shows that the three largest suppliers capture under 20% of market revenues, while the top five remain below one-quarter of industry sales—an important strategic signal. Low concentration implies of-the-moment opportunities for consolidation, targeted vertical integration by strategic buyers, and differentiated service offerings by tier-two and regional specialists.
Food Grade Softening Resin Market
Leading suppliers illustrate divergent strategic plays:
- Winpak (Norwood, NJ; https://www.winpak.com) — leverages precision conversion and pharmaceutical-grade compliance to deliver MedGuides, IFUs and large-format-to-compact conversions suited for automated application on bottles and cartons. Their recent product introductions point to continued productization of high-precision inserts.
- CCL Healthcare (Etobicoke, ON; https://cclhealthcare.com) — positions itself on customization scale and regulatory multilingual capabilities, producing extensive panel counts and long-form booklets under cGMP and ISO environments to serve multinational pharma needs.
- Nosco (USA; https://www.nosco.com) — emphasizes advanced folding and stitched booklets, targeting regulatory consistency and repeatability across high-panel-count applications for pharma and CPG clients.
- Colbert Packaging (Kenosha, WI; https://colbertpkg.com) — combines custom carton manufacturing with high-capacity micro-folding systems; a recent capacity expansion (new blanking die cutter, March 2026) underlines expectations for renewed demand in paperboard-based solutions.
- Graphic Packaging International (global; https://www.graphicpkg.com) — integrates leaflet and carton design with targeted paper grades for mandatory safety literature, competing on system-level solutions that reduce secondary packaging complexity.
- Faller Packaging (Waldkirch, Germany; https://www.faller-packaging.com) — focusing on pharma system supply in Europe and digital printing adoption (notably digital leaflet printing expansions in 2025) to shorten lead-times and support variable content needs.
- RLG Healthcare, Tursso, Flottman and others — occupy specialized niches (high-panel patient leaflets, IFUs for devices, miniature precision inserts) and form a resilient middle market that supplies technically demanding pharma applications.
These competitive archetypes—scale/system suppliers, precision/regulatory specialists, and digitally-enabled short-run providers—map directly to client strategies in our report: whether the right move is to partner, co-develop, insource, or acquire.
Key dynamics shaping 2026 planning
- Raw-material volatility: Recent data points show month-to-month movements in packaging-related producer price indices and persistent sensitivity in wood-pulp markets. For example, U.S. producer price indices for folding paperboard boxes and related packaging components have displayed near-term moderation, while global wood-pulp import/export spreads remain material for producers that do not hedge or pass costs to customers. The report contains templates to translate index moves into unit-cost deltas for contract negotiations.
- Regulatory acceleration: A wave of Extended Producer Responsibility laws across multiple U.S. states and the EU’s PPWR (effective August 2026) shift lifecycle costs onto producers and demand upstream redesigns—especially for mixed-material and non-recyclable laminates. Our regulatory-impact module brings these obligations into 3-year CAPEX and sourcing plans.
- Digital and automation inflection: Investments in variable-content digital printing, inline folding/gluing, and automation for in-line application are changing the economics for short-run, multi-language, and serialized literature—enabling new just-in-time strategies for patient materials and promotional leaflets.
- Fragmented supply base, targeted consolidation: Low top-tier share creates acquisition and partnership windows for organizations seeking to secure capability gaps (micro-folding, high-panel count production, regulatory printing) and to build geographic resiliency.
Practical recommendations for 2026
For executive teams seeking concrete next steps, the study prioritizes a short list of actions with measurable outcomes:
- 0–12 months — Execute supplier stress tests using our cost-sensitivity templates; secure short-term price collars or indexed contracts for paperboard/pulp exposure; launch a supplier capability audit focused on digital printing and serialization readiness; evaluate immediate OEM partnerships to manage EPR administrative compliance.
- 12–36 months — Invest in selective automation and digital print capacity (own or partner) to reduce lead-times and enable personalization; pursue targeted M&A or JV opportunities to acquire specialized folding or high-panel-count capabilities; implement circular-design pilots aligned to foreseeable recycled-content mandates and EPR reporting requirements.
- Commercial and regulatory — Rework SLAs and quality gates to include cGMP/ISO evidence, digital file management workflows, and change-control processes that reduce recall risk and rework on regulated pharmaceutical literature.
What we deliberately leave for the full report
This release is intended as a strategic preview. To preserve the value of our proprietary segmentation and supplier-scorecard outputs — which include granular regional and application-level demand allocations, detailed supplier cost benchmarking, and payback schedules — readers are directed to the full report. Those datasets power the tactical models and vendor-selection tools that teams will use to operationalize the recommendations above.
Next steps and how to access the study
PW Consulting’s Packaging Outsert and Inserts Market report combines empirical market modeling with practical implementation tools for procurement, packaging engineering, regulatory and sustainability teams preparing for 2026. For access to the full dataset, vendor scorecards, and scenario worksheets that underpin the recommendations summarized here, please visit our report page or contact our research team for a tailored briefing.
About PW Consulting: We advise Fortune 1000 and mid-market clients on packaging, supply-chain resilience, and regulatory strategy. Our market studies are built to translate industry dynamics into executable plans and measurable KPIs.
For detailed analysis of this topic, please visit the official page: Packaging Outsert and Inserts Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com