

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting Forecast: Worldwide SPECT Camera Market to Expand at a 6.02% CAGR Through 2032

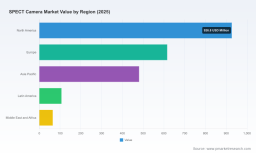
Worldwide SPECT Camera Market: Strategic Briefing for 2026 Decision-Makers
PW Consulting’s latest market study on the Worldwide SPECT Camera Market delivers a focused, action-oriented intelligence package designed to influence capital allocation, product strategy, and go-to-market planning in 2026. Built on a 2020–2025 historical base and a 2026–2032 forecast horizon, the report synthesizes primary interviews, vendor benchmarking, regulatory mapping, reimbursement analysis, and scenario-based financial models to surface near-term inflection points and durable competitive advantages.
Worldwide Virtual Office Market
Why this briefing matters for 2026
-
Macro trajectory: The global SPECT camera market—measured in USD millions—continues to expand from a 2025 baseline, with modelled output showing a near-term uplift in 2026 and a compounded annual growth rate of approximately 6.02% across the forecast period. This trajectory implies both incremental volume opportunities and rising pressure to differentiate along software, digital detector, and service dimensions.
Traffic Aggregators Market -
Consolidation signal: Market concentration is meaningful—our CR3 and CR5 metrics indicate a high degree of share control among leading incumbents, reinforcing that scale, installed-base service economics, and regulatory footprint are decisive competitive assets.
Worldwide Site Management Organization Market -
Decision window: 2026 represents a strategic window for procurement and product investment decisions: buyers will balance legacy fleet upgrades with adoption of hybrid and digital solutions; vendors must prioritize clinical evidence, reimbursement alignment, and workflow-centric AI to capture premium segments.
Core findings (high-level, non-granular)
-
Growth drivers: Aging populations in developed markets, expanding oncology and cardiology imaging volumes, and continued clinical validation of SPECT/CT hybrid workflows are the primary demand engines. Parallel advances in detector technology (including cadmium zinc telluride / CZT and digital solid-state sensors) and AI-enabled reconstruction/quantification are increasing effective throughput and diagnostic yield.
-
Technology bifurcation: The market is evolving along two complementary axes—hardware modernization (hybrid SPECT/CT, digital detectors, advanced collimation) and software-enabled workflow/value capture (AI reconstruction, automated quantification, and cloud-enabled enterprise services).
-
Commercial economics: Service revenues, consumables, and upgrade packages are becoming a larger share of lifetime value per installed system. For capital-constrained customers, bundled financing and outcome-linked service agreements will be decisive.
-
Regulatory and reimbursement dynamics: SPECT cameras are regulated as Class II devices under established device codes and require 510(k) notifications in the U.S.; procedure coding and DRG structures materially influence adoption economics across payers. Compliance with international quality and QC standards remains a gating factor for procurement.
What the report contains — practical deliverables for executives
-
Market sizing and scenario modelling: Top-down and bottom-up models from 2020 through 2032, including baseline, conservative, and upside scenarios that stress-test device replacement cycles, modality substitution, and reimbursement shifts.
-
Competitive playbooks: Vendor scorecards, product roadmaps, patent and clinical-trial intelligence, and go-to-market matrices that identify where each supplier can win or is vulnerable.
-
Clinical and technology assessment: Comparative analysis of detector technologies, AI-enabled reconstruction, and hybrid SPECT/CT architectures with guidance on clinical use-cases, throughput trade-offs, and dose-optimization strategies.
-
Reimbursement and regulatory navigator: A practical section mapping CPT/DRG implications, 510(k) pathways, and relevant standards (including minimum performance and QC standards), with recommended compliance checklists for procurement and clinical adoption.
-
Commercial models and procurement templates: Total-cost-of-ownership calculators, service-contract templates, and outcome-based contracting frameworks designed for hospital systems and imaging network consolidators.
-
M&A and partnership intelligence: Target screening, valuation multiples, and integration playbooks for investors and strategic buyers seeking scale, technology access, or geographic expansion.
Competitive landscape — strategic implications
-
Incumbent OEM strengths: Leading multinational vendors bring deep installed bases, broad regulatory clearances, and global service networks—advantages that enable premium pricing for hybrid solutions and rapid platform rollouts. They also invest heavily in AI-enabled workflow and quantification to lock in clinical workflows.
-
Disruptive specialists: Technology-focused entrants leveraging CZT and digital detectors are redefining performance benchmarks—faster scans, higher energy resolution, and targeted cardiac/oncology applications—creating opportunity to displace legacy platforms in specialized centers of excellence.
-
Regional challengers and vertically integrated solutions: Newer players combining system design with local manufacturing or tailored financing models can accelerate adoption in price-sensitive markets, particularly where service and spare-part economics are optimized for local scale.
-
Recent regulatory milestones: A sequence of clearances for advanced SPECT/CT and CZT-based systems in recent years has lowered clinical adoption barriers for higher-performance devices, while reinforcing the need for robust clinical evidence and post-market performance monitoring.
Key vendors examined
-
GE HealthCare — positioning: Broad SPECT/CT portfolio with targeted cardiac and oncology quantification capabilities; strength in global service and clinical partnerships.
-
Siemens Healthineers — positioning: Integrated AI workflows and recent regulatory clearances for intelligent SPECT/CT platforms; emphasis on productivity and standardized exam protocols.
-
Philips Healthcare — positioning: Low-dose optimized systems with strong clinical protocols for cardiac and oncology; focus on dose management and image quality trade-offs.
-
Spectrum Dynamics Medical — positioning: CZT-centric systems offering substantially higher count sensitivity and spatial resolution, enabling faster exams and new clinical applications.
-
United Imaging Healthcare — positioning: Rapidly scaling digital-detector offerings with integrated whole-body SPECT/CT solutions targeted at high-throughput oncology and cardiology centers.
-
Mediso — positioning: Niche expertise across preclinical and clinical SPECT/CT products with focused application support for translational imaging workflows.
Regulatory, reimbursement and standards landscape
-
Regulation: SPECT cameras fall under established device classification frameworks requiring premarket notifications; recent device clearances for AI-enabled systems signal regulatory receptivity when clinical benefits are demonstrated.
-
Reimbursement: Existing procedure codes and DRG classifications materially influence capital recovery timelines. Providers and vendors must synchronize clinical validation with payer engagement to secure favorable reimbursement trajectories.
-
Standards & quality: Adherence to international QC and performance standards is a minimum requirement for procurement in most systems; robust QC protocols also reduce operational risk and total cost of ownership.
Strategic recommendations for stakeholders (2026-ready)
-
For OEMs: Prioritize hybrid SPECT/CT and digital-detector upgrades where clinical outcomes and throughput uplift can be demonstrated. Bundle AI-driven workflow, remote service, and outcome-linked financing to protect margins and extend customer relationships.
-
For hospital systems and imaging networks: Adopt a portfolio approach—retain a mix of high-throughput digital systems for volume procedures, and specialized CZT-enabled units for centers of excellence. Negotiate lifecycle service agreements that align incentives around uptime and exam quality.
-
For investors and M&A teams: Seek targets that fill gaps in service networks, bring proprietary detector technologies, or provide access to differentiated clinical algorithms. Pay attention to installed-base service economics as a value driver.
-
For policymakers and payers: Encourage clinical trials that demonstrate comparative effectiveness, and align reimbursement with outcomes that reward diagnostic accuracy, lower downstream costs, and improved throughput.
What the report does not disclose here — and why
This briefing intentionally omits fine-grained geographic or application share tables and specific segment-level dollar figures in order to preserve the full strategic value of the complete report. PW Consulting’s full dataset includes granular regional splits, application-specific demand curves, and vendor-level market share estimates that are essential for transaction diligence, procurement strategy, and product prioritization.
How to use the full report in 2026 planning
-
Scenario workshops: Use the included scenario models to stress-test capital procurement plans under reimbursement shifts and device-substitution scenarios.
-
Vendor selection: Apply the vendor scorecards and technology assessments as a short-listing tool for RFPs and pilot deployments.
-
M&A diligence: Leverage the target-screening and valuation appendix to prioritize acquisition targets and build integration playbooks focused on service expansion.
-
Regulatory strategy: Follow the report’s regulatory navigator to align 510(k) strategies with post-market surveillance requirements and clinical-evidence generation.
Next steps
For executives preparing 2026 capital plans, PW Consulting’s Worldwide SPECT Camera Market report is built to convert market intelligence into executable strategy—balancing clinical, commercial, and regulatory lenses. To access the complete dataset, vendor-level shares, and the procurement-ready appendices that underpin these recommendations, please visit our report page and download the full study.
For detailed analysis of this topic, please visit the official page: Worldwide SPECT Camera Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com