

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Worldwide During Production Inspection (DPI) Market to Hit USD 845.05 Million by 2032 on a 6.45% CAGR

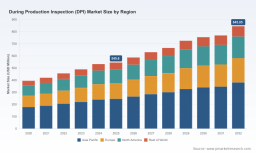
Worldwide During Production Inspection (DPI) Market: Strategic Imperatives for 2026
PW Consulting’s latest market research on the Worldwide During Production Inspection (DPI) market delivers a focused, operationally grounded view designed to inform boardroom and procurement decisions in 2026. Our analysis shows a market that has accelerated from roughly USD 395 million in 2020 to approximately USD 546 million in 2025 and is forecast to expand to about USD 845 million by 2032, reflecting a compound annual growth rate of 6.45% over the forecast horizon. These headline figures underscore a durable, mid-single-digit growth opportunity underpinned by regulatory tightening, supply-chain risk management, and rapid technology adoption — but they also mask critical differentiation between service models, verticals and geographies. This release summarizes the strategic takeaways and describes the hands-on tools embedded in the full report (with detailed segmentation and datasets available via our website).
Containerized Mobile Renewable Energy Unit Market
Why 2026 Is a Strategic Inflection Point
Three forces converge in 2026 to make DPI an operational priority rather than a cost center: (1) heightened regulatory scrutiny that elevates liability and product surveillance during manufacturing; (2) commercial pressure to shorten time-to-market while maintaining quality; and (3) rapid adoption of digital remote monitoring and analytics that change how inspection services are delivered and priced.
Robotic Agent Market
- Regulatory drivers: International standards governing inspection body competence (e.g., ISO/IEC 17020) and regional market surveillance frameworks are increasingly explicit about inspecting during production. Compliance programs are becoming prerequisites to market entry in multiple jurisdictions.
- Technology disruption: Remote digital monitoring is shifting the economics of DPI. Adoption accelerates cost-efficient coverage of distributed supplier bases, but it also requires new controls, cybersecurity considerations, and data governance.
- Labor and automation: The median annual wage for quality control inspectors and the projected employment shifts driven by automation should prompt firms to re-skill and reconfigure inspection staffing as part of broader productivity investments.
Market Trajectory and Capital Allocation Implications
The DPI market’s compound annual growth rate of 6.45% through the forecast period suggests steady expansion, driven by both legacy on-site verification and a growing layer of remote and hybrid services. For 2026 capital allocation, executives should treat DPI as a strategic enabler of resilient supply chains: investments that reduce recall risk, accelerate supplier onboarding, and protect brand value.
Intelligent Driver Testing and Training System Market
- Investment focus: Prioritize capex and opex that create modular inspection capabilities — for example, hybrid inspection teams, remote monitoring platforms, and integrated lab-to-inspection workflows.
- M&A and partnerships: Expect mid-market consolidation opportunities where global reach, digital platforms, or specialized vertical expertise can be stitched into client-facing bundles.
- Service packaging: Shift from time-and-material inspection contracts to outcome-based and subscription models tied to quality KPIs and reduced time-to-release.
What the Report Contains: Practical, Actionable Deliverables
PW Consulting’s DPI report is designed as an operator’s toolkit for 2026. The full publication contains:
- Methodologies and data: Transparent forecasting approach, model assumptions, sensitivity tests and downloadable time-series for the overall market.
- Operational playbooks: Standardized inspection protocols, decision trees for choosing on-site vs. remote inspections, templated RFPs and SOWs, and contractual clauses to manage workmanship, data ownership and liability.
- KPI and benchmarking frameworks: Benchmarks for inspection pass/fail rates, defect distributions, cycle-time to corrective action and customer holdback metrics tailored to industry verticals.
- Digital adoption roadmap: A phased implementation plan for remote monitoring, including vendor selection criteria, pilot KPIs, integration checklists for ERP/QMS systems and expected ROI timelines.
- Procurement and supplier selection: Due-diligence checklists and scorecards that align inspection scope with supplier risk tiers and regulatory obligations.
- Scenario playbooks: Stress-tested action plans for regulatory shifts, factory closures, or rapid SKU proliferation — including contingency staffing, rapid audit templates, and escalation workflows.
These assets are intentionally operational: procurement teams, quality directors and compliance officers can extract immediate, tactical change items without needing to rework our models.
Competitive Landscape: Who Matters and How They Compete
The DPI market is characterized by a mix of large, diversified assurance providers and focused specialists. Market concentration is moderate: our concentration analysis shows that the top three providers account for a meaningful but not dominant share, and the top five amplify that position — an environment that supports both scale plays and specialist entrants.
- SGS (Geneva): A global leader with deep on-site verification capability across electronics, automotive and consumer goods. Their strength is international footprint and cross-border logistics for large-scale retail and industrial programs.
- Bureau Veritas (Neuilly‑sur‑Seine): Known for integrating DPI within broader supplier audit and production monitoring suites, making them attractive for enterprises seeking single‑vendor assurance stacks.
- Intertek (London): Focuses on real-time quality assurance for hardgoods and electrical products; successful at packaging testing and DPI into tight product release timelines.
- TÜV Rheinland (Cologne) & TÜV SÜD (Munich): European specialists emphasizing industrial, automotive and renewables. Their competitive edge is technical depth and process monitoring expertise.
- DNV (Bærum) & LRQA (London): Bring sector-specific assurance for maritime, oil & gas and energy projects, often coupling DPI with certification and lifecycle assurance.
- DEKRA (Stuttgart), Eurofins (Luxembourg City) & UL Solutions (Northbrook): Offer complementary capabilities — DEKRA with vehicle/industrial focus, Eurofins with integrated testing for life sciences and consumer health, UL with safety compliance and appliance testing.
- Kiwa (Rijswijk), Cotecna (Geneva), Applus+ (Barcelona): Regional specialists that combine local standards expertise with targeted laboratory networks and trade facilitation services.
For buyers, this landscape implies three practical behaviors: (1) use competition to drive bundled pricing where labs + DPI deliver tangible cycle-time improvements; (2) seek regional partners with local regulatory expertise; and (3) evaluate digital capability as a primary procurement criterion, not an optional add‑on.
Strategic Playbook for 2026 Decision-Makers
We advise a prioritized, two-year program for firms that wish to convert DPI from a compliance checkbox into a competitive advantage:
- Adopt a hybrid delivery model: Combine targeted on-site inspections with continuous remote monitoring. Start with a small cohort of high-risk suppliers and scale by ROI.
- Embed regulatory readiness: Update supplier contracts and SOPs to reflect ISO/IEC 17020 competence criteria and applicable market surveillance rules. Build regulatory triggers into your supplier tiering logic.
- Reskill quality teams: Reallocate headcount from routine inspection tasks to analytics, exception management and supplier engineering support. Use automation to redeploy inspectors toward higher-value verification.
- Invest in data interoperability: Prioritize platforms that integrate inspection reports with ERP, PLM and supplier portals to reduce reconciliation lag and accelerate root-cause workflows.
- Pursue strategic partnerships: Where internal build is slow, use joint ventures or white‑label arrangements with established DPI providers to accelerate geographic or vertical expansion.
- Revise commercial models: Experiment with outcome-based pricing tied to defect rates, time-to-corrective-action and reduced rework costs.
Risk Factors and Contingency Measures
Leaders must evaluate three clusters of risk as they scale DPI capability:
- Regulatory volatility: Enforcement scope and technical standards evolve; maintain a regulatory horizon-scanning function and escalate changes into contract clauses.
- Technology adoption lag: Remote monitoring reduces cost but increases reliance on data integrity. Pilot cybersecurity and data governance early in the deployment cycle.
- Workforce transition risk: Automation reduces routine inspector roles; institute retraining programs and maintain knowledge transfer protocols to preserve institutional expertise.
How PW Consulting Can Accelerate Your 2026 Outcomes
PW Consulting supports executive teams with tailored services that move beyond diagnostics into implementation. Our offering includes:
- Due diligence for DPI-related M&A and partnerships, including commercial, operational and technology assessments.
- Vendor selection and contracting support that embeds regulatory and data-governance requirements.
- Pilot design and scaled roll-out roadmaps for hybrid inspection programs, with KPI dashboards and measurable cost/quality targets.
- Regulatory gap analysis against ISO/IEC 17020 and major market surveillance frameworks, plus remediation roadmaps.
- Workforce transformation programs focused on inspector upskilling, productivity metrics and transition incentives.
Each engagement is calibrated to the commercial levers most material for the client — whether margin protection, speed-to-market or risk mitigation.
Closing: What You Can Do Next
DPI is a growing, structurally important market segment. Its forecast trajectory points to continued investment, but the shape of value capture will differ markedly between scale-driven service providers and niche specialists. To translate market growth into competitive advantage in 2026, executives must move from ad-hoc inspection commissioning to integrated assurance strategies that combine regulatory readiness, digital-enabled monitoring and supplier engineering partnerships.
PW Consulting’s full Worldwide DPI Market report provides the detailed segmentation, country-level overlays, and downloadable datasets to operationalize these recommendations. The document also includes proprietary benchmarking tables and vendor scorecards to expedite procurement decisions — an essential next step for teams that want the full, implementable intelligence behind this executive summary.
For detailed analysis of this topic, please visit the official page: Worldwide During Production Inspection (DPI) Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com