

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Worldwide Brake Force Sensors Market to Expand at 9.2% CAGR, Reaching USD 897.84 Million by 2032

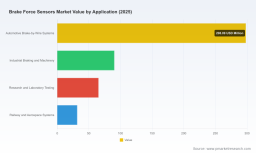
Worldwide Brake Force Sensors Market — Strategic Outlook and 2026 Imperatives
Executive snapshot
PW Consulting’s new market study on the Worldwide Brake Force Sensors market delivers a compact but rigorous briefing tailored to executives who must decide where to allocate capital, engineering resources, and go-to-market effort in 2026. The market crossed the half‑billion USD mark in our 2025 base year and — under our central forecast — is projected to grow at a 9.2% compound annual growth rate (CAGR) through the 2026–2032 horizon, with the model forecasting near‑doubling of market value by 2032. These headline figures capture both the opportunity size and momentum for players across the automotive, industrial and test & validation ecosystems.
Worldwide Ophthalmology EMR Software Market
Why this matters for 2026 decisions
- Timing of investment: With market growth accelerating into the latter half of the decade, 2026 is the inflection point when product investments, supplier qualification, and manufacturing ramp plans convert into share gains or missed windows.
- Technology steering: Brake force sensing is at the intersection of hardware sensor innovation, electronic brake architectures (including brake‑by‑wire and EMB), and functional safety. Product choices made in 2026 will harden a company’s competitive position for the next vehicle platform cycle.
- Regulatory synchronization: New and tightening rules around active safety systems and brake performance testing increase the strategic value of validated force measurement solutions that can demonstrably support compliance and reduce validation risk.
What the report delivers — practical, actionable content
Our study is designed as an operator’s manual for strategy teams, product leaders, procurement and corporate development. It blends rigorous market measurement with tools that accelerate execution. Key deliverables include:
ELISA Reader Market
- Validated market trajectory: Annual historicals and a granular scenario forecast framework covering 2026–2032 that translates broader macro trends into addressable market outlooks under three adoption pathways.
- Go‑to‑market playbooks: Segment‑specific commercial approaches for OEMs, Tier‑1s and specialist test houses — including positioning, pricing levers, channel strategies and partner archetypes.
- Supplier and capability mapping: A practical supplier landscape that aligns core technical approaches (strain gauge, piezoelectric, capacitive/optical and proprietary hybrids) to application profiles, manufacturing complexity and ASIL/FuSa readiness levels.
- Functional safety & integration checklist: A concise, actionable checklist to accelerate FuSa validation, reduce rework and harmonize sensor integration across hydraulic, electromechanical and x‑by‑wire platforms.
- Test & validation protocols: Benchmarks and recommended test sequences for durability, repeatability and EMC/EMI robustness — essential for supplier selection and supplier audits.
- Commercial diligence templates: Standardized models for unit economics, BOM sensitivity analysis, capital intensity and ramp timelines to support M&A, JV or Tier‑1 sourcing decisions.
- Risk & regulatory scenario modeling: Impacts of pivotal regulations (AEB mandates, heavy‑vehicle braking standards and FuSa requirements) on product compliance costs, time‑to‑market pressures and potential liability exposures.
Competitive landscape — what the market structure means
The market exhibits a moderate level of concentration: the top three suppliers account for a material minority of global demand, while the top five push that share substantially higher. That structure creates a dynamic where specialist innovators and incumbent sensor platforms co‑exist — enabling rapid adoption of new technologies alongside continued reliance on established measurement solutions.
Nickel-Metal Hydride Button Cell Market
Key competitive archetypes identified in the study:
- Systems integrators with FuSa depth (e.g., TE Connectivity): These players compete on integrated sensor suites, system‑level validation and the ability to deliver components that meet ASIL requirements for advanced brake controllers.
- Sensor specialists with production scale (e.g., Sensata Technologies): Suppliers leveraging micro strain gauge or similar in‑caliper measurement technologies are positioned to service closed‑loop electromechanical brake systems and EMB platforms for EVs and passenger vehicles.
- Application‑centric innovators (e.g., Methode Electronics): Providers focused on pedal and drive‑input sensing — often using magnetoelastic or other non‑contact approaches — are capturing roles in driver input verification and emergency backup systems.
- Test & instrumentation vendors (e.g., FUTEK, Strainsert, Althen Sensors): Specialist load cell and force sensor manufacturers retain strong footholds in R&D, endurance testing and validation channels, with bespoke products for laboratory environments and component qualification.
Recent in‑market signals validate our competitive reading. For example, a leading supplier’s production nomination with several OEM brake system manufacturers underscores how rapidly force sensors are being embedded into next‑generation electromechanical brake modules — a commercial transition that will profoundly affect supplier selection, tiering, and integration responsibilities during 2025–2026 product qualification cycles.
Regulatory and standards dynamics shaping risk and value
- Active safety mandates: Recent regulatory actions on automatic emergency braking (AEB) increase the requirement for robust braking actuation and supplemental measurement in many light‑vehicle classes. These mandates raise the value of validated force sensing within overall brake application strategies.
- Functional safety (ISO 26262): Meeting Automotive Safety Integrity Levels (ASIL) remains a prerequisite for any sensor intended for closed‑loop control or safety‑critical verification. Suppliers that can demonstrate FuSa‑compliant development processes and evidence packages reduce OEM integration cost and schedule risk.
- Brake system performance standards: Heavy‑vehicle brake performance rules and federal standards for brake systems impose testing and documentation burdens that can favor suppliers offering turnkey measurement and validation suites.
Strategic plays for 2026 — concise choices for leadership
From our advisory engagements and scenario analysis, the most productive actions for 2026 cluster into three categories:
- De‑risk product integration: Prioritize suppliers with demonstrated FuSa toolchains and evidence artifacts. Short‑list partners that can supply sample quantities and engineering support within a 6–9 month qualification window.
- Segment capture via adjacent capability: For mid‑sized suppliers and Tier‑1s, marrying force sensing with related brake control electronics or system calibration services is the fastest path to move up the value chain and capture recurring program revenues.
- Investor & M&A focus: Target bolt‑on acquisitions that provide either validated ASIL artifacts, in‑vehicle production nominations, or unique measurement IP that shortens time‑to‑market for EMB and brake‑by‑wire platforms.
How the PW Consulting report supports operational execution
This study is not an academic exercise. It is structured to be used in boardrooms, procurement committees and product councils. Subscribers receive:
- Decision matrices that prioritize opportunities by profitability, integration risk and ramp timeline;
- Supplier due‑diligence checklists and red‑flag indicators for technical, quality and supply continuity issues;
- Commercial templates for negotiating development milestones, NRE recovery and volume price curves;
- Practical scenario modeling files that let teams re‑cast our baseline forecasts into company‑specific demand and investment cases.
What we are deliberately not disclosing here — and why
In line with the “trailer” principle for this briefing, we are showing the analytical depth and the decision‑ready outputs you need to act, while withholding the granular segment allocations and application‑level dollar splits that form the core proprietary intelligence of the full report. This summary therefore omits detailed breakouts by region, technology and application to protect the integrity of the calibrated datasets and to ensure subscribers derive exclusive advantage from the full deliverable.
Next steps and call to action
For executive teams preparing 2026 capital and product roadmaps, the principal questions are not whether brake force sensing matters — they already do — but how rapidly you will operationalize that knowledge. PW Consulting’s full report provides the calibrated market model, supplier scorecards, FuSa readiness rubrics and commercial playbooks required to convert insight into measurable competitive advantage.
Contact PW Consulting to schedule a briefing and obtain the full report package. Our advisory team will walk your leadership through a tailored scenario exercise and supply the procurement, engineering and M&A templates required to reduce time‑to‑value on your 2026 initiatives.
For detailed analysis of this topic, please visit the official page: Worldwide Brake Force Sensors Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com