

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting Forecasts 4.85% CAGR for Worldwide IR Carbon Sulphur Analyzers Market Through 2032

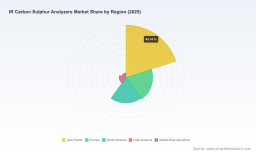
Worldwide IR Carbon Sulphur Analyzers Market — Strategic Preview for 2026 Decision-Makers
Executive summary
As of our 2025 base-year assessment, the global market for infrared (IR) Carbon Sulphur analyzers has matured into a mid-sized, concentrated sector characterized by steady, engineering-driven demand and pockets of rapid adoption tied to materials critical to decarbonization and high‑performance manufacturing. PW Consulting’s newest market model shows the market growing from roughly USD 383.1 Million in 2020 to USD 485.5 Million in 2025, and continuing on to an estimated USD 676.4 Million by 2032 — a compound annual growth rate (CAGR) of approximately 4.85% across the 2026–2032 forecast window.
Worldwide Punch & Die Storage Cabinet Market
This briefing is designed as a strategic “trailer”: it surfaces the most consequential dynamics that should influence capital allocation, procurement timing, product roadmaps, and M&A intent for 2026 — while reserving the granular segment tables and regional share matrices for the full report. The objective is to give senior leaders immediate, actionable perspective and to motivate targeted follow-up on our site for the detailed intelligence that guides execution.
Water in Oil Analyser Market
Market trajectory and what the numbers mean for 2026
-
Macro growth is steady, not sensational. The trajectory from USD 383.1M (2020) to USD 485.5M (2025) and our forecast through 2032 signals a market with healthy reinvestment in laboratory automation, throughput optimization, and expanded process-control deployments in heavy industry. Expect incremental, technology-driven demand rather than explosive, consumer-style adoption.
Worldwide Insurance Compliance Software Market -
Concentration favors incumbent engineering specialists. The top three vendors account for a majority share of the market (CR3 ~58.4%); the top five hold a dominant position (CR5 ~72.2%). This concentration reduces price erosion risk but raises barriers for new entrants who cannot differentiate by instrumentation performance, application breadth, or aftermarket services.
-
Near-term buying windows will be defined by process cycles. Capital purchases for high-throughput labs and process-control integration will follow discrete industrial investment cycles — for example, plant modernization in metallurgy or expansion in cement and battery materials. Procurement teams should align replacement and expansion CAPEX with these cycles to avoid oversupply and to capture vendor promotional windows.
Strategic implications for 2026 planning
-
Prioritize TCO and uptime over lowest first cost. Given the market’s technical maturity and the importance of continuous process-control data, selection criteria will weigh lifetime service, parts availability (including crucibles and accelerators), and software integration more heavily than headline price. Buyers should require vendor-provided Total Cost of Ownership (TCO) models covering consumables and preventive maintenance across plausible duty cycles.
-
Lock supply for critical consumables. Across major instrument platforms, ceramic crucibles and high‑purity tungsten accelerators remain indispensable consumables for combustion analysis. Disruptions to these supplies (or shifts in grain‑size specifications) can materially affect instrument throughput and reproducibility. Procurement and operations teams should implement multi‑year supply agreements or qualify multiple approved suppliers for accelerators and crucibles in 2026.
-
Differentiate by systems integration. Equipment makers that bundle robust data management, LIMS/API connectivity, and predictive maintenance capabilities will capture a premium as industrial labs seek to fold elemental analysis into broader digital quality ecosystems. Technology investments in cloud-enabled diagnostics and automated QC workflows will deliver disproportionate returns for vendors and for labs that adopt them early.
-
Invest in modularity and multi-matrix capability. Instruments that can handle both inorganic (e.g., metals, alloys) and organic matrices (e.g., coal, some waste streams) — or that offer dual-furnace workflows — lower the cost of ownership for mixed-use labs. Buyers planning expansions in 2026 should explicitly test cross-matrix performance and throughput when evaluating proposals.
-
Embed environmental and regulatory readiness. As process-control reporting demands increase, instruments and vendors able to demonstrate low-emissions workflows, safe handling of combustion byproducts, and documentation to support regulatory audits will have an edge in tender evaluations.
Competitive landscape — who matters and why
The competitive topology remains dominated by a handful of engineering-intensive players with deep application expertise and extensive installed bases. Our qualitative assessment highlights each firm’s strategic posture and where they are likely to exert influence in 2026 procurement decisions:
-
HORIBA, Ltd. (Kyoto, Japan): Known for the EMIA line — from entry models to flagship EMIA‑Expert — HORIBA couples induction-furnace combustion with NDIR detection optimized for inorganic matrices. Their focus on throughput, operator ergonomics, and moisture-handling improvements makes them a logical choice for high-volume metallurgy and alloy labs.
-
ELTRA GmbH (Verder Scientific) (Haan, Germany): ELTRA’s ELEMENTRAC family — including dual-furnace models — provides flexibility across organic and inorganic sample types. Product-line expansion into CN and ONH instruments signals a cross-sell strategy to laboratories seeking consolidated elemental-analysis platforms.
-
LECO Corporation (St. Joseph, USA): LECO’s 744/844 line and application outreach into cement and process control underline a vertical-market approach: tailored solutions for raw-material testing and plant-level control. Their fortified application messaging (e.g., 2026 emphasis on cement production control) makes them a strong partner for process-centric buyers.
-
Elementar Analysensysteme GmbH (Langenselbold, Germany): Elementar’s inductar and CS cube platforms emphasize speed and simultaneity in carbon/sulfur measurement — appealing to labs focused on fast turnaround and multi-sample workflows.
-
Bruker Corporation (Billerica, USA): Bruker’s G4 ICARUS Series 2 integrates high-frequency induction combustion with sensitive detection and positions itself on the precision and speed axes, making it a contender for high-value industrial research and advanced materials QA/QC.
-
Labtron Equipment Ltd. (UK), Torontech Group (Canada), BIOBASE Group (China), JIEBO Instrument (China): These regional and niche specialists compete on price/performance balance, aftermarket responsiveness, and tailored service packages. They are particularly relevant for labs with constrained budgets or regionally specific service requirements.
Recent vendor moves and their operational implications
-
LECO (Feb 2026) — Repositioning of the SC832 Series toward cement production raw-material control underscores the continued importance of vertical application strategies. For plant operators, this signals improved instrument fit-for-purpose and vendor willingness to commit to process-focused validation activities.
-
HORIBA (Jan 2025) — Updated EMIA documentation emphasizing throughput and moisture-handling highlights incremental hardware and consumable optimizations that reduce rework and sample failure rates — features that materially affect per-sample costs in high-volume labs.
-
ELTRA (2025) — The expansion of ELEMENTRAC platforms into CN and ONH domains demonstrates a platform consolidation strategy: vendors seek to increase wallet share by offering instruments that reduce the need for multiple disparate analyzers.
Technology, consumables, and supply‑chain considerations
From a practical procurement standpoint, three technical realities will shape purchasing decisions in 2026:
-
Furnace and detection choices matter: High-frequency induction furnaces remain the preferred route for inorganic solids; dual‑furnace architectures offer flexibility for mixed-matrix labs. Detection techniques centered on infrared (NDIR) remain the industry standard for carbon and sulfur quantitation in combustion workflows.
-
Consumable risk is real: Ceramic crucibles and tungsten or blended tungsten accelerators are not optional add-ons — they are operational enablers. Grain-size, purity, and crucible integrity affect combustion completeness and precision. 2026 sourcing strategies should therefore include validated second-source suppliers and inventory buffers to prevent analytic downtime.
-
Aftermarket and calibration services are revenue multipliers: Vendors that can bundle proactive calibration, remote diagnostics, and guaranteed spare-part SLAs will command premium pricing and longer service contracts. For buyers, negotiating embedded service credits and uptime guarantees will reduce long-run operational risk.
What the PW Consulting report contains — practical tools for leaders
Our full Worldwide IR Carbon Sulphur Analyzers Market report (base year 2025; historical 2020–2025; forecast 2026–2032) is structured to support action by procurement, R&D, and corporate development teams. Key deliverables include:
-
Robust market-sizing and scenario modeling (including the CAGR and multi-year forecast paths) to stress-test CAPEX timing and ROI assumptions.
-
Vendor heatmaps with qualitative scoring across throughput, matrix versatility, service footprint, and digital-integration readiness.
-
Buy-side playbooks: RFP templates, TCO calculators, consumables qualification checklists, and sample-test protocols to validate vendor claims under real-world matrices.
-
Supply-chain risk analysis for critical consumables and recommended mitigations, including dual-sourcing templates and inventory trigger points.
-
M&A and partnership screening criteria for strategic buyers looking to expand capabilities or enter adjacent elemental-analysis markets.
Final recommendations for 2026
-
Align procurement cycles with process modernization projects to maximize vendor concessions and minimize integration friction.
-
Define procurement requirements around validated TCO and uptime SLAs, not only instrument specifications.
-
Secure multi-year supply or dual-source agreements for ceramic crucibles and tungsten accelerators to protect throughput and data quality.
-
Prioritize vendors demonstrating active investments in digital diagnostics and plant-level integration capabilities — those investments are where incremental value will accrue over the next buying cycle.
Next steps
This industry preview highlights the levers that will most affect capital, operational, and strategic choices in 2026. For a deeper dive into vendor rankings, regional adoption scenarios, and the full dataset that underpins our forecast (including the detailed segmentation tables and buy-side tools), please visit the report landing page on PW Consulting’s website or contact our industry analytics team to schedule a briefing.
For detailed analysis of this topic, please visit the official page: Worldwide IR Carbon Sulphur Analyzers Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com