

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting Report: Worldwide Nuclear-Grade LED Lighting Market Poised to Expand at a 5.85% CAGR During 2026–2032

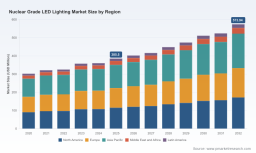
Worldwide Nuclear Grade LED Lighting Market — Strategic Preview for 2026 Decision-Makers
Executive summary
The Worldwide Nuclear Grade LED Lighting Market is entering a phase of sustained, engineering-led expansion that will materially affect procurement, OEM roadmaps, and capital planning across utilities, research institutions, and specialized contractors in 2026. Our latest market model projects growth from an estimated USD 385.5 Million in 2025 to roughly USD 574.0 Million by 2032, reflecting a compound annual growth rate (CAGR) of approximately 5.85% over the forecast window. These headline dynamics mask a number of operational and regulatory pressures that are reshaping buyer requirements and supplier strategies — factors that must be explicitly integrated into any near-term capital and sourcing decisions.
Cryogenic Amplifier Market
Why this matters for 2026 planning
-
Risk-adjusted procurement: Nuclear facilities are moving beyond lowest-first-cost buying toward validated life-cycle sourcing that prioritizes radiation tolerance, LOCA compatibility, seismic qualification, and long-duration emergency illumination. The market’s moderate growth does not dilute the need for higher-certainty suppliers; rather it concentrates strategic value in validated, compliant solutions.
Manual Pallet Trucks Market -
Operational resilience: Emergency systems and containment-area lighting are increasingly viewed as system-level enablers of plant safety cases. Decisions made in 2026 on lighting platforms will carry through multi-decade asset management cycles; early alignment with recognized standards reduces retrofit and requalification risk.
Electric Vehicle Graphene Battery Market -
CapEx-to-OpEx trade-offs: Advances in radiation-hardened LEDs and integration of sealed housings, driver-less designs, and maintenance-free batteries are shifting total cost of ownership calculations. A higher upfront investment in certified, low-maintenance luminaires often delivers compelling operational savings and lower outage risk.
Market trajectory and what the headline numbers conceal
The aggregate numbers show steady expansion — a predictable outcome of ongoing plant life-extension programs, new-build activity in specific markets, and replacement cycles for legacy lighting installations. But the headline growth rate obscures several important nuances that should shape 2026 strategies:
-
Performance over price: Buyers are increasingly selecting solutions based on qualification regimes (gamma irradiation testing, LOCA compatibility, seismic ratings) and demonstrable in-field life, not merely initial luminous efficacy.
-
Integration complexity: The most commercially successful offerings tightly integrate mechanical design, optics, and driver engineering to avoid external driver shielding and to ensure predictable behavior under extreme radiation doses and thermal cycles.
-
Regulatory interplay: Compliance requirements (for example, seismic qualification per IEEE-344, extended emergency illumination periods compatible with 10CFR50 Appendix R expectations, and system-level environment controls influenced by IEC 62954:2019) are non-negotiable procurement filters for U.S. and many international operators.
Report contents — practical, executable intelligence
The full PW Consulting report is structured to be operationally useful to decision-makers preparing 2026 budgets and procurement strategies. Key actionable elements include:
-
Validated market model and scenario analysis — a forward-looking revenue model (base year 2025) with sensitivity cases tied to new-build timing, life-extension rates, and replacement cycles through 2032.
-
Procurement playbooks — checklist-driven RFP language, mandatory qualification tests (gamma dose thresholds, LOCA compatibility), and vendor QA/QC expectations (e.g., 10CFR50 Appendix B–aligned production controls) that reduce buyer negotiation effort and rework risk.
-
Technical evaluation framework — a vendor scoring matrix that weights radiation tolerance, seismic certification (IEEE-344), emergency illumination duration, maintainability (decontamination-friendly surfaces, stainless housings), and EMC behavior to protect instrumentation and control systems.
-
Replacement and retrofit roadmaps — cost/benefit templates and risk matrices for refit vs. staged replacement that align with outage windows and ALARA constraints.
-
Supplier diligence templates — a compact due-diligence pack for validation of in-house capabilities (mechanical, LED, and driver production), third-party testing records, and post-delivery support commitments.
Competitive landscape — practical takeaways for sourcing and partnerships
The nuclear-grade LED lighting supply base is a specialist ecosystem. Market concentration is meaningful: the top suppliers collectively command a sizable share of the global revenue pool, creating a market where technical differentiation and certification readiness drive commercial outcomes. Our strategic assessment of incumbent and specialist manufacturers highlights several patterns:
-
Full-stack specialists with in-house testing and manufacturing (examples include firms with integrated LED, driver, and mechanical production) are positioned to command premium pricing for mission-critical applications because they can demonstrate traceable component selection and controlled assembly processes.
-
Firms with proven high-dose tolerance and LOCA-compatible designs — validated by gamma testing programs and published endurance data — have a clear edge for containment and high-radiation zones.
-
Seismic-qualified emergency fixture suppliers are particularly favored in regions and facility types where IEEE-344 and Appendix B–style quality programs are enforced; their product claims (e.g., multi-day emergency illumination, maintenance-free battery systems, seismic mounting) are decisive procurement differentiators.
Representative supplier strengths uncovered in our vendor profiles:
-
Companies that combine radiation-hard component selection with sealed stainless housings and decontaminable finishes are repeatedly selected for pool, hot-cell, and containment applications.
-
Suppliers offering driver integration that avoids external shielding — together with demonstrated thermal and photometric stability under irradiation — lower system-level integration cost and requalification risk.
-
Those who maintain documented quality systems aligned with nuclear QA requirements (including production under Appendix B–style programs) materially reduce buyer audit burden and timeline uncertainty.
Recent product and regulatory developments you must factor into 2026 decisions
-
Product evolution: Selected manufacturers released upgraded models in early 2025 that emphasize custom CoB LEDs, improved mechanical stability, and enhanced thermal management to maintain photometric performance under prolonged irradiation. These iterations illustrate a clear industry trend: incremental hardware improvements are being used to preserve lumen output and reliability in environments where replacement is costly and hazardous.
-
Radiation validation: Third-party gamma testing programs continue to be a gating factor. Vendors are publishing higher dose tolerances and expanded LOCA compatibility test results. Procurement teams should insist on seeing test protocols, traceable lab credentials, and sample-level photometric retention curves post-irradiation.
-
Regulatory reality: Seismic design per IEEE-344, emergency duration specifications aligned with 10CFR50 Appendix R, and IEC environment-control considerations are not theoretical—they are procurement filters that materially affect lead times, design choices, and supplier selection.
Strategic recommendations for 2026
-
Adopt a qualification-first RFP: Embed gamma test pass/fail criteria, LOCA compatibility requirements, seismic certification, and QA-program evidence into tender documentation to accelerate evaluation and reduce change orders.
-
Prioritize supplier traceability: Give preference to manufacturers that produce or tightly control LED chips, drivers, and mechanical housings, and that can demonstrate in-house or contracted third-party irradiation testing.
-
Model TCO with scenario stress tests: Include extended emergency illumination, decontamination cycles, and the cost of unplanned replacements in life-cycle models rather than relying on nominal lumen-hour figures alone.
-
Lock in lead times and spares strategy: Given the specialized nature of some components, negotiate spares kits and priority remanufacture clauses as part of the purchase agreement to avoid protracted outages.
-
Integrate regulatory checkpoints into program governance: Align procurement milestones with QA audits and third-party test result reviews so that certifications are in place before factory acceptance testing.
How PW Consulting’s report supports execution
This intelligence package is designed to be directly operational. Subscribers receive downloadable RFP templates, supplier scorecards, compliance checklists, and a scenario-based financial model calibrated to 2025 baseline data and the forecast path to 2032. Additionally, the report includes concise vendor profiles and a short-listing tool that translates technical criteria into procurement-ready pass/fail gates — enabling teams to make defensible supplier choices in 2026 with less reliance on expensive expert second opinions.
Concluding note — the strategic opening
The market for nuclear-grade LED lighting is maturing: steady aggregate growth conceals a transition toward certification-driven competition where technical proofpoints and production governance determine market access. For utilities and technical buyers making allocation choices in 2026, the priority is to convert headline market certainty into procurement-level assurance. Our full report provides the detailed segmentation, vendor-validated test data, and contractual templates required to do that — intentionally withheld from this preview to preserve the commercial value of the complete analysis.
To access the full model, detailed supplier dossiers, and the procurement toolkit that will shorten your 2026 decision cycle, visit the PW Consulting report page for the Worldwide Nuclear Grade LED Lighting Market.
For detailed analysis of this topic, please visit the official page: Worldwide Nuclear Grade LED Lighting Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com