

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
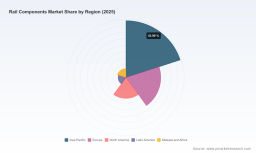
PW Consulting: Worldwide Rail Components Market to Grow from USD 72.45 Billion in 2025 to USD 99.6 Billion by 2032 (2026–2032 Forecast) at 4.65% CAGR — Asia‑Pacific Leads with 31.9% Share

Worldwide Rail Components Market 2026: Strategic Imperatives from PW Consulting’s Latest Study
As the rail components industry moves from recovery to structural transformation, PW Consulting’s newest Worldwide Rail Components Market report equips executives with the forward-looking intelligence they must act on in 2026. Anchored on a 2025 base year and drawing on a five‑year historical series (2020–2025) and a 2026–2032 forecast horizon, the analysis sets out a clear macro trajectory: the global market stands at USD 72.45 billion in 2025 and is projected to grow to roughly USD 99.6 billion by 2032, reflecting a compound annual growth rate of 4.65% across the forecast period. This release is designed as a strategic briefing — it demonstrates the depth of our modelling and scenario work while directing decision-makers to the full report for the granular segment-level intelligence that underpins investment and procurement decisions.
Worldwide Policy Management Software Market
Why 2026 Is a Decision Point
Multiple converging forces make 2026 the year to translate strategy into binding commitments. Regulatory clocks are driving certification and interoperability deadlines across major markets, while carbon policy and tariff mechanisms are reshaping sourcing economics. At the same time, material cost volatility and accelerating adoption of automation and digital fleet management are altering the value equation for OEMs, suppliers, and asset owners.
Photovoltaic DC Distribution Box Market
- Regulatory triggers: New signaling and onboard interoperability mandates have crystallized technology roadmaps for rolling stock and wayside systems — increasing compliance-driven procurement and creating windows to capture retrofit opportunities.
- Carbon and trade exposure: Emerging carbon-border measures and import tariff frameworks are forcing reassessments of localisation, supplier selection, and total landed cost calculations.
- Input volatility: Rail steel markets have seen double-digit year-on-year price pressure driven by energy and input-cost dynamics, and demand for advanced bainitic steels for high-speed lines has strengthened the premium-steel segment.
- Technology inflection: Production automation, driverless platform components, and digital fleet optimisation are migrating from pilots to serial deployments, shifting value from pure mechanical supply toward integrated systems and services.
What the Report Delivers — Practical, Board-Level Tools
PW Consulting’s report is structured for action. It goes beyond descriptive market sizing to deliver operational tools that teams can apply immediately in 2026 planning cycles:
AGV & Forklift Battery Market
- Robust market sizing and topline forecasting (historical 2020–2025; forecast 2026–2032) expressed in USD billion, with sensitivity runs that test price, demand, and policy shocks against a base-case path consistent with a mid-single-digit CAGR.
- Scenario playbooks: three investment scenarios (accelerated modernization, regulated compliance wave, and cost‑constrained replacement) that translate macro forecasts into procurement volumes and capex phasing for OEMs and infrastructure owners.
- Supplier benchmarking frameworks that evaluate scale, product scope, technology readiness, and aftermarket capability — constructed to inform make-versus-buy and M&A prioritisation without disclosing confidential supplier metrics.
- Supply‑chain risk heatmaps and mitigation templates that quantify exposure to steel-price volatility, single-source manufacturing, and geopolitical tariffs, and recommend contractual hedging and localization levers.
- Commercial playbooks for lifecycle cost negotiations, including approaches for embedding digital services, spare parts strategies, and performance-based contracting.
Competitive Landscape: Who Matters and How
The industry remains moderately concentrated, requiring different strategic responses depending on whether a buyer or supplier seeks scale, specialization, or niche differentiation. Our concentration analysis shows a clear leader cluster and a broader competitive tier — a structure that favours strategic partnerships and selective consolidation rather than pure price competition alone.
Key corporate dynamics to watch (illustrative insights rather than exhaustive profiles):
- Alstom — With deep product breadth across bogies, braking systems, and signaling interfaces, Alstom remains a go-to partner for integrated rolling-stock projects; ongoing collaboration models with national rail authorities signal a continued focus on localized co-development.
- Siemens Mobility — A leader in electrification, automation and signalling; the launch of higher-grade automation components underscores a strategic pivot toward driverless and high‑automation corridors where systems integration drives premium margins.
- Wabtec Corporation — Strong in braking and digital fleet optimisation; recent contract wins for trip-optimisation and friction products highlight the monetisation of software-enabled aftermarket services.
- Knorr-Bremse — Product portfolio depth in braking and climate systems is being reinforced via targeted acquisitions to capture compact urban-vehicle segments and bolster metro offerings.
- voestalpine, Nippon Steel, Lucchini RS, ArcelorMittal — Steel and wheelset specialists are anchoring upstream security of supply; premium rail steels and certification achievements are differentiators as high‑speed and heavy‑haul projects demand material performance and compliance.
- Thales, Hitachi Rail, Stadler — These companies reinforce the trend toward integrated systems: signaling, traction, and control subsystems are increasingly sold as programme-level solutions, reducing components-only procurement opportunities.
- CRRC and major freight-systems suppliers — Scale and cost competitiveness remain potent forces, particularly in markets where price and delivery dominate. Their footprint continues to influence global pricing dynamics and local content strategies.
- Freight-focused players (Greenbrier, Trinity, Titagarh) — Continue to capitalise on regional freight-car renewal waves and aftermarket demand, with product strategies focused on ruggedisation and cost-to-serve optimisation.
Strategic Imperatives — What Winners Will Do in 2026
Across the value chain, our report identifies a short list of near-term priorities that separate resilient strategies from tactical responses:
- Lock supply pathways for premium steels and critical subcomponents through multi-year contracts and strategic joint ventures to hedge against input-price spikes and carbon-border adjustments.
- Accelerate certification and interoperability roadmaps (ERTMS/CBTC/PNR/PTC standards) to secure bid eligibility and reduce retrofit risk — engage early with regulators and test authorities to shorten approval cycles.
- Shift commercial models toward outcome-based and lifecycle contracts that monetise digital fleet services and spare parts while smoothing revenue volatility.
- Pursue targeted M&A or alliance moves to fill capability gaps: braking and HVAC specialists, signaling integrators, and premium-material suppliers are prime acquisition targets for firms seeking upstream or services-led margin expansion.
- Design localisation strategies that explicitly account for carbon-adjusted tariffs and landed-cost sensitivities; in many jurisdictions, partial local assembly plus certified local content can be a decisive contract-winner.
- Invest in modular product architectures that enable commonality across regional fleets and reduce engineering cost per unit while improving aftermarket simplicity.
Scenario Sensitivities: How Robust Is the Base Case?
The base-case forecast — the path that produces the mid-single-digit CAGR to 2032 and the market size near USD 99.6 billion — assumes orderly regulatory implementation, gradual steel-price normalisation, and sustained investment in urban and intercity rail renewal. Our downside and upside scenarios quantify the impact of policy slippage, raw-material shocks, or accelerated automation uptake. Example sensitivities in the report include:
- Steel-price shock: a sustained material-cost shock compresses supplier margins and shortens the procurement pipeline for non‑critical upgrades; winners are those that can flex production or pass through indexed pricing.
- Regulatory acceleration: more aggressive interoperability mandates or carbon pricing disproportionately increase demand for compliant components and certified suppliers, advantaging vertically integrated vendors and early adopters.
- Technology leap: rapid roll‑out of driverless operation standards increases demand for automation and signalling components while reducing some vehicle-level weight and energy requirements — creating winners among systems integrators.
How Boards, CFOs, and Procurement Heads Should Use This Report in 2026
For executives running 2026 planning cycles, the report provides immediate tactical and strategic inputs:
- Allow CFOs to rebase five‑year capex and working‑capital models using the scenario outputs and sensitivity ranges, not single-point estimates.
- Enable procurement to redesign RFQs that embed carbon and exchange-rate clauses, clearer certification timelines, and aftermarket performance targets.
- Help strategy teams identify realistic adjacency plays (e.g., services, digital fleet management) and quantify payback under alternative market paths.
- Equip M&A teams with screening criteria and a short list of target types (steel specialists, signalling integrators, aftermarket-service providers) that would materially change position within the concentration landscape.
PW Consulting’s Worldwide Rail Components Market report blends rigorous forecasting, supplier intelligence, and playbook-style recommendations so that decisions taken in 2026 are defensible against the major downside risks in the next seven years.
Next Steps — Accessing the Full Intelligence
This release is a strategic preview. The full report contains the granular segment and regional breakdowns, product-level forecasts, supplier scorecards, and downloadable modelling tables that underpin the conclusions summarised here. For executives who need to model contract strategies, capital allocations, or acquisition targets with precision, the detailed segment datasets and supplier assessments are available on PW Consulting’s report page. Clients can also commission customised scenario workstreams and supplier diligence packages calibrated to their portfolios.
Contact PW Consulting to request the full Worldwide Rail Components Market report and bespoke advisory options that will make 2026 the year your strategy captures the next wave of value in rail components.
For detailed analysis of this topic, please visit the official page: Worldwide Rail Components Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com