

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting Forecast: Worldwide Classified Circuit Breaker Market to Surge to USD 811.96 Million by 2032 on a 6.0% CAGR

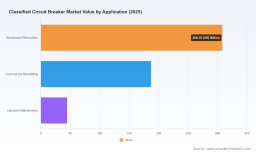
Worldwide Classified Circuit Breaker Market: Strategic Briefing for 2026 Decision-Makers
Executive summary
PW Consulting’s newest market research—Worldwide Classified Circuit Breaker Market—provides a forward-looking, decision-grade intelligence package tailored for corporate strategists, product leaders, M&A teams, and procurement heads preparing for the pivotal planning cycle of 2026. Our analysis quantifies an established market that has demonstrated recovery and steady expansion during the 2020–2025 historical window and that is expected to continue growing into the 2026–2032 forecast horizon at a compound annual growth rate of roughly 6.0% (USD, revenue in millions). The report combines rigorous market sizing and forecasting with actionable playbooks: go-to-market scenarios, supplier risk matrices, regulatory roadmaps, and M&A targets — all calibrated to support concrete near-term decisions without exposing the granular proprietary splits that drive our proprietary models.
Extracellular Matrix Products Market
Market snapshot (what you need to know right now)
-
Base year and recent scale: The sector’s baseline was established in 2025 and serves as the reference point for corporate planning in 2026.
Remote Control Model Batteries Market -
Growth trajectory: Our forecast models — built on multi-source demand indicators, supply-side constraints, and technology adoption curves — show a steady mid-single-digit CAGR through 2032, driven by renovation cycles, retrofitting activity, and increasing adoption of smart/distributed energy solutions.
Commercial Vehicle Air Disc Brakes Market -
Concentration and competitive dynamics: The market shows a profile where several global incumbents maintain significant share and influence over standards and interoperability, while aggressive regional players and OEM-compatible suppliers are accelerating product and channel plays.
What the report delivers — practical, operational content
-
Decision-ready market sizing and high-resolution forecasts aligned to a 2026 planning horizon, including scenario analyses that stress-test demand under energy-transition, supply-chain disruption, and certification-delay scenarios.
-
Go-to-market playbooks for product managers and commercial leaders: channel segmentation, pricing benchmarks, specification harmonization guidance for UL-Classified compatibility, and partner-mapping for local assembly and aftermarket distribution.
-
Procurement and supply-risk toolkit: raw-material exposure (copper, steel, polymers), lead-time sensitivities, alternative sourcing options, and supplier scorecards to prioritize resilience investments.
-
Regulatory and standards guide: focused analysis on UL-Classified interchangeability requirements and certification pathways that accelerate aftermarket acceptance while reducing liability exposure.
-
Competitive intelligence pack: concise strategic profiles, capability heatmaps, and suggested engagement strategies for incumbent and challenger OEMs — built to inform M&A screens, JV due diligence, and selective partnerships.
-
Implementation templates: business-case models, integration checklists, and a configurable KPI dashboard to track 12–36 month execution against the scenarios in the report.
Why this matters for 2026 corporate decisions
-
Timing is critical: 2026 is a transitional year for many buyers — utilities and large commercial integrators are accelerating retrofit projects tied to grid modernization and distributed energy resources. The report identifies the levers that convert portfolio exposure into near-term revenue with defensible margin expansion.
-
Interchangeability is a commercial hinge: UL-Classified interchangeability continues to lower barriers to third-party replacement breakers in residential and light-commercial loadcenters. Our strategic guidance shows how manufacturers and aftermarket players can monetize compatibility while managing warranty and liability through product, labeling, and certification strategies.
-
Supply and raw material strategy: Given the sector’s dependence on copper, steel, and specialized polymers, procurement plays an outsized role in 2026 planning. The report offers hedging strategies, demand-smoothing recommendations, and capex/redesign options to mitigate input-cost volatility.
-
Digital and service monetization: Smart breakers with remote telemetry and diagnostics are moving from proof-of-concept to procurement lists. For product and service leaders, the research outlines viable subscription and retrofit-service models that can unlock new recurring revenue streams.
Competitive landscape — what the incumbent and challenger moves mean
Our competitive analysis reviews the strategic positioning of the sector’s major participants, assessing technological breadth, channel strength, standards influence, and product interoperability moves. Key observations:
-
Eaton Corporation (Dublin): Maintains a broad portfolio of UL-Classified breakers and extensive compatibility claims with many loadcenter OEMs. Eaton’s breadth and system-level go-to-market advantage make it a critical partner or benchmark for any supplier targeting the residential aftermarket.
-
Connecticut Electric (United States): Focused on UL-Classified replacement breakers and aftermarket retrofit solutions — a practical case study in how a specialized player can capture retrofit demand through certification focus and channel intimacy.
-
Siemens (Munich): Combines global scale with integrated distribution and OEM panel business. Siemens’ classified-compatible offerings complement its broader electrification and automation portfolio, making it a strategic supplier for large commercial and institutional projects.
-
ABB (Zurich) and Schneider Electric (Rueil-Malmaison): Both reinforce strength in industrial and utility-grade breakers while leveraging their global service networks. Their strategic emphasis is on integrated systems and enterprise clients where lifecycle services and digital add-ons command premium pricing.
-
GE Vernova (United States), Mitsubishi Electric (Tokyo), LS Electric (South Korea), and Fuji Electric (Tokyo): Represent diversified, regionally strong suppliers with capability across molded-case and medium-voltage segments — relevant when planning cross-border supply and aftermarket strategies.
-
CHINT Group (China): Aggressively expanding presence via trade shows and local assembly initiatives; recent moves illustrate a playbook centered on localization to reduce logistics risk and compete on lead times in select regional markets.
Recent industry signals that matter for 2026
-
Localization and supply-chain re-shoring: Recent trade-show announcements and local assembly commitments by players such as CHINT reflect a broader trend to reduce lead times and support regional content requirements. This dynamic is shaping procurement KPIs and eligibility for large retrofit programs.
-
Digital-enabled breakers moving to commercialization: Prototypes and product showcases from regional innovators point to an acceleration of digitally-native products for industrial monitoring and arc-fault/ground-fault analytics. Vendors who can certify and scale these capabilities in 2026 stand to capture higher-margin service contracts.
-
Standards-driven interoperability: UL classification continues to be the decisive factor enabling third-party replacements in many residential and light-commercial contexts. Companies that align product roadmaps and legal/compliance frameworks to these standards will face fewer go-to-market obstacles.
Actionable strategic recommendations for executives
-
For product leaders: Prioritize certification pathways and interoperability testing to shorten sales cycles into retrofit channels. Allocate a defined budget and timeline in 2026 for UL classification workstreams and third-party compatibility labs.
-
For procurement heads: Implement a layered-sourcing strategy that blends incumbent OEMs with certified third-party suppliers and localized assemblers. Incorporate raw-material pass-through clauses and performance-based SLAs to manage cost and delivery risk.
-
For corporate development teams: Use the report’s M&A screen to identify targets that bring certification know-how, channel access, or digital-service capabilities; prioritize bolt-on deals that can be integrated within 12 months to capture retrofit cycles.
-
For sales and channel leaders: Build retrofit-focused bundles and subscription services around smart breaker offerings to differentiate from commodity replacement parts; ensure installers receive certification-aligned training and warranty clarity to reduce friction at point-of-installation.
Methodology and data integrity
Our forecast framework blends bottom-up installation data, OEM and distributor channel checks, trade-show intelligence, and materials-cost modeling. Where public disclosures are incomplete, our proprietary surveys and installer interviews provide triangulation. The report adheres to strict transparency standards: we document assumptions, sensitivity ranges, and scenario triggers so that 2026 planners can update models as new regulatory or supply events occur.
How to use this report in 2026 planning
Think of this work as both an intelligence dossier and a playbook. Use it to set 2026 budgets, prioritize R&D and certification roadmaps, re-align procurement scorecards, size M&A pipelines, and shape dealer/distributor incentive schemes. Crucially, we have withheld detailed segment-level tables and proprietary model outputs in this summary to preserve the analytical rigor of the source report; clients needing the granular datasets, breakouts by loadcenter compatibility, and supplier-level P&L proxies should consult the full publication.
Next steps
To receive the full Worldwide Classified Circuit Breaker Market report, data annexes, and custom briefing options for executive teams, visit the PW Consulting reports page or contact our industry practice. For leaders preparing investment, product, or procurement decisions in 2026, the intelligence in the complete report will materially shorten your decision cycle and reduce execution risk.
For detailed analysis of this topic, please visit the official page: Worldwide Classified Circuit Breaker Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com