

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting Forecasts 6.72% CAGR for Worldwide Surface Water Measuring Instrument Market, Signaling Strong Growth Ahead

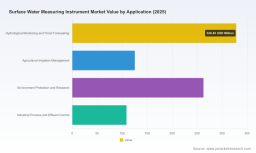
Worldwide Surface Water Measuring Instrument Market — Strategic Briefing for 2026 Decisions
PW Consulting’s latest market intelligence brief for the Worldwide Surface Water Measuring Instrument Market (base year 2025) is purpose-built to inform executive decisions in 2026. Our research synthesizes time-series market sizing, vendor benchmarking, technology roadmaps, procurement playbooks, and scenario-based forecasts across a seven-year horizon (2026–2032). The market reached an estimated USD 825.4 Million (revenue unit: Million) in 2025 and, under the central scenario in this study, is projected to expand to approximately USD 1,301.3 Million by 2032 — a compound annual growth rate (CAGR) of 6.72%. This briefing explains why that trajectory matters for capital allocation, supplier strategy, and operational readiness in 2026 without giving away the granular segmentation that forms the core IP of the full report.
Worldwide Stream Analytics Software Market
Why this report matters for 2026
-
Budget and procurement cycles: Many public agencies and water utilities will finalize multi-year CAPEX and service contracts in 2026. Our forward-looking sizing and price/technology trend lines enable CFOs and procurement leads to set realistic budgets and contract lengths that align with expected component and device cost evolution.
Worldwide Cloud Core Financial Management Suites Market -
Risk and resilience planning: Accelerating extreme-weather events are increasing demand for real-time surface water monitoring solutions. The report quantifies the commercial implications of that demand and links technology choices (e.g., radar FMCW sensors, telemetry, edge analytics) to operational resilience outcomes.
Polymeric Positive Temperature Coefficient Device Market -
Vendor selection and consolidation: The competitive landscape is moderate in concentration — top-three vendors account for roughly one-third of market value, with the top-five approaching about half. That structure has implications for negotiation leverage, strategic partnerships, and M&A watchfulness in 2026.
-
Regulatory alignment and compliance: Device accuracy standards and monitoring guidelines (e.g., those influencing non-contact radar sensor acceptance) are shifting procurement acceptance criteria. The report translates regulatory nuance into procurement checklists and acceptance test protocols.
What the report contains — practical, operational, deployable
-
Market sizing and forecast model: A transparent, auditable model that traces historic performance (2020–2025) into a base case and three alternate scenarios through 2032. The model is delivered with configurable levers so corporate strategists can stress-test outcomes under different adoption rates and price curves.
-
Technology roadmap and cost curves: Comparative profiles for sensing modalities (e.g., non-contact radar, pressure transducers, electromagnetic flow meters, multiparameter quality probes), including maturity, expected unit cost trajectory, maintenance cadence, and suitability by deployment archetype.
-
Vendor benchmarking and procurement templates: Scorecards and RFP language that translate performance requirements into testable vendor commitments (accuracy, drift, telemetry protocols, MTTR, spare-parts lead times, warranty terms).
-
Deployment playbooks and case studies: Site selection frameworks, sensor siting checklists, telemetry network architectures, and data governance patterns drawn from real-world deployments to reduce time-to-value and avoid common field failures.
-
Supply chain and component risk analysis: Assessment of critical materials (e.g., corrosion-resistant housings such as titanium and 316L stainless steel), single-source exposures, and mitigation actions including dual-sourcing, safety stock, and contractual clauses for lead-time guarantees.
-
Commercial scenarios and TCO models: Total cost of ownership models comparing CAPEX, OPEX, service contracts, calibration schedules, and data costs for fixed versus telemetry-enabled portfolios.
-
Action-oriented recommendations: A prioritized roadmap of 12–18 month actions for equipment OEMs, system integrators, utilities, and government agencies to capture near-term upside and minimize technology obsolescence risk.
Key strategic implications for 2026
-
Shift to telemetry and IoT-enabled sensing: Real-time monitoring and edge analytics are no longer experimental. Investments in IoT gateways, secure telemetry, and cloud-native ingest pipelines yield outsized operational benefits — our scenario analysis shows faster payback where telemetry reduces manual site visits and accelerates incident response.
-
Procure for accuracy and maintainability, not just headline price: The regulatory environment and growing expectations for high-frequency data mean that device accuracy (e.g., modern FMCW radar performance) and low-maintenance designs strongly influence lifecycle cost. Contract language should reflect calibration intervals, drift tolerances, and acceptance criteria.
-
Design for heterogeneity: Most long-term monitoring networks will be heterogeneous. Interoperability, standardized telemetry protocols, and middleware that normalizes datasets are essential to avoid vendor lock-in and to enable cross-agency data sharing.
-
Prioritize supply-chain resilience: Critical housings and sensor components use corrosion-resistant materials. Given global sourcing constraints for specialty alloys, 2026 procurement rounds should bake in longer lead times and alternative sourcing plans.
Competitive landscape — who to watch and how to position
The market is populated by specialized instrumentation firms, systems integrators, and diversified water technology players. Our vendor oversight highlights tactical strengths and practical selection criteria for each profile. Below are condensed strategic notes on key players included in the study:
-
Campbell Scientific (Logan, UT, USA) — Strengths: robust dataloggers, proven long-duration unattended systems, and adherence to Office of Surface Water accuracy paradigms. Strategic advice: leverage Campbell for long-life installations requiring rigorous QA/QC and regulatory-compatible accuracy; insist on datalogger firmware transparency for data lineage.
-
Solinst Canada Ltd. (Georgetown, ON, Canada) — Strengths: quality field instruments and an expanded water quality portfolio following their 2025 acquisition of Eureka Water Probes. Strategic advice: evaluate Solinst for integrated level and water-quality projects where single-vendor simplicity reduces integration overhead; validate post-acquisition roadmap for sensor interoperability.
-
Seametrics (TASI Flow Group) (Kent, WA, USA) — Strengths: practical flow-meter technologies and submersible sensors with strong environmental application fit. Strategic advice: choose Seametrics for flow-centric sites and where field-replaceability is a priority.
-
OTT HydroMet (Kempten, Germany) — Strengths: hydrological instrumentation and integrated flood systems, amplified by 2025 product launches including an 80 GHz FMCW radar sensor and a combined IoT flood monitoring system. Strategic advice: OTT’s recent product set should be evaluated where high-precision, low-maintenance non-contact sensing is mission-critical; test integration with incumbent SCADA/telemetry ecosystems.
-
In-Situ Inc. (Fort Collins, CO, USA) — Strengths: coastal and estuarine monitoring solutions with attention to harmful algal bloom (HAB) monitoring. Strategic advice: prioritize In-Situ for coastal projects and HAB surveillance where domain-specific probes and analysis kits are advantageous.
-
Badger Meter (Milwaukee, WI, USA) — Strengths: municipal-grade flow and level monitoring, and integrated quality instrumentation. Strategic advice: target Badger Meter for municipal or utility rollouts with strong service infrastructure expectations.
-
Xylem / YSI / Global Water (Washington, DC, USA) — Strengths: broad multiparameter instrumentation and established environmental product lines. Strategic advice: leverage Xylem brands where multi-parameter consistency and vendor reach are procurement priorities.
-
Stevens Water Monitoring Systems (Portland, OR, USA) — Strengths: legacy data-acquisition expertise and hydrology-focused systems. Strategic advice: Stevens is a strong candidate for complex hydrology projects requiring deep domain integration.
-
Aquaread Ltd. (Broadstairs, Kent, UK) — Strengths: multi-parameter water quality testers and compact loggers. Strategic advice: consider Aquaread for modular water-quality deployments that require portable or distributed sensing.
-
KISTERS (Aachen, Germany) — Strengths: sensor-to-cloud offerings and IoT-enabled hydrology solutions. Strategic advice: evaluate KISTERS where rapid data normalization and analytics are required across heterogeneous sensor fleets.
-
Heron Instruments Inc. (Dundas, ON, Canada) — Strengths: premium level and CTL (conductivity/temperature/level) meters. Strategic advice: select Heron for critical monitoring points where premium sensor accuracy and field ruggedness are decisive.
Technology, procurement and operations playbook for 2026
-
Define acceptance criteria aligned to regulatory norms and operational objectives: accuracy, sampling frequency, telemetry latency, and environmental tolerance.
-
Run a two-stage procurement: technical pre-qualification (lab and bench tests) followed by a short field pilot to validate maintainability and data quality.
-
Mandate telemetry standards and open APIs in contracts to avoid lock-in; require end-to-end data lineage and calibration logs.
-
Price in lifecycle costs: insist on total cost of ownership estimates that include calibration, spare-parts, and recurring telemetry/cloud costs.
-
Harden supply chains: pre-qualify alternate component suppliers for critical alloys and create staged replenishment plans for high-priority field sites.
Why purchase the full PW Consulting report
The full report contains the detailed segmentation, disaggregated forecasting, vendor scorecards, and downloadable financial model that underpin the strategic recommendations in this briefing. PW Consulting’s deliverables are structured to be directly usable by procurement teams, engineering leads, and corporate strategy groups — from templated RFP language to calibrated TCO calculators and scenario-ready forecasts. The “trailer” above is designed to show the analytical depth while reserving the proprietary split-level detail that drives specific contract decisions and competitive stratagems.
For procurement leads, asset managers, and technology officers preparing 2026 capital plans, this report converts market signal into executable steps. To access the full market segmentation, vendor appendices, and the interactive forecasting workbook, consult the PW Consulting report page and download the executive package.
For detailed analysis of this topic, please visit the official page: Worldwide Surface Water Measuring Instrument Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com