

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting Report: Worldwide Financial Services App Market to Grow from USD 165.2 Billion in 2025 to USD 400.84 Billion by 2032 at 13.5% CAGR

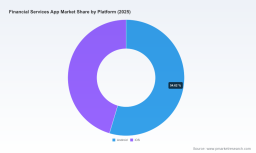
Worldwide Financial Services App Market — 2026 Strategic Brief
PW Consulting’s latest market study, Worldwide Financial Services App Market (base year 2025, forecast period 2026–2032), equips executives with an action-oriented, evidence-based view of the mobile financial services landscape as they set priorities for 2026. The market has experienced sustained expansion—growing from USD 84.12 Billion in 2020 to USD 165.2 Billion in 2025—and our projections see this momentum continuing toward a sizeable USD 400.84 Billion by 2032, reflecting a compound annual growth rate (CAGR) of 13.5% across the forecast window. This narrative summarizes the strategic implications of those trends, highlights competitive dynamics, and outlines the operational levers that should shape boardroom decisions this year. For the full datasets, regional and service-level breakdowns, and vendor scorecards, consult the complete report.
iSIM Chip Market
Why this report matters for 2026 decision-making
-
Clarity in a high-velocity market: Financial services apps are no longer a peripheral channel; they are the primary customer interface for broad swathes of banking, payments, insurance, lending, and wealth services. With market value nearly doubling in five years and a sustained double-digit CAGR ahead, 2026 is a pivotal year for firms that must choose between incremental product improvements and platform-scale transformation.
Worldwide Injectable Cement Market -
Risk and regulation converge: New regulatory regimes—regional digital-operational resilience requirements, consumer data portability mandates, and localized data processing laws—are shifting the cost and timing of digital initiatives. Our report synthesizes the commercial consequences of these rules and provides governance templates that fast-track compliance without sacrificing product velocity.
Laboratory Monocular Microscopes Market -
Infrastructure economics are strategic: Rising energy costs and evolving cloud economics materially affect TCO for app platforms. The report models multiple hosting and architectural configurations (edge, cloud, hybrid) to compare performance, resilience, and cost over a seven-year horizon.
What’s in the report — practical, decision-ready content
-
Forecast engine and scenario maps: A transparent forecasting model calibrated to historical data (2020–2025) and multiple macro scenarios for 2026–2032 that quantify upside and downside outcomes under varying adoption, regulation, and macroeconomic assumptions.
-
Go-to-market playbooks: Actionable roadmaps for incumbents, challengers, and platform players—detailing product roadmaps, partnership architectures, pricing/monetization levers, and pilot-to-scale templates that reduce time-to-value.
-
Vendor selection toolkit: A vendor RFP framework, scoring matrix, and migration checklist aligned to enterprise risk tolerances and cost targets—designed to shorten procurement cycles and avoid costly rework.
-
Operational playbooks: Implementation sprints for embedding payments, lending, and wealth features in apps; security and resilience blueprints mapped to prevailing regulations; and AI/ML adoption frameworks for fraud, personalization, and credit underwriting.
-
Executive dashboards and KPIs: A concise set of leading indicators and financial metrics tailored for executive oversight—enabling boards and operating committees to track customer engagement, economic value, and regulatory compliance in near-real time.
Competitive landscape — who matters and why
The market remains fragmented: top-three and top-five players account for a minority share of total industry revenue, underlining significant opportunity for scale, differentiated propositions, and regional champions. Our competitive chapter offers deep, comparable profiles of the companies shaping the sector—covering product scope, partnership ecosystems, go-to-market models, recent strategic moves, and capability gaps.
-
Challenger super apps (example): Global neo-banks and super apps have accelerated user acquisition through embedded finance and cross-border features. Their advantage is speed of experimentation and customer-centric bundles; their constraint is regulatory and liability complexity as they scale into banking functions.
-
Payment and infrastructure specialists: Payment networks and infrastructure firms are increasingly front-of-wallet for merchants and platforms by offering SDKs, tokenization, and seamless settlement rails. Their strategic play is to monetize platform plumbing while partnering or integrating with consumer-facing experiences.
-
Core banking and cloud vendors: Providers of core banking and cloud-native suites position themselves as enablers for incumbents seeking rapid modernization. They compete on integration footprints, SaaS delivery, and data-residency capabilities.
Representative firms we profile include (but are not limited to) Revolut, PayPal, Stripe, FIS, Fiserv, Block (Cash App), Temenos, nCino, Mastercard, Visa, Alipay (Ant Group), WeChat Pay (Tencent), Adyen, Klarna, and SoFi. For each, the report distills strategic posture, recent product developments, partnership maps, and a concise risk/opportunity assessment designed to inform partnership, investment, or competitive response decisions.
Recent developments shaping near-term strategy
-
Advanced fraud and network intelligence: Enhancements in network-level fraud tools are raising the bar for detection effectiveness in real time. Firms must reassess fraud budgets, data-sharing agreements, and incident response playbooks to preserve margins while protecting customers.
-
Digital asset integration: Tokenized deposits, stablecoin pilots, and institutional-grade rails are moving from experimentation to early commercialization. Partnerships between core processors and digital-asset platforms signal that 2026 will be a year for controlled rollouts rather than purely exploratory proofs-of-concept.
-
Real-time payments expansion: RTP and instant payment volumes have accelerated; application providers that integrate these rails can dramatically improve conversion, reduce settlement friction, and unlock new monetization around request-for-payment flows.
-
Regulatory milestones: New operational resilience and consumer-data-rights regimes demand code-level controls, auditability, and enhanced API governance. These are not optional compliance add-ons—regulatory expectations are redesigning product backlogs and vendor selection criteria.
Strategic implications for 2026 — priorities for executives
-
Reframe product strategy around composability: Adopt modular architectures that allow rapid composition of payments, wallets, credit, and wealth features via APIs and SDKs. This reduces time-to-market and isolates compliance boundaries.
-
Institutionalize data sovereignty and portability: Implement data partitioning and localized processing where required while centralizing analytics through privacy-preserving techniques (e.g., federated learning, synthetic datasets) to retain product intelligence.
-
Reprice for resilience: Build energy and infrastructure costs into unit economics; evaluate multi-cloud and edge strategies to mitigate concentration risk and reduce long-run TCO.
-
Elevate partnerships to board-level oversight: Select partners not just on features but on governance, auditability, and financial stability. The right partner can be a force multiplier; the wrong one can be an existential risk.
-
Operationalize regulatory readiness: Move from ad hoc compliance projects to continuous controls monitoring, embedding DORA-aligned and consumer-data-rights controls into CICD pipelines and vendor contracts.
-
Monetize trust: With growing consumer sensitivity to privacy and security, firms that can credibly demonstrate superior controls and transparent data use will unlock premium monetization pathways.
How to use the report
-
CEOs and boards: Use the executive summary and scenario maps to stress-test strategic plans and capital allocation decisions under alternative regulatory and macroeconomic outcomes.
-
Product and technology leaders: Adopt the vendor selection toolkit and implementation playbooks to accelerate modernization while preserving compliance and uptime SLAs.
-
M&A and corporate development: Leverage the market model and vendor profiles to size adjacencies, identify attractive acquisition targets, and model integration economics.
Final note — what’s withheld here and where to go next
This brief presents the strategic contours and executive-ready recommendations from PW Consulting’s Worldwide Financial Services App Market study. In keeping with our “trailer” approach, detailed segment and regional breakdowns, platform-level tables, full financials, and the comparative vendor scorecards are not reproduced here. Those datasets—along with raw model files, scenario assumptions, and implementation templates—are available in the full report package.
To download full forecasts, regional and service splits, vendor matrices, and the procurement-ready RFP attachments, visit the PW Consulting report page or contact our market intelligence desk for an executive briefing. The choices made in 2026 will determine who captures the next decade’s value in mobile financial services—this report tells you where the value pools are and how to move decisively to capture them.
For detailed analysis of this topic, please visit the official page: Worldwide Financial Services App Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com