

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Zinc L‑carnosine Market Poised to Expand at a 6.15% CAGR — New Report Flags Strong Growth Ahead

Zinc L‑Carnosine Market — Strategic Imperatives for 2026: PW Consulting Industry Brief
Executive summary
The Zinc L‑carnosine market has moved from niche therapeutic origins toward a commercially diverse ecosystem spanning pharmaceuticals, nutraceuticals and specialty nutrition. PW Consulting’s new Zinc L‑carnosine Market report (base year 2025) models a resilient expansion pathway: global revenues have grown materially since 2020 and PW forecasts sustained mid‑single‑digit growth through 2032 at a compound annual growth rate (CAGR) of 6.15% (2026–2032). Measured in USD (Million), the market reached a meaningful scale by 2025 and is projected to expand further by 2032 driven by regulatory evolution, increasing clinical interest beyond traditional gastroenterology, and broader adoption in dietary supplements and oral care applications.
Polysulfone Tube Market
Why this matters to corporate decision‑makers in 2026
-
Timing of strategic moves is now a competitive differentiator. With steady CAGR dynamics and a clear growth runway through 2032, 2026 is the inflection point for converting exploratory initiatives into scale bets—whether that is upstream capacity investment, securing supply agreements, or locking in regulatory positioning for finished products.
Silicon Carbide Column Ultrafiltration Membrane Market -
Regulatory and classification ambiguity creates both risk and optionality. Zinc L‑carnosine maintains approved drug status in several Asian markets while it is primarily a dietary ingredient in many Western markets. This dual identity enables differentiated go‑to‑market strategies—but also demands a bespoke regulatory roadmap for each commercial ambition (drug, novel food, or supplement).
Marine Canvas Fabric Market -
Supply chain resilience is strategic. API‑grade manufacturing must meet growing expectations for GMP compliance and filings (USDMF, JDMF, WHO‑GMP) to support both regulated pharmaceuticals and premium nutraceutical lines. Corporates that secure multi‑source, certified supply now will avoid costly disruptions as demand grows.
-
Clinical momentum is creating new product windows. Recent scientific reviews and bioequivalence activity signal interest in therapeutic extensions beyond peptic ulcer therapy. Firms that invest in targeted clinical evidence, PK/safety comparators, and branded intellectual property will convert scientific interest into differentiated commercial propositions.
Market trajectory and interpretation
From 2020 through 2025, the market demonstrated durable expansion as manufacturers scaled production and regulatory acceptances in Asia matured. Our forecast to 2032 incorporates conservative uptake scenarios across pharmaceutical, dietary supplement and oral care channels and confirms a steady growth path: the market base measured in 2025 provides a launching pad for mid‑single‑digit CAGR through the forecast period (6.15% CAGR for 2026–2032). For executive teams this means predictable topline growth with opportunities for margin expansion where value can be captured via branded formulations, premium certifications, or proprietary clinical data.
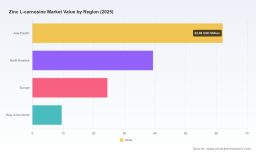
Importantly, while the macro trajectory is robust, growth is not uniform—market segmentation, regulatory status by jurisdiction, and application mix create pockets of premium pricing and commoditization risk. PW Consulting’s full report contains granular scenarios mapping these pockets to commercial levers; the headline narrative here intentionally omits detailed regional and application breakdowns to preserve competitive value and direct stakeholders to the full dataset.
Competitive landscape — strategic takeaways
-
Originator and branded leadership: The market retains a recognizable originator presence with companies that developed clinically used formulations and maintain branded assets. These organizations offer premium positioning (branded reference products and therapeutic dossiers) that remain valuable for both prescribers and regulators.
-
Manufacturing depth across geographies: A mix of long‑standing Japanese originators and an expanding roster of Indian and Chinese API manufacturers has created a bifurcated supply base—one side focused on branded, regulated outputs and the other delivering cost‑competitive API volumes. Recent regulatory filings from several suppliers demonstrate the intent to serve regulated markets globally.
-
Concentration and competitive dynamics: Market concentration is moderate: the top three and top five suppliers represent material portions of industry supply (PW analysis indicates the three‑company concentration and a broader five‑company band are significant). This structure favors coordinated capacity planning among buyers and selective consolidation plays among suppliers seeking scale and regulatory credentials.
-
Regulatory filings as strategic signals: Active USDMF and JDMF submissions, together with reference product availability for bioequivalence studies, are early indicators of supplier intent to enter high‑barrier markets. Buyers should monitor these filings to anticipate changes in competitive sourcing, quality expectations and pricing.
Profiles and strategic postures of key players
PW Consulting’s industry mapping differentiates players by capability: branded originators with therapeutic dossiers and certifications; quality‑focused API manufacturers with regulatory filings; and bulk suppliers that compete primarily on cost and logistical reach. Examples of strategic positioning observed in market activity:
-
Originator companies retain leverage through clinical heritage and branded assets, using regulatory filings (e.g., novel food registrations) to open new markets while protecting therapeutic channels.
-
Large API producers in India and China are pursuing quality credentials—WHO‑GMP, USDMF/JDMF filings—to shift from high‑volume suppliers to preferred vendors for finished formulations in regulated jurisdictions.
-
Specialist ingredient suppliers in Europe and the UK position technical specifications and ancillary documentation (CoA, MSDS) to support formulators in supplements and veterinary applications, enabling route‑to‑market flexibility for their customers.
Regulatory and scientific developments to watch in 2026
-
Classification shifts in major markets: Novel food registrations and similar reclassification efforts will materially change market access for finished products. Companies should prepare evidence dossiers tailored to novel food pathways where appropriate.
-
Clinical repurposing signals: Recent scientific reviews that examine broader therapeutic potential (including neuromodulatory and systemic indications) increase the value of targeted R&D and investigator‑led studies. Firms that create focused clinical programs will strengthen payer and prescriber acceptance beyond gastrointestinal indications.
-
Quality and documentation expectations: The presence (or absence) of active USDMF/JDMF/WHO‑GMP filings will determine which suppliers can support mainstream pharma conversions. Buyers need granular supplier audits and contingency plans keyed to certification changes.
Actionable recommendations for 2026 planning
-
Adopt a tiered supplier strategy: Categorize suppliers by regulatory readiness (e.g., DMF/JDMF/WHO‑GMP status), and secure at least two qualified sources for any program targeting regulated markets. Include audit triggers tied to certification milestones.
-
Invest in regulatory investments where it matters: If your commercial strategy targets Europe or regulated pharmaceutical markets, plan and fund targeted filings (novel food dossiers, or dossier support for marketing authorization) in 2026 to capture first‑mover advantages.
-
Prioritize clinical evidence aligned to commercial goals: For companies pursuing labelled therapeutic claims, prioritize bioequivalence and safety/PK data using established reference products. For supplement positioning, invest in human proof‑of‑benefit studies that resonate with consumers and channels.
-
Design M&A and partnership screens around certification and IP: Acquisition targets that bring JDMF/USDMF filings, proven reference products or unique formulations accelerate market entry and reduce time‑to‑market risk.
-
Model price curves under certification stress scenarios: Use scenario stress‑testing to anticipate margin compression if major suppliers scale up while lacking premium certifications—or, conversely, to estimate upside if supply consolidates under certified producers.
What the full PW Consulting report delivers
The full Zinc L‑carnosine market report is an operational toolkit built for strategic and commercial teams. Deliverables include:
-
Detailed market model (historical 2020–2025, forecast 2026–2032) with scenario toggles and sensitivity analysis to test pricing, penetration and regulatory outcomes.
-
Segmented demand drivers and commercial implications for pharmaceutical, nutraceutical and oral care channels (note: granular segmentation tables and region/application shares are included exclusively in the paid dossier).
-
Supplier intelligence dossier: regulatory filing maps (USDMF/JDMF/WHO‑GMP), capability matrices, audit checklists and contingency sourcing playbooks.
-
Regulatory pathway blueprints for novel food, supplement and drug routes by jurisdiction, with recommended evidence packages and timeline estimates.
-
Clinical and IP landscape: bibliography of recent studies, patent cluster analysis and playbooks for brand‑building through clinical differentiation.
Conclusion — positioning for advantage in 2026
Zinc L‑carnosine is no longer a purely niche therapeutic ingredient—its market evolution combines predictable macro growth with differentiated pockets of premium value tied to regulatory status and clinical evidence. For 2026, firms must decide whether to play the premium branded route (invest in clinical and regulatory dossiers), secure supply and cost leadership, or pursue hybrid strategies that combine regional regulatory plays with global supplement distribution.
PW Consulting’s Zinc L‑carnosine Market report is designed for executives who need to convert macro visibility into actionable plans. To access the complete datasets, supplier scorecards, and executable playbooks that support board‑level decisions, please visit the PW Consulting report page and download the full report and model package. Note: this brief intentionally omits segmented region/application figures to preserve the commercial value of the complete research offering.
For detailed analysis of this topic, please visit the official page: Zinc L-carnosine Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com