

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Worldwide Multi‑Gigabit Switches Market Poised to Expand at 18.52% CAGR Through 2032

Worldwide Multi-Gigabit Switches Market — Strategic Imperatives for 2026: A PW Consulting Report Preview
Executive snapshot
Rapid enterprise digitization, the proliferation of Wi‑Fi 7 and high-density edge devices, and accelerating cloud and hybrid architectures have driven sustained growth in the worldwide multi‑gigabit switches market. Our analysis uses 2025 as the base year and projects the market through a seven‑year forecast window (2026–2032). The market expanded from an estimated USD 2,840.5 million in 2020 to USD 7,280.0 million in 2025, and PW Consulting projects a continuation of that momentum into 2026 and beyond — with a rollover to roughly USD 8,886.7 million in 2026 and a long‑term trajectory to approximately USD 23,915.1 million by 2032. That outlook reflects a compound annual growth rate (CAGR) of 18.52% across the forecast period.
Hydraulic/Pneumatic Rotary Joints Market
Why this preview matters for 2026 decision‑makers
-
Timing and procurement: Rapid growth and technology refresh cycles mean procurement windows in 2026 will determine cost, capabilities and upgrade paths for networks through 2028–2030.
Total and Permanent Disability (TPD) Insurance Market -
Architecture choices: Multi‑gigabit switches are increasingly the fulcrum between high‑density Wi‑Fi access, PoE‑driven edge devices, and higher‑speed uplinks to cloud and data center fabrics. Strategic choices made in 2026 will lock in platform and vendor dependencies.
Worldwide Dementia Care APP Market -
Cost of ownership: Energy, construction and fiber economics are re‑shaping TCO. Data center power accounts for a material share of operating expense, and rising build costs and fiber deployment expectations will affect total program budgets.
-
Competitive positioning: Vendor consolidation and product differentiation are intensifying. Buyers must balance scale, feature breadth and openness to avoid lock‑in while preserving operational simplicity.
What PW Consulting’s full report delivers (practical, purchase‑ready insights)
-
Proven market sizing and scenario forecasts — with a clear base year (2025), a detailed historical review (2020–2025), and scenario modeling across 2026–2032 that quantifies upside and downside paths driven by adoption rates, enterprise refresh cycles and technology inflection points.
-
Actionable TCO and lifecycle models — built to be used in procurement meetings, financial planning and capex/opex tradeoff analyses. These models integrate power consumption, expected device lifetimes, uplink strategy and projected energy cost inflation.
-
Vendor scorecards and decision matrices — comparative frameworks that translate product capability into procurement guidance (fit‑for‑purpose, scalability, manageability, security posture and total cost of ownership), including red/amber/green triggers for shortlisting.
-
Deployment playbooks — migration roadmaps for campus, branch and edge environments with RFP language, interoperability checkpoints, and staged upgrade strategies designed to minimize business disruption.
-
Use‑case driven adoption maps — templates for prioritizing multi‑gig investments by customer persona (enterprise, service provider, data center and industrial/IoT) and by technical trigger (Wi‑Fi 7 rollout, PoE++ expansion, 10G uplink densification).
-
Tools and templates — editable RFPs, TCO calculators, sample BOMs, and a scenario generator you can run with your own inputs (traffic growth, power tariffs, expected device counts).
Competitive landscape — who matters and why (strategic positioning)
The competitive picture combines established incumbents focused on enterprise and data center performance with nimble vendors targeting SMB, prosumer and industrial niches. Market concentration is meaningful: the three largest vendors collectively control a majority of the market, and the top five account for nearly three‑quarters — a dynamic that shapes pricing leverage, channel strategies and enterprise procurement behavior.
-
Cisco Systems — The dominant enterprise and campus player with broad platform coverage and deep lifecycle services; best positioned for large, managed campus and hybrid data center deployments.
-
Arista Networks — A high‑performance, data‑center and cloud‑oriented vendor whose strength in 10G+ switching makes it a preferred choice where scale and low latency matter.
-
Hewlett Packard Enterprise (Aruba) — Competes strongly in campus and enterprise campus fabrics with integrated wired/wireless management and cloud management options.
-
Juniper Networks — Focused on service provider and enterprise fabrics, offering platforms that balance programmability and scale.
-
NETGEAR, TP‑Link, Ubiquiti — These vendors lead value and channel‑centric segments, delivering competitive price/performance for SMBs, prosumers and distributed edge sites.
-
QNAP, D‑Link, EnGenius, TRENDnet and specialized vendors — Targeted propositions for NAS‑integrated networks, surveillance/Wi‑Fi 7 use cases, hardened industrial environments and PoE‑heavy deployments.
-
Industrial/hardened vendors (e.g., Omnitron, Lantronix, PLANET) — Focus on environmental ruggedness, industrial PoE and protocol support for IIoT users.
Recent vendor moves and what they indicate
-
New product introductions during 2025 underscore two clear trends: higher‑power PoE and multi‑gig per‑port options tailored to Wi‑Fi 7 and AI‑driven surveillance, and low‑cost 5–10G edge switches that accelerate adoption at the SMB level.
-
These product releases also reveal an intensifying bifurcation: high‑end platforms designed for scale and programmability versus cost‑optimized appliances aimed at rapid edge refresh cycles.
Macro headwinds and tailwinds that will shape 2026 outcomes
-
Supply and input costs: Fiber deployment expectations and certain raw material inputs are showing renewed upward pressure in early 2026, which can extend project timelines or increase first‑mile access costs.
-
Energy and operational expense: Electricity remains a dominant cost line for data center operators, forcing a re‑examination of power budgets and device energy efficiency as a competitive procurement criterion.
-
Construction economics: Average shell‑and‑core data center construction costs have ticked higher year‑over‑year, adding strategic friction to large on‑prem expansion plans and increasing the relative attractiveness of cloud‑native and colocation strategies.
-
Regulatory environment: Changes in net neutrality and other policy dynamics can alter service provider product strategies, pricing, and willingness to invest in certain market segments.
Strategic recommendations for 2026 (what to do next)
-
Review and rationalize your portfolio entry points: Apply the vendor scorecards in this report to trim single‑vendor dependencies and identify alternative suppliers for critical edge and PoE functions.
-
Incorporate energy and build cost scenarios into procurement: Require suppliers to publish energy‑use metrics and support cross‑supplier TCO comparisons as part of RFP responses.
-
Stage deployments with upgrade paths: Favor modular, field‑upgradeable platforms that allow incremental port‑speed upgrades rather than forklift replacements.
-
Run controlled pilots for Wi‑Fi 7 and PoE++ use cases: Use short, measurable pilots to validate switch performance in real traffic conditions before enterprise‑wide rollouts.
-
Negotiate ecosystem commitments: Seek multi‑year support, interoperability guarantees and transparent roadmap commitments from shortlisted vendors to reduce upgrade risk.
-
Fast‑track industrial and edge use‑cases where latency and environmental resilience matter — early specialization can secure competitive advantage in IIoT segments.
Decision‑support assets included in the full report
-
Editable TCO and scenario models to run with your in‑house assumptions.
-
Vendor scorecards and shortlist templates you can apply immediately to vendor RFP processes.
-
Deployment checklists, RFP language and migration roadmaps designed to shorten procurement cycles and reduce integration risk.
Final note — why PW Consulting’s preview is intentionally selective
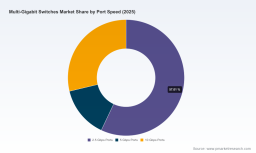
This preview is designed as a strategic “trailer”: it highlights the drivers, vendor dynamics and decision frameworks that will matter in 2026, while preserving the granular segmentation datasets and proprietary vendor scoring engines contained in the full report. Those detailed datasets — including regional, port‑speed and deployment splits, and the underlying excel models used to generate scenario outputs — are available in the complete study and are intended for enterprise planning teams and vendor negotiation working groups.
How to access the full intelligence
For procurement teams, CIO offices and investor strategists preparing 2026 budgets and network roadmaps, the PW Consulting Worldwide Multi‑Gigabit Switches Market report provides the practical tools and empirical backing to make confident choices. Visit our report page to access the full market dataset, model files and enterprise licensing options.
PW Consulting — Equipping technology leaders with market foresight and the operational tools to convert insight into decisive action.
For detailed analysis of this topic, please visit the official page: Worldwide Multi-Gigabit Switches Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com