

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting Forecast: Industrial-Grade Borated Polyethylene Market Set to Reach USD 309.07 Million by 2032

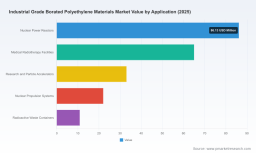
Industrial Grade Borated Polyethylene Materials Market: Strategic Imperatives for 2026
PW Consulting’s latest market research brief on Industrial Grade Borated Polyethylene Materials delivers an actionable intelligence package designed to orient executive decision-making through 2026 and beyond. Built on a transparent methodology and multiyear trend analysis, the study quantifies the market’s current scale and near-term trajectory while exposing the operational, regulatory, and supply-side dynamics that will determine winners and laggards in this specialized polymer niche.
Worldwide Portable Audio Amplifiers Market
Market at a Glance: Size, Growth and Structural Signals
Our analysis identifies the borated polyethylene market as a modest but steadily expanding industrial specialty market. The report’s base-year assessment (2025) positions the global market in the low hundreds of millions (USD), and a compound annual growth rate of approximately 5.18% drives the market to a materially larger footprint by the end of the 2026–2032 forecast horizon. The trajectory is underpinned by sustained demand from nuclear-related end markets—reactor construction and maintenance, spent fuel storage systems, medical radiotherapy suites, and accelerator facilities—as well as emerging uses in defense, transport security, and aerospace platforms.
Tourmaline Stone Market
Market structure is neither atomized nor highly concentrated. The top three suppliers together account for under forty percent of market value, while the top five firms capture just over half of the market. This mid-range concentration creates room for differentiated plays—regional specialists, technical innovators, and vertically integrated suppliers can all find defensible positions if they align product, certification, and service models with buyer needs.
High Temperature Resistant Ceramic Fiber Blanket Market
Why This Matters to Strategic Decision-Makers in 2026
- Procurement and cost planning: Polymers with boron loading are materials with specific performance trade-offs (neutron attenuation vs. hydrogen density, long-term aging considerations). Buyers must incorporate lifecycle performance and certification costs into procurement forecasts rather than treating sheets or blocks as interchangeable commodities.
- Regulatory and compliance risk: Military and civil nuclear applications require compliance with recognized specifications and standards. Firms that can document conformity to these specs and embed traceable QA/QC processes will enjoy a commercial premium and lower contractual friction.
- Supply resilience: The market remains sensitive to feedstock availability, custom formulation lead-times, and manufacturing capacity for large-format sheets and machined components. Strategic sourcing—dual sourcing and forward stocking—reduces program delivery risk.
What the PW Consulting Report Provides (Practical Tools for 2026)
This report is intentionally designed as an operational playbook for commercial, procurement, and technical teams. What readers will find inside:
- Transparent market-sizing and demand-modeling routines that reconcile historical uptake (2020–2025) with scenario-driven forecasts through 2032.
- Supply-chain mapping and a component-level cost curve that isolates the key cost drivers: masterbatch/boron feedstock, polymer resin economics, sheet extrusion and finishing, and value-added machining/fabrication.
- Supplier scorecards and capability matrices—assessing production scale, in-house machining, quality certifications (including pertinent military/nuclear standards), and geographic service footprints—presented to facilitate shortlist creation without disclosing confidential customer contracts.
- Case studies that convert technical requirements into procurement specifications and acceptance tests for reactor vaults, radiotherapy rooms, and research accelerators—showing how OEMs and integrators have structured warranties and acceptance criteria.
- Investment prioritization templates and M&A screening heuristics that let corporate strategists size the payoff of adding borated-polyethylene capability, partnering with regional fabricators, or acquiring specialty compounders.
- Regulatory & compliance checklists and a practical guide for qualification testing—helpful for product managers converting R&D formulations into certified production runs.
Competitive Landscape: Who’s Competing and How
The market is populated by a mix of long-established polymer fabricators, specialty shielding manufacturers, and increasingly active international producers. Across the competitive set, four strategic archetypes emerge:
- Heritage polymer fabricators with defense/nuclear certifications: These firms leverage long-standing process know-how and recognized military or nuclear specifications to supply large institutional buyers. Their value proposition centers on traceability, certifiable formulations, and capacity to meet large-format or bespoke orders.
- Shielding-focused specialists: Smaller, highly nimble companies offer end-to-end solutions—material supply, CNC/waterjet cutting, and custom assembly for vaults, doors, and transport containers. They frequently pair product supply with installation services and integration into regulatory acceptance packages.
- High-boron compounders: Producers that can supply high-concentration boron formulations target niche criticality or weight-sensitive applications where neutron capture per unit volume is at a premium. These players typically capture premium pricing but face tighter raw-material and processing constraints.
- Low-cost regional producers: Emerging manufacturers in lower-cost geographies compete on price and customizability, and are expanding their footprint by offering multiple boron-load options and flexible order sizes.
Representative firms illustrate these archetypes: established North American sheet producers that emphasize military specification compliance and machining capacity; specialist shield fabricators that combine product and service; and international compounders offering broad boron-content options and competitive lead times. Recent market activity—partnerships with national nuclear initiatives and targeted trade-show participation—signals an intensifying commercial focus on both civil and defense channels.
Key Dynamics Shaping 2026 Strategy
- Specification-driven purchasing: A significant portion of demand is specification-led. Buyers in nuclear and medical sectors prioritize certified performance and lifecycle documentation over unit price alone.
- Product differentiation via boron concentration and machining: Variants in boron content and the availability of tight-tolerance machining/fabrication increasingly define supplier selection. High-boron formulations command strategic importance in specific applications, but they require different production and QA workflows.
- Logistics and lead times matter: Large-format sheets and machined blocks impose freight and handling considerations. Supply-chain disruptions or single-source dependence can delay critical path activities in reactor maintenance or facility builds.
- Regulatory convergence and harmonization: While national standards remain influential, internationally recognized military and nuclear specifications act as de facto market qualifiers for suppliers targeting export and large institutional orders.
Strategic Recommendations for 2026
- For buyers (utilities, hospital systems, defense primes): Shift procurement to a two-tier sourcing model combining a certified primary supplier for mission-critical runs and vetted secondary vendors for contingency and small-batch work. Build acceptance criteria that prioritize long-term attenuation performance and documented aging behavior.
- For suppliers (manufacturers and fabricators): Invest selectively in capabilities that raise barriers to entry: certified process control, large-format extrusion capacity, and in-house precision machining. Complement product with installation and design services to capture system-level value.
- For investors and corporate development teams: Consider bolt-on acquisitions that provide either certification credentials or localized fabrication networks. Target deals that close capability gaps (e.g., machining, certified traceability, or raw-material feedstock control) rather than simple volume plays.
- For innovators and R&D groups: Prioritize formulations and processing techniques that maintain hydrogen density and mechanical properties over long-term service life, while minimizing embrittlement and dimensional drift under realistic exposure scenarios.
What We Are Holding Back—and Why
Consistent with our “trailer” approach, the executive summary above highlights the strategic contours and operational levers that matter most in 2026. To preserve the commercial value of the dataset—and to help practitioners move directly from insight to action—the report itself contains granular segmentation by region, application, and boron-content tiers, as well as supplier-level revenue estimates, price benchmarks, and a turnkey supplier contact matrix. Those line-level details are intentionally omitted here to encourage direct engagement with PW Consulting’s full offering, where teams can download datasets, scenario tools, and supplier scorecards suited to procurement RFPs or investment memoranda.
How PW Consulting Supports Implementation
We structure our advisory engagements around turning market intelligence into executable plans. Services available to clients include:
- Custom procurement RFP templates and supplier evaluation workshops.
- Onsite supplier audits and certification-gap analyses to accelerate qualification cycles.
- Scenario modeling tailored to program timelines—helping align stocking policies and CAPEX for extrusion or machining investments.
- M&A diligence support focused on integration risk and value capture in specialty polymers and shielding assemblies.
For executives assessing capital allocation, supplier managers refining sourcing strategies, or engineering leaders specifying shielding for new projects, our report is explicitly designed to bridge the gap between technical nuance and commercial decision-making.
Next Steps
PW Consulting’s Industrial Grade Borated Polyethylene Materials Market report is the authoritative planning tool for 2026. To access the full dataset, supplier scorecards, and practitioner templates that underpin the recommendations above, please visit our report page or contact our strategy team for an advisory briefing and tailored scenario run.
For detailed analysis of this topic, please visit the official page: Industrial Grade Borated Polyethylene Materials Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com