

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Cephalosporin Intermediates (GCLE) Market to Rise from USD 392.36 Million in 2025 to USD 566.97 Million by 2032 (5.4% CAGR) as Asia‑Pacific Leads with USD 244.39M

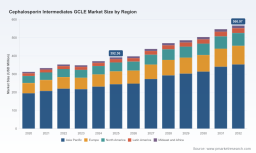
Cephalosporin Intermediates (GCLE) Market — PW Consulting Strategic Briefing for 2026 Decision‑Makers
PW Consulting today issues a strategic briefing derived from our full market research report on Cephalosporin Intermediates — specifically GCLE (7‑phenylacetamido‑3‑chloromethyl cephalosporanic acid p‑methoxy benzyl ester). Anchored on a 2025 base year and a 2026–2032 forecast horizon, the study synthesizes commercial, technical and regulatory intelligence to inform capital allocation, procurement strategy and M&A decisions in 2026. The global GCLE market is estimated at approximately USD 392.36 Million in 2025 and, under our base forecast, grows at a 5.4% CAGR through 2032 to reach roughly USD 566.97 Million. This briefing translates those macro dynamics into pragmatic actions executives can take in the next 12–18 months.
Recycled Drawn Textured Yarn Market
Market Snapshot: Growth Drivers and Structural Features
-
Measured, resilient growth: After a recovery period in the early 2020s, the GCLE market entered 2025 from a position of steady demand driven by global cephalosporin API production. Our forecast assumes continued expansion at a mid-single‑digit CAGR (5.4%) through 2032, underpinned by sustained therapeutic demand and incremental quality upgrades in intermediate specifications.
Worldwide Water Wall Panels Market -
Concentrated upstream exposure: GCLE production is technically rooted in penicillin‑based synthetic routes. Industry evidence shows that Penicillin‑G remains the principal starting material and, in practice, is predominantly sourced from China. That single‑source dependency creates a structural supply‑chain vulnerability that ripples through pricing, availability and qualification timelines.
Multifunctional Hydrotropes Market -
Regulatory and trade nuances matter materially: Recent policy mechanisms — including authorization schemes that permit import of Penicillin‑G without minimum import price (MIP) constraints for export‑oriented cefixime manufacture in India — alter the economics for some global producers. Parallel logistics pressures (higher ocean freight and container scarcities) have intermittently inflated export costs, especially for firms reliant on long downstream supply chains.
-
Quality and grade migration: Buyers are increasingly specifying higher‑purity GCLE grades to reduce downstream processing burden and to meet tighter regulatory scrutiny in end markets. This trend favors suppliers with advanced process controls and validated quality systems.
What Makes This Report Operationally Valuable for 2026?
-
Actionable supplier intelligence — not just names: Beyond listing active players, the report provides validated supplier archetypes (integrated global innovator, scale‑focused Chinese integrator, India‑based niche supplier, and contract specialist) with decision trees for qualification, dual‑sourcing and on‑shoring scenarios.
-
Supply‑chain stress testing: We deliver scenario models that quantify the P&L and working capital impact of plausible disruptions — e.g., raw‑material supply interruption, a 20–40% rise in ocean freight, or a one‑quarter delay in material release. Each scenario includes mitigation playbooks and procurement triggers.
-
Regulatory and trade tracker: A continuously updated matrix maps the interaction of licensing, export incentives and import controls that affect GCLE flows and the economics of finished cephalosporin APIs. This is designed to inform sourcing location choices and long‑lead regulatory filings in 2026.
-
Commercial templates: Negotiation scorecards, lead‑time benchmarking dashboards, and tiered contract language (supply continuity clauses, quality release criteria, force majeure refinements) are included for immediate deployment by procurement and legal teams.
-
Capital allocation tools: For investors and corporate strategy teams, the report includes TEV/EBITDA sensitivity tables, a staged CAPEX decision framework for brownfield expansions, and an IRR model that incorporates raw‑material price volatility and grade‑based pricing differentials.
Competitive Landscape — Strategic Profiles and Implications
-
Otsuka Chemical Co., Ltd. (Osaka, Japan) — Originator advantage and dedicated capacity. As the developer and a principal manufacturer of GCLE, Otsuka demonstrates the combination of legacy process know‑how and validated quality systems that buyers prize for regulated markets. Its investments — including manufacturing presence in India — provide strategic flexibility for offtake contracts and regional supply cushions.
-
Otsuka Chemical (India) Private Limited (Haryana, India) — Localized capacity for export‑oriented production. The Indian plant’s positioning benefits from favorable regulatory routes for export economics when aligned with domestic incentives and relaxed MIP norms for targeted products.
-
Virchow Group / Virchow Petrochemicals (Telangana, India) — India‑based scale with a focus on GCLE supply to regional and global customers. Competitive in cost arbitrage and nimble on custom supply formats for formulators.
-
Chinese listed and private manufacturers (multiple Tianjin, Ningbo, Jiangsu and Shandong‑based firms) — breadth and proximity to penicillin feedstocks. These firms display rapid capacity scaling, integration into penicillin supply chains and competitive pricing, but some have historically faced perceptions of variable quality and process maturity — an opportunity for differentiation through certification programs and strategic partnerships.
-
Market positioning insight: The supplier base presents a mixed model — a small set of well‑established technology holders and a larger group of execution‑oriented manufacturers. Buyers should calibrate supplier selection against three vectors: quality/validation readiness, raw‑material security (contracts for penicillin‑G), and logistical footprint relative to end‑market delivery.
Risk Matrix — Triggers, KPIs and Watchlist for 2026
-
Raw‑material concentration: Key trigger — sustained tightening or export restrictions on Penicillin‑G supply in China. KPI to monitor — import volumes and price trends reported by major Chinese producers and trade agencies.
-
Logistics shocks: Key trigger — prolonged elevated ocean freight or container shortages. KPI to monitor — weekly freight indices, port congestion reports, and lead‑time variances from tier‑1 suppliers.
-
Regulatory shifts: Key trigger — changes to MIP or export authorization norms in producer or consuming countries. KPI to monitor — policy notices and commentaries from trade ministries and industry associations in India and China.
-
Quality and compliance events: Key trigger — regulatory inspection outcomes or product recalls in the cephalosporin API chain. KPI to monitor — product release failure rates, audit outcomes and change‑control histories from strategic suppliers.
Recommended 90‑Day Playbook for Executive Teams
-
Procurement: Execute immediate dual‑sourcing pilots for critical SKUs, lock in rolling three‑month purchases with quality release milestones, and include contingency pricing collars to mitigate short‑term raw‑material volatility.
-
Supply security: Negotiate mid‑term off‑take agreements with selected Chinese and Indian manufacturers that explicitly tie to penicillin‑G supply commitments or prioritized allocation in the event of shortages.
-
Regulatory hedging: Fast‑track regulatory dossiers for alternate sources and validate change‑control packages so that supplier swaps can occur with minimal approval delay in regulated markets.
-
Capital and M&A: Prioritize bolt‑on acquisitions or minority investments that deliver vertical integration into penicillin precursors, or that add validated high‑purity manufacturing capacity to shorten qualification cycles.
-
Commercial: Reprice contracts where possible to reflect grade migration and incentivize suppliers to invest in purity upgrades that reduce downstream processing costs.
How PW Consulting’s Report Supports Boardroom Decisions
-
Decision‑ready intelligence: We translate market size trajectories (current market ~USD 392.36 Million in 2025; estimated growth at a 5.4% CAGR through 2032) into investment thresholds, break‑even timetables and procurement KPIs that can be embedded into 2026 operating plans.
-
Scenario‑based capital planning: The report’s TEV/EBITDA and IRR modules allow CFOs and strategy teams to test CAPEX and acquisition alternatives under multiple raw‑material and regulatory outcomes.
-
Operational playbooks: Procurement templates, supplier scorecards and quality gating frameworks are provided in deployable form so that functional teams can act on insights within weeks, not months.
Closing — A Strategic Preview Designed to Drive Action
The GCLE value chain is at an inflection point where modest but persistent market growth, coupled with concentrated raw‑material exposure and evolving regulatory dynamics, will determine winners and laggards through 2026. PW Consulting’s full report provides the granular segmentation, validated supplier scorecards, proprietary pricing curves and scenario models that commercial teams and boards will require to move from insight to contract. This briefing presents the strategic contours and immediate actions; the full dataset and operational deliverables — including the region‑ and application‑level segmentation tables, supplier performance matrices and downloadable commercial templates — are available through our report portal.
For organizations that must make supply, spend and investment decisions in 2026 with confidence, the right combination of supply‑chain hardening, regulatory foresight and disciplined capital allocation will be decisive. PW Consulting’s Cephalosporin Intermediates (GCLE) report is designed to be the single source of truth for those decisions.
For detailed analysis of this topic, please visit the official page: Cephalosporin Intermediates GCLE Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com