

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting Forecasts 9.15% CAGR for Worldwide Highly Pure Coconut Shell Activated Carbon Market as Asia-Pacific Drives Growth

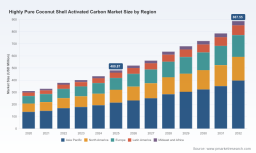
Worldwide Highly Pure Coconut Shell Activated Carbon Market — Strategic Briefing for 2026 Decisions
PW Consulting’s latest market research — the Worldwide Highly Pure Coconut Shell Activated Carbon Market report (base year 2025, forecast 2026–2032) — translates complex supply-chain, pricing, and demand signals into a practical playbook for senior executives, procurement leads, and corporate strategists preparing for 2026. The core message is straightforward: the market is expanding at a sustained pace (9.15% CAGR across the forecast window) and will materially change competitive dynamics, cost structures, and sourcing strategies through to 2032. This briefing highlights the report’s strategic value for 2026 decision-making, outlines high‑impact scenarios, and previews the practical tools included in the full deliverable — while intentionally preserving the granular split tables and segment-level figures for subscribers.
Worldwide Ad Network Software Market
Market Snapshot: Scale, Growth Trajectory, and Structural Features
-
Macro growth: The market shows robust expansion from the 2025 base, reflecting heightened demand across core applications such as municipal and industrial water treatment, precious-metal recovery, food & beverage processing, and technical applications in semiconductors and medical filtration. The report’s forecast embeds a compound annual growth rate of 9.15% for 2026–2032, underpinned by regulatory tightening and accelerating replacement cycles for high‑purity adsorbents.
EV NMC Battery Market -
Consolidation profile: Market concentration is meaningfully skewed toward established specialists. The top three players control a significant portion of global volume, and the top five firms capture a clear majority of market share — a dynamic that drives pricing power, capacity discipline, and route-to-market advantages for incumbents.
Worldwide Police Scanner Market -
Demand mix: The product range remains anchored in granular and powdered grades optimized for different performance envelopes. High‑purity, low‑ash coconut shell carbons continue to be preferred where regulatory and quality requirements are most stringent.
Why this Matters for 2026 Strategy
-
Procurement and cost control are front‑row issues. Raw‑material and feedstock volatility, coupled with supplier pricing actions, translate quickly into cost of goods sold for downstream users. Buyers that enter 2026 with clearer multi‑supplier strategies, indexed pricing clauses, and longer lead‑time visibility will preserve margins and avoid reactive spot purchasing.
-
Supply security is a strategic lever. Given the concentrated nature of quality feedstock and the geopolitical friction raising the cost of certain import routes, companies must treat coconut-shell activated carbon as a component with strategic inventory and dual‑sourcing planning rather than a routine commodity.
-
Product differentiation will increasingly decide margin capture. Suppliers that can certify low-ash, high-hardness, and trace-level purity for critical applications (e.g., pharmaceutical filtration, ultrapure water for semiconductors) command price premia and longer-term contracts.
-
M&A, joint ventures, and off‑take agreements will accelerate. With mid‑cycle capacity additions and periodic raw material tightness, integrated players and financial sponsors are exploring equity investments and strategic alliances to secure feedstock and capacity.
Supply‑Side Dynamics and Practical Implications
-
Feedstock tightness and input price pressure: The coconut shell charcoal feedstock market experienced a pronounced tightening through 2024–2025 that persisted into planning horizons for 2026. For practitioners, this means conducting supplier stress‑tests against multiple raw‑material trajectories and running a “stretch” procurement plan that models worst‑case availability and lead times.
-
Pricing behavior and tactical responses: Several large manufacturers have moved to protect margins via price adjustments and contract restructuring. Procurement teams should expect accelerated use of forward‑cover instruments, multi‑tier pricing clauses tied to raw‑material indices, and portfolio hedging (geographic and product-form diversification).
-
Logistics and port dependencies: Shipping and port access remain non-trivial contributors to delivered cost and reliability. Firms with exposure to single‑port logistics or long international routing should re-evaluate warehousing footprints and explore regional stocking partnerships to reduce the probability of supply interruptions during 2026 peak demand windows.
Competitive Landscape — Who Matters and Why
The competitive map is dominated by a mix of long‑established specialists and vertically integrated suppliers. Key strategic characteristics we emphasize in the full report include capacity scale, feedstock integration, quality certifications, geographic reach, and customer‑segment focus.
-
Haycarb PLC — With a leading global position and recent capacity expansion through a new automated activation plant, Haycarb’s playbook centers on scale, sustainability credentials, and a diversified supply base across the region. For corporate partners, this profile signals consistency and large‑lot supply capability.
-
Jacobi Carbons Group (Osaka Gas Chemicals) — A global manufacturer with strong specialty-grade offerings, Jacobi recently implemented a significant price adjustment to reflect raw material pressures. This move demonstrates the pricing discipline available to large players and the importance of contractual protections for buyers.
-
Regional champions (e.g., Raj Carbon, Kalpaka, Xingsen Carbon, and other Asia-based producers) — These firms compete on cost, proximity, and adaptability in granular and powdered product forms. Their strategic intent frequently focuses on rapid order fulfilment and tailored grade development.
-
Western/regional service providers (e.g., Carbon Activated Corporation, Karbonous, Mellifiq) — These companies emphasize value‑added services such as regeneration, filtration system integration, and technical support for regulated markets. Buyers looking to reduce total cost of ownership should weigh integrated service offers against raw material‑focused supply.
PW Consulting’s full competitor matrix benchmarks each of the major providers on nine dimensions (capacity, quality certifications, sustainability and traceability, lead time, price volatility exposure, technical service depth, regional footprint, contract flexibility, and strategic contracts in regulated sectors). This is an operational tool for sourcing decisions — not just descriptive industry color.
Risk Scenarios — Short, Medium, and Long Horizon
-
Short term (0–12 months): Episodic feedstock disruptions and reactive supplier price increases. Action: Activate contingency inventories, revise spot‑purchase authority, and deploy short-term forward buys against credible suppliers.
-
Medium term (12–36 months): Structural rebalancing of supply chains, selective reshoring, and increased regionalization prompted by trade policy and tariff shifts. Action: Reassess supplier qualification criteria, evaluate nearshoring for critical grades, and invest in supplier development programs.
-
Long term (36+ months): Technology and substitution risk (e.g., new adsorbent chemistries or recycling/regeneration scale-ups) that could compress premiums on high‑purity coconut shell grades. Action: Monitor R&D developments, protect channel relationships through long‑term contracts, and build options for regeneration partnerships.
What the Report Delivers — Practical, Operational Tools for 2026
-
Decision-ready demand and supply model: A dynamic model that connects macro demand drivers to grade‑level needs and translates them into procurement volumes, working capital impacts, and capex scenarios.
-
Supplier scorecard and short‑list methodology: Objective templates and qualifying thresholds to run an expedited RFP that converts technical specifications into commercial comparators.
-
Pricing & contract playbook: Negotiation playbooks that include indexed clauses, pass‑through templates, and a tiered contracting approach suited to both large anchor buyers and smaller processors.
-
Scenario planner and stress tests: Pre-built scenarios (mild, moderate, severe supply shock) that quantify cost and service impacts under differing raw material and logistical assumptions.
-
M&A and partnership lens: Target profiles and integration checklists for executives evaluating upstream asset acquisitions, tolling arrangements, or strategic tolling‑to‑ownership transitions.
How to Use This Intelligence in 2026 — Recommended Next Steps
-
Immediate (60–90 days): Run a supplier exposure audit, identify single-source risks for critical grades, and initiate contract conversations to secure capacity for Q3–Q4 2026 requirements.
-
Near term (6 months): Implement the supplier scorecard across your sourcing team, adopt at least one alternative regional supplier, and update budget forecasts to reflect the report’s central-case pricing trajectory.
-
Medium term (12 months): Consider strategic inventory nodes and potential co‑investment with a supplier to lock capacity or secure preferential allocation in tight cycles.
Invitation — Where the Full Intelligence Adds Value
This briefing highlights the strategic contours and operational levers that PW Consulting’s full report unpacks in greater depth. The comprehensive study contains granular segmentation (by region, product form, and application), detailed vendor benchmarking tables, and downloadable models that enable scenario testing with client‑specific inputs. To preserve the actionable advantage for subscribers, the complete segment-level splits, price trajectories by origin and grade, and the vendor financial scorecards are available through the full report package.
For procurement, operations, or corporate development teams preparing capital allocations and sourcing strategies for 2026, PW Consulting’s report functions as both a market map and a toolkit: it not only diagnoses where value is migrating but prescribes how to capture it. If your 2026 plans hinge on resilience, cost discipline, and strategic supplier alignment in the coconut shell activated carbon value chain, this report should be the foundation of your decision calendar.
For detailed analysis of this topic, please visit the official page: Worldwide Highly Pure Coconut Shell Activated Carbon Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com