

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Worldwide Machine Tool Control Transformer Market to Reach USD 1,228.7 Million by 2032 at a 4.6% CAGR — Asia Pacific Leads with USD 390.47 Million in 2025

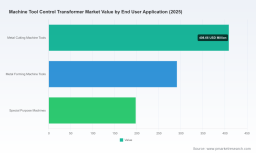
Worldwide Machine Tool Control Transformer Market — Strategic Insights for 2026 Decision-Makers
Executive summary
As capital equipment manufacturers, control-panel assemblers, OEM procurement teams, and private equity investors set budgets and strategic priorities for 2026, the machine tool control transformer market has returned to a path of steady expansion after a period of mid-cycle rebalancing. PW Consulting’s new market study synthesizes seven years of historical performance (2020–2025) and delivers a detailed forecast for the 2026–2032 window. The market is modeled on a 2025 base and a 2026–2032 forecast horizon with a projected compound annual growth rate (CAGR) of 4.6% for the forecast period. Our analysis combines market sizing, cost and margin sensitivity, supplier capability mapping, and regulatory foresight to give decision-makers the pragmatic inputs needed to align capital allocation, sourcing, and product roadmaps with an evolving supply-cost and policy environment.
Worldwide Parabolic Solar Concentrators Market
Market trajectory: what the headline numbers tell you
PW Consulting’s topline view shows recovery and measured growth. From the early-2020 baseline through 2025 the industry absorbed uneven demand across machine tool classes, and the 2026–2032 forecast reflects both normalization of capital cycles and structural demand drivers such as electrification and automation. The 4.6% CAGR embedded in our central forecast assumes moderate technology substitution, ongoing aftermarket opportunity growth, and periodic raw-material-driven cost pressure that can be managed through procurement strategy. For executives, that translates into a market that is large enough to justify scale investments—especially in aftermarket services, custom-engineering capabilities, and supply-chain resilience—while still rewarding nimble product differentiation and cost engineering.
Ceiling-mounted Medical Grade Air Purifier Market
Key market drivers and near-term dynamics
-
Raw-material volatility: Copper and electrical steel remain the dominant cost levers for machine tool control transformers. Copper experienced a sharp intraday spike in early 2026 and remains subject to tight supply-demand dynamics driven by electrification across industries. Electrical steel prices have more than doubled since 2020 in some supply bands, contributing to margin pressure for producers that cannot pass through costs rapidly. Our report quantifies the pass-through sensitivity and models multiple hedging and supplier-qualification scenarios.
Worldwide HIPAA Compliant Messaging Software Market -
Regulatory exclusions that matter: Unlike distribution transformers, machine-tool control transformers are excluded from recent U.S. DOE efficiency regulation scopes—this distinction, and similar state-level exemptions, materially alters compliance and product-development roadmaps. In practice, the exclusion reduces the near-term regulatory impetus for expensive core-loss optimizations at the control-transformer level, allowing suppliers and OEMs to prioritize inrush performance, isolation, and physical packaging over marginal efficiency gains where those trade-offs are value-accretive.
-
End-user dynamics: Automation adoption in metal-cutting and forming applications continues to drive higher-specification control panels, but demand mix is shifting toward solutions that balance high inrush handling with compact footprint and predictable lifecycle costs. This incrementally favors supplier partners that can deliver engineered-to-order units and robust aftermarket support.
-
Supply-chain reshoring and qualification cycles: Lead-time risk and qualification barriers have made supplier diversification and dual-sourcing practical imperatives for mission-critical production lines. Cost volatility has heightened interest in alternative procurement constructs such as index-linked contracts and multi-year supply agreements with tiered pricing.
What the report contains — practical, executable deliverables
PW Consulting’s study is designed as an action toolkit rather than a descriptive catalog. Highlights include:
- Interactive financial model calibrated to the PW baseline—scenario-driven P&L and cash-flow impacts for price, copper, and electrical-steel shocks.
- Procurement playbook—supplier segmentation, qualification scorecards, and sample contract clauses for price escalators, lead-time guarantees, and quality penalties.
- Product-portfoli o optimization templates—decision logic to prioritize component substitution, frame-size rationalization, and aftermarket kit development.
- Competitive capability matrix—technology and compliance benchmarking across manufacturers (molded vs. dry-type, inrush-handling design, UL/CSA and regional approvals, custom-engineering throughput).
- Risk heat map and mitigation playbooks—mapped by supplier geography, single-source exposures, and raw-material dependencies, with tactical and strategic response options.
- Deal diagnostics for investors and acquirers—value-creation levers, quick-win cost takeouts, and integration risk checklist for M&A in the control-transformer space.
Each deliverable is built to be operational: spreadsheets, boilerplate contract language, annotated supplier RFP templates, and a regulator tracker that flags jurisdictional nuances that matter to engineering and procurement teams.
Competitive landscape — concentration, capability, and strategic postures
The market exhibits a moderate top-tier concentration: our CR3 and CR5 metrics indicate the industry’s leading groups control a meaningful but not dominant share of volume and revenue. That structure creates opportunity for both scale-driven incumbents and focused niche players.
-
Large North American incumbents (examples include firms with deep dry-type transformer portfolios) leverage scale, broad distribution networks, and extensive UL/CSA certification archives. Their competitive advantages are rapid fulfillment at scale, broad catalog offerings, and legacy relationships in heavy-industry OEMs and panel builders.
-
Specialist U.S. and European engineering houses distinguish themselves through high-inrush designs, custom VA ranges, and strict compliance with industrial standards. These players capture margin in engineered-to-order business and aftermarket spares, where application-specific performance matters more than price alone.
-
Low-cost and export-focused manufacturers from Asia have expanded capability and now offer variants that borrow design techniques from Western counterparts. Their strategic play often emphasizes competitive pricing, rapid capacity expansion, and tailored commercial terms for high-volume OEMs.
-
Service- and solution-oriented firms are growing their footprint by bundling transformers with control panels, testing services, and field-support contracts—this integration reduces buyer complexity and improves lifetime revenue capture.
PW Consulting’s supplier profiles evaluate product families (molded vs. dry-type), inrush performance, certification breadth, and custom-engineering capacity. The report highlights practical selection criteria for procurement teams—how to trade off unit cost versus qualification time, repairability, and lead-time reliability.
Strategic implications for 2026 decisions — six recommended actions
-
Lock in layered procurement protection: Combine short-term indexed purchase agreements to manage copper swings with medium-term strategic contracts for capacity assurance. Our model shows how hybrid contracting reduces margin volatility while preserving upside from price declines.
-
Prioritize modular product design: Standardize core interfaces and modularize transformer chassis so redesigns (to adapt to alternative core or winding materials) can be completed without full requalification of control panels.
-
Shift investment to aftermarket and retrofit services: Warranty extension products, preventive maintenance kits, and rapid-replacement programs offer higher-return, lower-capex pathways to margin expansion.
-
Target bolt-on M&A selectively: Look for small engineering-focused assets that provide inrush-handling IP, regional distribution channels, or certification footprints that shorten time-to-market in prioritized geographies.
-
Operationalize environmental- and energy-cost monitoring: Given electrical-steel and copper cost trends, embed a raw-material pass-through index into pricing models and launch a rapid-review process for BOM redesign when material-price thresholds are breached.
-
Maintain active regulatory monitoring: The current exclusions from DOE and specific state-level rules create a window to optimize design for performance rather than efficiency alone—but this could change. Build a regulatory trigger protocol that translates policy changes into product and sourcing responses within 90 days.
Why PW Consulting’s study is the tactical advantage for 2026
Our report is intentionally structured as a decision-enabler for executives who must weigh near-term margins against long-term strategic positioning. We combine a defensible, transparent market-sizing approach with tactical artifacts—contract templates, supplier scorecards, cost-sensitivity models, and scenario playbooks—that allow cross-functional teams (procurement, engineering, finance) to act immediately.
To preserve the commercial utility of our proprietary segmentation and supplier intelligence, the public summary above highlights the analytical framework and strategic conclusions without disclosing the granular segment allocations and company-level revenue splits that matter when formulating supplier negotiations or M&A bids. Subscribers to the full report receive the complete dataset, downloadable models, and a confidential supplier-performance workbook that maps performance to price, lead time, and qualification risk.
Next steps
For procurement leaders, engineering heads, and corporate strategists preparing 2026 budgets, the full PW Consulting study delivers the practical tools and validated assumptions required to convert market foresight into measurable outcomes. Accessing the full report provides the detailed segmentation, supplier-level benchmarking, and downloadable scenario models that our summary intentionally omits so companies can use them as the basis for negotiation, investment, or divestiture strategies.
For detailed analysis of this topic, please visit the official page: Worldwide Machine Tool Control Transformer Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com