

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Worldwide Multi‑Sensor & Multi‑Directional Security Camera Market to Hit USD 3,911.82 Million by 2032, Backed by 15.26% CAGR

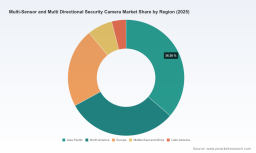
Worldwide Multi‑Sensor and Multi‑Directional Security Camera Market: Strategic Imperatives for 2026 Decision‑Makers
As organizations plan capital and operating expenditures for 2026, multi‑sensor and multi‑directional security cameras are moving from niche deployments to foundational infrastructure for wide‑area surveillance, smart‑city initiatives, and complex enterprise estates. PW Consulting’s latest market study — covering historical trends (2020–2025) and a detailed forecast to 2032 — frames a pragmatic playbook for executives who must balance rapid capability gains from edge AI and sensor fusion against growing regulatory and supply‑chain complexity.
Worldwide High Pressure Booster Pumps Market
Market snapshot: scale, growth trajectory, and what it means for procurement
The market for multi‑sensor and multi‑directional cameras has expanded rapidly across the last half‑decade. PW Consulting’s baseline model shows a compound annual growth rate (CAGR) of 15.26% through the forecast horizon, with total industry revenues growing from a strong base in the early 2020s to a multi‑billion‑dollar opportunity by the early 2030s. Our 2026 projection signals a clear inflection: demand accelerates as customers upgrade from single‑sensor PTZs and multiple‑camera arrays to consolidated multi‑sensor systems that lower total cost of ownership for wide‑area coverage.
Small Joint Suture Anchor Market
For procurement organizations, the implication is straightforward: 2026 is the year to transition from tactical camera buys to strategic platform contracts. The market is large and growing quickly enough that choices made this year will materially affect lifecycle costs, analytics enablement, and vendor dependence for several contract cycles.
Worldwide Financial Services CRM Software Market
Why multi‑sensor is winning: three practical drivers
-
Operational efficiency through sensor consolidation — Multi‑sensor units reduce cabling, rack space, and camera count while delivering broad, stitchable coverage. For large perimeters, concourses, and plazas, that translates into lower installation and maintenance costs and fewer integration touchpoints for VMS platforms.
-
Edge compute and analytics — Vendors increasingly embed substantial neural processing (serverless inference or accelerated modules such as Jetson‑class platforms), enabling advanced analytics on‑device. That reduces bandwidth and cloud costs for continuous monitoring and supports privacy‑sensitive, localized decisioning for alerts and automated responses.
-
Design flexibility — Modern multi‑direction systems support combinations of fixed panoramic sensors, adjustable modules, and PTZ‑augmented hybrids. This architectural flexibility lets integrators tune solutions for both broad situational awareness and zoomed investigative views without proliferating unique camera models.
Regulatory, interoperability, and supply considerations that will shape 2026 choices
-
Compliance and procurement risk — NDAA restrictions and U.S. export controls remain material considerations for government and regulated enterprise deployments. Buyers must verify supplier compliance proactively as part of contract award and acceptance testing.
-
Standards interoperability — ONVIF and related network video standards continue to be the baseline for ensuring VMS and analytics compatibility. Our field work shows that projects that bake interoperability testing into procurement reduce downstream integration cost by a measurable margin.
-
Component & manufacturing exposure — Sourcing decisions should account for geographic manufacturing footprints and supply‑chain risk. Diversified sourcing and multi‑tier inventory strategies will de‑risk large rollouts scheduled in 2026–2028 windows.
Competitive landscape — who matters and why
The market exhibits moderate concentration: the top three vendors account for a meaningful share, and the top five consolidate a majority portion of revenues. That dynamic produces two strategic effects for buyers: first, incumbent vendors can influence roadmap and interoperability standards; second, there’s ample room for best‑in‑class niche players to win vertical or regional mandates.
Key suppliers active in multi‑sensor and multi‑direction segments include established global OEMs and cloud‑native entrants. Examples we track closely:
-
Hanwha Vision — Pushing serverless edge AI with recent product introductions leveraging accelerated platforms to deliver multi‑channel inference without additional servers.
-
Axis Communications — Focused on modular multidirectional lines that emphasize seamless panoramic imaging for municipal and enterprise applications.
-
i‑PRO — Concentrating on multi‑directional + PTZ hybrids with robust low‑light imaging and automated tracking competencies for challenging environments.
-
Avigilon (Motorola Solutions), Pelco, Honeywell, Hikvision, Dahua, Bosch, Vivotek and others — Each brings differentiated strengths across analytics, systems integration, and industrial design that make vendor selection a matter of matching product capabilities to operational requirements rather than purely price.
-
Cloud‑native and agile competitors such as Rhombus Systems and OpenEye — Offering cloud management, PoE‑centric deployment models, and compliance features useful for multi‑site enterprises.
Recent product moves illustrate the speed of innovation: late‑2024 and early‑2026 releases show leaders embedding higher on‑device inference, refining NDAA‑compliant SKUs, and refreshing product matrices to capture enterprise RFP cycles in 2026. These developments confirm our view that product evolution — not just price competition — will drive share shifts in the next 18–36 months.
What PW Consulting’s report delivers for 2026 strategy
Our new report is designed as an operational toolkit for decision‑makers. It moves beyond descriptive market sizing to deliver:
-
Detailed demand modelling and scenario analysis (base, accelerated, downside) to support budget planning and sensitivity testing for multi‑year procurement windows.
-
Vendor decision matrices that score suppliers across product architecture, analytics maturity, compliance posture, and lifecycle economics — enabling rapid short‑listing for RFPs.
-
Practical deployment playbooks: PoC templates, acceptance test plans, network and storage sizing guidance, and recommended security hardening steps for edge devices.
-
Integration roadmaps for VMS, PSIM, and enterprise data lakes — including tradeoffs between edge‑first vs. cloud‑centric analytics and how those choices affect ongoing OPEX.
-
Procurement and contracting advisories — model service level agreements, firmware lifecycle clauses, and compliance certification checklists that reduce vendor lock‑in and legal exposure.
Note: the granular sub‑segment volumes and regional splits underpinning our forecasts are reserved for the full report and dataset. This executive briefing highlights the strategic implications without exposing the detailed tables that enterprise teams require for procurement validation.
Actionable recommendations for 2026
-
Adopt platform procurement, not unit procurement — Structure RFPs around capability bundles (analytics profile, edge compute, integration APIs, compliance) rather than solely camera counts. This secures roadmap alignment and predictable upgrade paths.
-
Make NDAA and export‑control verification a pre‑award gate — Require documented supply‑chain attestations and firmware provenance clauses during bidding to avoid retroactive write‑downs or contract cancellations.
-
Design PoCs around network and analytics throughput — A successful PoC must validate end‑to‑end behaviour: daylight/night performance, analytics false positive rates, and operational alerts under expected network constraints.
-
Prioritize interoperability testing early — Demand ONVIF‑compliant handshake and VMS integration tests as part of acceptance criteria to limit custom driver work and integration delays.
-
Plan for staged rollouts with spares and diverse sourcing — Large rollouts benefit from phased procurement windows, buffer inventory, and alternative suppliers prequalified to mitigate manufacturing or component shortages.
How to use this insight in boardroom decisions
For CIOs, CSOs, and capital planners, the combination of a high growth rate and moderate market concentration means two things: first, technology selection will have long‑lived implications for security posture and analytics value; second, vendors are investing significantly in product differentiation, particularly around on‑device AI and compliance. The right decision in 2026 is therefore less about choosing the cheapest camera and more about securing a resilient platform: one that balances interoperability, upgradeability, and legal compliance.
PW Consulting’s report supplies the modelling, vendor scoring, and procurement artifacts to turn these strategic imperatives into executable plans. It is expressly crafted to help procurement boards, security OEM partners, integrators, and infrastructure owners move from evaluation to deployment with confidence and minimized execution risk.
Next steps
If your organization is planning major surveillance or smart‑city investments in 2026, PW Consulting’s full report — including the comprehensive datasets, segmented forecasts, and vendor scorecards — will be essential for RFP design, risk mitigation, and supplier negotiation. For an executive‑level briefing or to access the full dataset and playbooks, visit the report page or contact our industry practice to schedule a tailored walkthrough.
For detailed analysis of this topic, please visit the official page: Worldwide Multi-Sensor and Multi Directional Security Camera Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com