

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting Forecasts Worldwide 5G NR Antenna Market to Reach USD 80,113.5 Million by 2032, Driven by a 15.68% CAGR

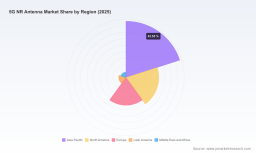
Worldwide 5G NR Antenna Market: Strategic Imperatives for 2026 Decisions
As PW Consulting’s Senior Strategic Advisor and Chief Industry Analyst, I present a concise, practitioner-focused synthesis of our latest Worldwide 5G NR Antenna Market research. This briefing is intended to frame the high-stakes decisions that network operators, infrastructure vendors, component suppliers, investors and large enterprise IT teams must make in 2026. We show the market trajectory, the force-multiplying dynamics shaping supplier and procurement choices, the competitive contours to watch, and an operational playbook—while intentionally preserving the report’s proprietary subsegment detail (to secure competitive advantage and direct stakeholders to the full study for granular intelligence).
Worldwide Retail Distributed Order Management Systems Software Market
Executive snapshot
The global 5G NR antenna market has moved from early scale-up to broad commercial expansion. On a macro basis, the market grew from roughly USD 12.5 billion in 2020 to about USD 28.9 billion in 2025, with our base year set at 2025. Under the forecast scenario informing our analysis, the market continues to expand into 2026 and beyond, with a compounded annual growth rate around 15.7% across the forecast horizon. This growth reflects a sustained investment cycle in both radio access evolution (massive MIMO and active AAUs) and complementary coverage solutions (DAS, small cells, and hybrid passive-active panels).
Duct Air Conditioner Market
Why this matters for 2026 strategic decisions
- Capital allocation for network buildouts will be judged not only on coverage needs but on antenna architecture choices that materially affect site economics, power consumption, and upgrade paths for future releases of 3GPP specifications.
- Procurement teams must balance near-term supply risk and cost inflation against long-term capacity requirements; the right vendor mix and contractual structures can mitigate exposure to raw-material price swings and regulatory-driven rework.
- For vendors, product roadmaps must align with evolving OTA emission norms, broader spectrum availability, and operators’ preference for integrated vs. disaggregated radio-antenna solutions.
Market dynamics shaping supplier and operator strategy
Regulatory and standards-driven inflection points
Several policy and standards developments are reshaping technical requirements and commercial viability. 3GPP Release 19 (March 2025) introduced new over-the-air spatial emission limits in the upper 6 GHz band to protect fixed satellite uplinks—this materially affects antenna pattern design, calibration procedures, and OTA testing workflows for manufacturers and integrators. Separately, U.S. legislative direction (P.L. 119-21) has set in motion a multi-year spectrum pipeline and renewed FCC auction authority extending through 2034, increasing the certainty around mid- and upper-band allocations for licensed mobile use. These developments force a design-for-compliance mindset early in R&D and materially increase the importance of test-and-measure partnerships during product development.
Worldwide Magnesium Hydroxide Fire Retardant Additives Market
Infrastructure and supply-side pressure points
Network architectures are sensitive to backhaul economics. Recent industry analysis shows that fiber deployment costs per kilometer remain a significant component of total 5G NR network capex, and fiber optic cable prices themselves surged in early 2026 due to demand from backhaul and data-center interconnect projects. The net effect is a higher marginal cost for cell densification projects. For operators, this raises the bar on evaluating alternative topologies (e.g., fewer macro sites with higher-capacity AAUs vs. denser small-cell overlays) and underscores the value of optimizing antenna selection to reduce the need for excessive fronthaul/fiber upgrades.
Technology migration and deployment choices
Massive MIMO and integrated AAU architectures continue to displace traditional passive-only deployments in many greenfield and macro-upgrade scenarios because of their spectral efficiency and beamforming capabilities. At the same time, distributed antenna systems and purpose-built indoor solutions remain indispensable in high-density venues. Non-terrestrial network (NTN) testing and certification activity—illustrated by recent PTCRB/NTN milestones—also points to new use cases and validation complexity for antenna vendors targeting cross-platform compatibility.
Competitive landscape: what to watch
The market exhibits moderate concentration: the top three vendors account for nearly half of global market sales, and the top five for over sixty percent. This creates a market structure where a few global suppliers influence standards adoption, price benchmarks, and integrated platform availability—yet meaningful opportunity exists for specialized suppliers along three vectors: system-level integration (AAUs and massive MIMO), passive hybrid solutions optimized for energy and sustainability, and in-building/venue DAS systems that require bespoke engineering.
- Global RAN incumbents (Ericsson, Nokia, Huawei, Samsung, ZTE) — These players continue to push integrated AAU and massive MIMO product portfolios, coupling radio and antenna functionality to simplify deployments and extract higher margins from radio-integrated designs. Their strategic advantage lies in end-to-end vendor relationships with major operators and in advanced beamforming implementations that align with evolving Release 19 test requirements.
- Passive and hybrid antenna specialists (CommScope, Amphenol, Tongyu, PROSE) — These firms focus on multi-port passive panels and hybrid integration options suitable for operators preferring disaggregated RAN architectures or upgrades where radio swap-outs are staged over several upgrade cycles.
- Venue and DAS specialists (Corning, JMA Wireless, SOLiD) — Targeted indoor coverage and complex-venue deployment expertise remain high-margin niches. Demand will persist as venues retrofit for 5G NR capacity and as operators seek predictable indoor QoS without extensive macro densification.
Recent vendor and industry moves crystallize these trends: NEC’s planned launch of a new sub-6 GHz massive MIMO radio (planned for early fiscal 2026) signals continued RAN refresh activity in mature markets; Anritsu’s NTN PTCRB certification work with Samsung highlights the growing testing complexity for non-terrestrial and hybrid connectivity; and standards updates from 3GPP are increasingly defining both design constraints and acceptable test methodologies.
Strategic playbook for stakeholders
For network operators
- Adopt a portfolio approach to antenna procurement: preserve optionality between integrated AAUs and passive/hybrid panels to manage rollout sequencing and supplier concentration risk.
- Factor spectrum timing and regulatory certainty into procurement windows. Where auction timetables are known, align major procurement phases to avoid mid-build rework or unforeseen compliance costs arising from new OTA rules.
- Prioritize vendor partnerships that include end-to-end validation support—OTA test procedures and on-site calibration capabilities will shorten time-to-service and reduce interference risk.
For infrastructure vendors and component suppliers
- Differentiate via compliance and test capabilities: early conformance to Release 19 OTA requirements and NTN test cases will translate into preferred supplier status for major operator RFPs.
- Invest in low-power, high-efficiency antenna designs and modular mechanical interfaces to support incremental site upgrades without complete tower overhauls—this reduces total cost of ownership for operator customers.
- Hedge supply exposure to fiber and critical raw materials through contractual clauses and dual sourcing; provide integrated deployment packages that minimize fiber-labor intensity where possible.
For investors and financial sponsors
- Prioritize companies with defensible positions in either integrated AAU technology stacks or high-margin DAS and indoor coverage niches.
- Assess balance sheets for exposure to commodity and logistics inflation; firms with strong supplier diversification and long-term supply agreements will be advantaged.
- Value competitive moats that combine standards leadership (early compliance to Release 19), test-lab capabilities, and operator-installed reference sites.
What PW Consulting’s full report delivers (practical and actionable)
Our comprehensive market study extends this executive synthesis into a tactical resource for procurement, R&D prioritization, M&A diligence, and regulatory planning. The full report includes:
- Proprietary forecasting across the 2026–2032 horizon, calibrated to price and deployment scenarios;
- Decision-ready supplier profiles, technology benchmarking, and integration matrices;
- Implementation playbooks for operators—including capex/opex scenarios and site migration sequencing to support both macro refresh and small-cell densification;
- Risk assessments covering regulatory compliance, spectrum timing, raw-material volatility, and supply-chain constraints (with mitigation strategies);
- Detailed testing and certification roadmaps mapping OTA emission requirements and NTN conformance to product development timelines.
In keeping with the “trailer” principle of this briefing, we are intentionally withholding the granular segmentation tables and detailed regional / application revenue splits from this public summary—these are available exclusively in the full report and model package. That detailed breakdown is the operative intelligence procurement teams and investors need to refine bid strategies, vendor scorecards, and valuation models.
Closing guidance: decisions to make in the next 12 months
2026 will be a defining year for 5G NR antenna strategy. Operators must decide whether to accelerate integrated AAU rollouts to reap spectrum efficiency now, or to extend disaggregated approaches to preserve supplier flexibility. Vendors must choose between competing on integrated system performance versus modularity and sustainability. Investors should watch for businesses that convert standards-compliance, testing capability, and supply-chain resilience into predictable revenue growth.
PW Consulting’s market model shows the runway is significant, but the pace and profitability of adoption will be determined by who anticipates regulatory constraints, seals resilient supplier relationships, and designs uplifts that reduce lifecycle operational costs. For teams responsible for 2026 procurement and product roadmaps, this report provides the market-calibrated intelligence required to make those trade-offs with confidence.
Access the full analysis
For organizations that require the underlying segment-level forecasts, scenario models, supplier scorecards, and procurement playbooks, contact PW Consulting to obtain the full Worldwide 5G NR Antenna Market report and the interactive forecast model.
For detailed analysis of this topic, please visit the official page: Worldwide 5G NR Antenna Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com