

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting Report Forecasts 5.24% CAGR for Worldwide Solenoid Reversing Valve Market Through 2032

PW Consulting — Strategic Preview: Worldwide Solenoid Reversing Valve Market (2026 Outlook)
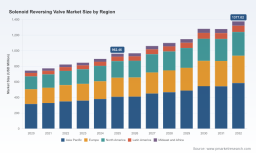
PW Consulting’s latest market research briefing previews strategic implications from our forthcoming Worldwide Solenoid Reversing Valve Market report (base year 2025; forecast period 2026–2032). The market demonstrates resilient growth dynamics, with a 2025 base size of USD 962.46 Million and a compounded annual growth rate (CAGR) of 5.24% over the forecast horizon. By 2032, our top-line projection reaches approximately USD 1,377.02 Million. This preview is designed as a high-value executive primer — showcasing analytical depth and practical recommendations while reserving full granular tables and region/application splits for the full report and subscriber portal.
Mouthguard and Clear Aligners Market
Why this research matters for 2026 corporate decisions
- Energy transition is a demand engine. Accelerating adoption of heat pumps and stricter efficiency goals are expanding demand for robust reversing valve solutions that support low-GWP and natural refrigerants. Procurement and product teams must align roadmaps to that trajectory now to avoid lost share.
- Regulatory and safety constraints are design drivers. Requirements such as UL recognition and maximum operating pressure ratings (e.g., 650 psig for common HFC service) meaningfully constrain engineering choices and supplier qualification. Competitive advantage accrues to suppliers who demonstrate certified compliance across target geographies.
- Input cost volatility is reshaping sourcing strategy. Raw-material price swings — exemplified by hot rolled coil (HRC) price movement through 2025–early 2026 — materially affect valve body and component economics. Production and procurement leaders should adopt hedging and flexible sourcing to preserve margin.
- Market concentration has strategic implications. With a highly concentrated supplier landscape (top-three and top-five players controlling a substantial share), OEMs and system integrators face clear trade-offs between supplier reliability and bargaining power when defining supply strategy.
What the full report delivers (actionable highlights)
- Independent market sizing and validated demand projections (2020–2032), including scenario variants reflecting high/low heat-pump adoption rates.
- Segment-level analysis by type, application and region with build-ups of installed base, replacement cycles and annual unit demand (note: detailed splits and values are included in the full report).
- Supplier scorecards and benchmarking: technical capabilities, materials mix (e.g., stainless vs. plated bodies), refrigerant compatibility, warranty terms and channel coverage.
- Cost-model templates and sensitivity analysis linked to raw-material price indices, labor costs and FX exposure — enabling live “what-if” margin modelling.
- Regulatory compliance matrix and design checklists for global deployment (UL, pressure ratings, refrigerant compatibility and end-of-life requirements).
- Commercial playbooks: prioritized GTM options for OEMs, aftermarket servicing strategies, retrofit product positioning and channel segmentation by vertical.
- M&A and partnership screeners: compact methodology for identifying bolt-on targets, integration risks and potential synergies in manufacturing footprint and technology.
- Operational diagnostics for manufacturing scale-up: CAPEX planning, supplier consolidation scenarios, and lead-time stress-testing under demand surges.
Each of these deliverables is paired with downloadable data assets and an executive dashboard in the subscriber portal to convert insight into immediate action.
Worldwide Backlite Glass Market
Competitive landscape: who matters and why
- Sanhua Holding Group — Hangzhou, China — https://www.sanhuaeurope.com
Sanhua remains a category leader in four‑way reversing valves for HVAC and heat pump markets, with recent product cadence emphasizing stainless-steel variants and broader refrigerant compatibility. Their SHF and next‑generation SHF‑G offerings exemplify the shift toward materials and designs that support low-GWP refrigerants and higher operating pressures.
Worldwide Virtual IT Labs Software Market - Danfoss — Nordborg, Denmark — https://www.danfoss.com
Danfoss combines broad refrigeration and HVAC valve portfolios with strong global channel reach. Competitive strength is their integrated control and system-level orientation, useful for OEMs seeking packaged solutions.
- Parker Hannifin Corporation — Cleveland, USA — https://www.parker.com
Parker’s hydraulic and pneumatic heritage supplies robust directional control solutions and positions it well for industrial and mobile applications where ruggedness and serviceability are critical.
- Bosch Rexroth — Lohr am Main, Germany — https://www.boschrexroth.com
Bosch Rexroth delivers industrial-grade hydraulic reversing valves for heavy machinery, competing on system integration, engineering support and global aftersales.
- Robertshaw — Itasca, USA — https://www.robertshaw.com
Robertshaw’s product strategy focuses on heat‑pump reversible valves, leveraging PTFE and metal slide mechanisms that balance low leakage with high durability for residential and light-commercial systems.
- Wilspec — Oklahoma City, USA — https://www.wilspec.com
Wilspec has carved a niche in geothermal and specialized heat‑pump reversing valves, offering configurations optimized for seasonal switching reliability.
- DunAn — Zhuji, China — https://dunanus.com
DunAn’s portfolio emphasizes electromagnetic four‑way valves for HVAC/refrigeration, competing on cost and scale for large OEMs.
- SMC Corporation — Tokyo, Japan — https://www.smcworld.com
SMC brings pneumatic valve strength and automation know-how, making it a go‑to for industrial automation applications that require reversing functions.
- ASCO (Emerson) — Florham Park, USA — https://www.asco.com
ASCO’s solenoid valve expertise is complemented by Emerson’s systems reach, creating cross-selling opportunities into larger refrigeration and HVAC projects.
- Shandong Yikaide Hydraulic Co., Ltd. — Shandong, China — https://www.yikde.com
A regional manufacturer focused on hydraulic reversing valves for industrial systems, competing on price and proximity to regional customers.
Recent competitive moves underscore product and channel emphasis. Notably, Sanhua introduced the SHF‑G stainless range (Nov 2025) and showcased intelligent control integrations around reversing valve technologies at RACC 2026 (Mar 2026). Such actions signal the dual technical requirements OEMs now demand: material resilience for corrosive refrigerants and smarter integration for system-level efficiency gains.
Segment and supply-side dynamics (what to watch)
- Type and application dynamics. The market mix spans multi‑way reversing valves, three‑way variants and specialty configurations across residential A/C, heat pumps, commercial HVAC and industrial refrigeration. Each segment carries distinct margin profiles, warranty expectations and reliability thresholds — critical factors when choosing production investments or supplier agreements.
- Material and input cost trends. HRC steel price volatility through 2025 and into early 2026 (notable mid‑run spikes) has changed the calculus of local versus global sourcing. Manufacturers with flexible material strategies — including stainless options and low‑waste stamping processes — will preserve margin and shorten time‑to‑market.
- Certification and operating envelope. Compatibility with refrigerant types and certified pressure ratings streamlines OEM qualification. Valve designs that meet common pressure and safety standards reduce custom engineering cycles and accelerate qualification with major equipment manufacturers.
- Concentration and bargaining power. High market concentration among the top suppliers delivers stable OEM relationships but also raises the bar for new entrants in terms of technology and channel access.
Strategic recommendations for 2026
- Prioritize product compatibility with heat‑pump trajectories. Engineering teams should fast‑track designs that support natural refrigerants and higher pressure ratings, while commercial teams create tiered product lines for retrofit and OEM channels.
- Lock in material resilience. Invest in corrosion‑resistant configurations as a differentiator; assess trade-offs in cost vs. lifecycle value with our cost‑model templates.
- Mitigate input volatility. Adopt multi‑sourcing, strategic inventory buffering and indexed supply contracts to manage steel and component cost exposure.
- Leverage concentration to accelerate consolidation or partnerships. Use M&A screeners to evaluate bolt‑on targets that expand geographic footprint, add refrigerant‑compatible technologies or fill distribution gaps.
- Embed serviceability and intelligence. Aftermarket revenue and product stickiness increase with predictive health features and simplified field serviceability — a priority for OEM roadmaps.
Risks and contingencies
- Policy surprises. Faster than expected refrigerant phase‑downs or new pressure/safety standards could necessitate rapid design rework.
- Supply disruption. Concentrated component manufacture and regional production nodes are vulnerable to local trade or capacity shocks.
- Technology commoditization. Price competition for basic reversing valve designs may compress margins; differentiation through materials, controls and service is essential.
Next steps — how to access the full intelligence
This preview highlights the strategic value embedded in PW Consulting’s full Worldwide Solenoid Reversing Valve Market report: validated top‑line projections, practitioner-ready tools and competitive schematics tailored for 2026 decision cycles. For the complete dataset (regional and application splits, model-level unit forecasts, supplier scorecards, downloadable Excel models and scenario dashboards), please visit the PW Consulting research portal or contact our advisory team to arrange a custom briefing and enterprise license.
Contact: PW Consulting — Strategic Markets & Industrial Components Practice. For media, licensing or bespoke advisory requests, visit our website or email our research engagements desk to schedule a 30‑minute executive briefing.
For detailed analysis of this topic, please visit the official page: Worldwide Solenoid Reversing Valve Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com