

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting Forecasts Worldwide HIFU Lipoplasty Devices Market to Reach USD 909.01 Million by 2032, Growing at an 8.01% CAGR

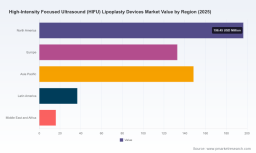
Worldwide High-Intensity Focused Ultrasound (HIFU) Lipoplasty Devices Market — Strategic Outlook for 2026 Decision‑Makers
As HIFU-enabled non‑invasive lipoplasty moves from early adoption into a growth phase, healthcare executives, investors and product leaders face a compressed decision window in 2026. PW Consulting’s latest market intelligence synthesizes five years of historical performance (2020–2025), a 2026–2032 forecast horizon, and a proprietary scenario framework to translate market momentum into executable strategy. At the aggregate level the market is re‑rating: after a 2025 base near USD 530 million, our model anticipates robust expansion through the forecast period driven by technology upgrades, reimbursement tailwinds and broader clinical acceptance (the model’s compound annual growth rate is ~8.0%). The headline trajectory is clear — the market is moving from niche to meaningful scale — and the choices firms make this year will determine who captures the next wave of value.
Worldwide RGB Filters Market
Why this report matters for 2026 decisions
-
Timing: 2026 is a pivot year. Our forecast period (2026–2032) is designed to align with capital planning, product roadmaps and potential M&A timetables. We model multiple adoption scenarios so leadership teams can stress‑test investments against plausible regulatory and reimbursement pathways.
Battery Material Market -
Precision: We blend a bottoms‑up device and service revenue model with top‑down market checks and over 60 primary interviews across OEMs, clinic chains, payers and key opinion leaders. The result is a market size and growth projection that firms can operationalize in budgeting and go‑to‑market planning.
Embryonic Stem Cell Culture Medium Market -
Actionability: Beyond headline numbers, the deliverables are structured to be immediately useful — commercial segmentation, go‑to‑market playbooks, clinical evidence roadmaps, price elasticity scenarios, and M&A target screening. The executive summary highlights strategic options; detailed modules provide the analytics required to act.
What’s in the report — practical modules for implementation
-
Market sizing and forecast model (2020–2032): annualized revenue, demand drivers and sensitivity to payment policy and clinical evidence milestones.
-
Regulatory and reimbursement intelligence: country‑level regulatory pathways, essential compliance checkpoints (including US 510(k) requirements and EU medical device rules) and a payer matrix detailing coverage codes and reimbursement dynamics that materially affect procedure economics.
-
Competitive landscape and vendor heatmaps: capability profiling of leading and emerging OEMs, product positioning (platforms, transducer technologies, form factors), and commercialization playbooks that are winning in different clinical settings.
-
Clinical evidence and KOL strategy: an evidence matrix linking indication strength to adoption velocity, recommended trial designs to unlock new indications (for example deeper adipose targets), and an ROI framework for funding investigator‑led studies.
-
Commercial approaches and pricing models: pricing sensitivity analyses, consumables and service revenue levers, and a distributor vs direct sales decision framework tailored to varied channel economics.
-
M&A and partnership screening: target archetypes, valuation precedents, integration risks, and a short‑list methodology for acquiring transducer IP, treatment‑planning software or regional distribution critical mass.
-
Scenario planning toolkit: three practical market scenarios (conservative, base, accelerated) with trigger indicators and recommended strategic responses for each.
Competitive dynamics — who matters and why
The competitive picture is dominated by a mix of established aesthetic medical device firms and specialized regional players. A few themes dominate competitive battlefields:
-
Product differentiation through transducer and energy control. Recent product launches emphasize more precise energy delivery, modular cartridges and vendor differentiation around depth targeting and treatment comfort — all of which influence physician preference and procedure throughput.
-
Clinical evidence as a moat. Vendors that can demonstrate reproducible fat‑reduction outcomes with robust safety data secure faster adoption among high‑volume aesthetic clinics and multispecialty centers.
-
Form factor and service model. Portability and lower capital barriers matter to medical spas and smaller clinics; scalable consoles with high throughput appeal to hospital systems and larger aesthetic centers. The consumables and service revenue model—cartridges, maintenance, training—often determines lifetime value.
Representative competitors profiled in the report include:
-
Liposonix (historical: Hologic) — historically notable for early FDA‑cleared HIFU abdominal fat reduction systems; this product line is no longer commercially available for new purchases, but its legacy data continues to inform clinical expectations and reimbursement discussions.
-
Ulthera (Merz Aesthetics) — a leader in skin lifting and tightening that has extended its clinical scope into body contouring; regulatory progress in the US has broadened indication potential and altered competitive positioning.
-
InMode — an aggressive innovator in platform features and transducer engineering, with recent product launches that raise the bar on efficacy and treatment speed for body contouring applications.
-
Hironic — a regional specialist with strong CE‑mark presence and iterative product improvements focused on depth penetration and cartridge innovation.
Recent industry moves highlighted in our Intelligence Brief include a late‑2024 product launch that improved transducer performance, a mid‑2024 US regulatory clearance expanding indications for submental fat, and CE‑Mark renewals combining upgraded cartridges for deeper targeting. Each of these events has measurable impact on buyer preference and competitive runway; the full report maps their commercial implications by quarter.
Regulatory and reimbursement levers that shape adoption
Two non‑market variables disproportionately influence near‑term adoption: regulatory clearance and reimbursement policy. In the US, HIFU lipoplasty products are governed by 510(k) pathways for devices demonstrating safety for non‑invasive fat ablation within defined depth ranges; in the EU, MDR Class IIb compliance and post‑market surveillance requirements create both a compliance cost and a competitive barrier. On the payer side, the existence of an established CPT code that specifically covers HIFU lipoplasty materially improves revenue visibility for clinic economics and investment appraisals. Our report quantifies how changes in reimbursement levels and code acceptance alter adoption curves and capex payback periods for typical buyer archetypes.
Strategic recommendations for 2026 — a pragmatic playbook
-
For device OEMs: Prioritize clinical programs that unlock high‑value indications and reduce time‑to‑reimbursement approval. Invest selectively in transducer IP and treatment‑planning software that enable differentiated clinical claims.
-
For investors: Target bolt‑on opportunities that add consumable‑led recurring revenue or unique distribution channels in under‑penetrated markets. Use our scenario outputs to stress test valuation against regulatory and reimbursement shocks.
-
For clinic operators and hospital procurement: Negotiate bundled pricing that incorporates training, warranty and consumables to align incentives and minimize first‑case risks. Evaluate platform flexibility to future‑proof against shifting indications.
-
For distributors: Curate a hybrid service model that blends capital financing, clinician training and outcomes reporting as a value prop to reduce procurement friction.
Risks and leading indicators to watch
-
Regulatory tightening or new guidance on energy‑based devices could raise compliance costs and slow new launches. Watch for formal agency communications and key 510(k) precedents.
-
Reimbursement variability across payers remains the primary adoption gating factor. Track large payer coverage decisions and any systematic changes in valuation of aesthetic procedures.
-
Competitive displacement from adjacent modalities (cryolipolysis, injectables, radiofrequency) could compress margins and force price competition; monitor clinical head‑to‑head data and promotional dynamics.
How PW Consulting’s report accelerates execution
This study is built to be operational: alongside narrative analysis we deliver a model workbook, an executive dashboard of trigger metrics, negotiation playbooks and a short‑list of acquisition targets mapped to strategic objectives. For leadership teams preparing 2026 budgets, the report converts the market’s aggregate growth trajectory — from a 2025 base of roughly USD 530 million toward nearly USD 910 million by the end of our 2032 horizon under the base forecast — into a set of prioritized, budget‑ready investments and contingency plans.
We intentionally present high‑level market momentum and competitive dynamics here while preserving the granular segmentation tables, channel economics and company‑level share analytics for the full report. Those detailed exhibits are where operating teams will find the exact inputs required for financial modelling, partner selection and procurement negotiation.
Next steps
PW Consulting is scheduling briefings for leadership teams that want a tailored interpretation of how 2026 scenarios affect their P&L and roadmaps. Access to the complete report — including detailed segmentation, regional deployment maps and vendor share matrices — is available on our website. For decision‑makers preparing capital allocation or clinical evidence strategies this quarter, the analysis provides a condensed, actionable foundation to inform investments that capture leadership positions as the HIFU lipoplasty market scales.
For detailed analysis of this topic, please visit the official page: Worldwide High-Intensity Focused Ultrasound (HIFU) Lipoplasty Devices Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com