

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Worldwide 3D AOI Equipment for PCBs to Grow from USD 1,100 Million in 2025 to USD 2,312.74 Million by 2032 at an 11.2% CAGR

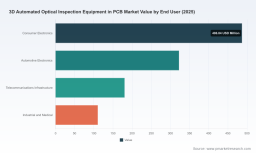
Worldwide 3D Automated Optical Inspection (AOI) Equipment in PCB Market — Strategic Outlook for 2026
Executive Overview
PW Consulting’s latest market intelligence briefing on the Worldwide 3D Automated Optical Inspection (AOI) Equipment in the PCB market equips board-level manufacturers, equipment OEMs, and strategic investors with an operational playbook for decisions in 2026. The market has evolved from a niche, inspection-centric toolset into a mission-critical pillar of high-reliability PCB production. Our base-year assessment (2025) and forward-looking model (2026–2032) show robust expansion driven by increasing component density, regulatory tightening on measurement accuracy, and the rising cost of defect escape in semiconductor-intensive assemblies. The model projects a compound annual growth rate (CAGR) of 11.2% over the forecast period, underpinned by accelerating spend on 3D sensing, analytics, and inline process integration.
Mil Spec Cables Market
Why this matters for 2026 decision cycles
-
Capital allocation: With a 2025 market base and near-term uplift projected into 2026, decision-makers must prioritize AOI investments not only for defect detection but as a nexus for data-driven process control. Equipment budgets that treat AOI as “nice-to-have” risk higher rework and warranty costs as assemblies become denser and component sizes shrink.
Magnetically Controlled Shunt Reactors Market -
Supply-chain timing: Lead times for high-resolution camera modules and optics remain elongated (averaging months in late 2025). Procurement calendars and vendor selection strategies for 2026 must factor multi-quarter sourcing and dual-sourcing where possible.
Worldwide Higher Education Student Information Systems Software Market -
Regulatory compliance and certification: Updated industry standards in 2025 raised 3D height accuracy requirements to the micrometer scale for certain high-reliability applications. This compels upgrades to both hardware and validation regimes in OEM and EMS environments.
-
Trade and tariff sensitivity: Export controls and tariff regimes that emerged in 2025 have already altered geographic sourcing economics. Executives must model scenarios in which equipment availability or landed costs vary materially by region.
State of the Market — A data-informed snapshot
PW Consulting’s topline market model captures historical performance (2020–2025) and projects through 2032. The market demonstrates consistent expansion from the early 2020s into the mid-2020s as SMT densities and customer quality expectations rise. Our forecasts indicate continued steady growth into the latter half of this decade, with market sizing and revenue trajectories offering clear guardrails for capacity planning and R&D prioritization. To preserve the tactical advantage of our subscribers, granular regional and end-market splits are available in the full report; summary commentary here intentionally refrains from disclosing segmented figures.
Competitive Landscape — What leading suppliers are doing
The market exhibits a moderate-to-high level of concentration at the top, with the top three and five suppliers collectively representing the majority of industry revenue — a dynamic that shapes competitive strategy and supplier negotiations. Key market participants continue to differentiate through sensor innovation, AI-enabled defect classification, and platform modularity. Notable trends among leading players include:
-
Koh Young Technology (Seoul) — maintains leadership with high-throughput true-3D imaging platforms and ongoing AI enhancements. Recent product introductions demonstrate a focus on throughput without sacrificing the finer height/detail resolution demanded by next-generation SMT assemblies.
-
CyberOptics Corporation (Minneapolis) — prioritizes multi-reflection suppression and fine-pitch capability, expanding support for ultra-small components and pushing inspection performance at the pixel and signal-processing level.
-
Viscom AG (Hannover) — targets high-volume HDI board lines with sensor and optics improvements that focus on resolution gains and repeatability for large-line deployments.
-
Test Research, Inc. (TRI) (Taipei) — blends AI analytics with inspection routines to extend the value of AOI into pre- and post-process decisioning, positioning inspection as a proximal control instrument rather than a quality gate alone.
-
SAKI Corporation (Tokyo) — continues to refine camera-mechanical architectures for microscopic height accuracy and advanced defect taxonomy, supporting stringent compliance footprints in regulated industries.
-
Mirtec Corporation (Oxford, CT) — integrates high-resolution imaging with laser profiling to provide comprehensive post-reflow analysis and traceable measurement outputs.
-
Nordson Test & Inspection (Carlsbad) — emphasizes hybrid inspection platforms that combine AOI with X-ray and automated handling to serve high-mix/low-volume lines where flexibility is valued.
Recent vendor moves and implications
-
Several vendors launched incremental hardware updates and AI-driven feature sets through 2025–2026. These moves signal a market phase where differentiation is squeezed between sensor fidelity and software-driven false call reduction.
-
Certification updates and trade-related rulings in 2025 pushed equipment vendors to adapt firmware, validation suites, and distribution strategies — an operational headache but also an entry point for service-led revenue streams (calibration, compliance-as-a-service).
Operational and strategic guidance included in the report
The full PW Consulting report is structured as an operational toolkit for 2026 decision-makers, combining quantitative forecast models with executable guidance. Core deliverables include:
-
Bottom-up and top-down forecasting engines with adjustable assumptions (component availability, tariffs, and installation rates) to run customized sensitivity analyses for capital planning.
-
Vendor scorecards and a capability matrix that cross-reference throughput, resolution, false-call rates, and service footprint — enabling OEMs and EMSs to select equipment aligned to product mix and quality targets.
-
Implementation playbooks for staged AOI rollouts, including sample KPIs, expected yield impacts, and recommended integration points with MES and SPC systems.
-
ROI and break-even models tailored to different line profiles (high-volume, high-mix, and high-reliability), including post-installation scenarios for ongoing software and calibration costs.
-
M&A and partner-mapping intelligence — identifying technology gaps and consolidation opportunities that could meaningfully change supplier dynamics within the forecast window.
Key risks and scenario planning for 2026
Our scenario framework identifies three high-impact vectors that should inform 2026 planning:
-
Supply shock continuation — protracted lead times for high-resolution camera modules and optics could force prioritization of critical lines and deferral of capacity expansion. Dual-sourcing and strategic inventory policies are recommended mitigations.
-
Regulatory tightening — stricter measurement accuracy requirements have immediate implications for calibration frequency, traceability documentation, and capital refresh cycles. Companies should budget for compliance-driven upgrades.
-
Trade and tariff volatility — export controls and targeted tariffs can shift landed-cost economics by region and supplier. Scenario planning should evaluate on-shore vs. off-shore sourcing trade-offs and the commercial impact of potential supply interruptions.
Practical recommendations for 2026 roadmap decisions
-
Adopt a layered procurement strategy: combine immediate purchases for high-impact lines with leased or subscription-based options for experimental or low-volume deployments.
-
Invest in software and analytics: AI-driven false-call reduction and closed-loop process control deliver outsized ROI compared to incremental hardware improvements in many line types.
-
Prioritize modularity and upgradeability: select platforms that allow sensor and compute upgrades without full capital replacement to future-proof against evolving component standards and accuracy rules.
-
Embed compliance into procurement contracts: include calibration SLAs and regional service assurances to protect throughput and quality targets in tariff-impacted or sensor-constrained scenarios.
How to use this intelligence
PW Consulting’s report is designed as a decision-support pack for procurement teams, operations leaders, and corporate development groups as they enter 2026 planning cycles. Readers can use the interactive models to:
-
Quantify the financial impact of different investment timelines and vendor mixes.
-
Stress-test sourcing strategies under varying tariff and export-control regimes.
-
Benchmark vendor performance against validated field metrics and supplier concentration indices.
Conclusion — The strategic inflection point
AOI for PCB inspection is no longer purely tactical. It is central to how manufacturers protect margins, manage risk, and accelerate time-to-insight in complex assembly environments. With a strong mid-term growth outlook (CAGR ~11.2%) and clear operational pressures from component supply, regulatory change, and trade dynamics, 2026 will be a year where choices about AOI architectures, vendor partnerships, and data strategies materially affect competitiveness.
PW Consulting’s full market study delivers the granular segmentation, vendor benchmarking, and downloadable financial models required to translate these trends into executable 2026 programs. For the complete dataset, regional and end-market breakdowns, and the downloadable scenario engines, please consult the PW Consulting report landing page.
For detailed analysis of this topic, please visit the official page: Worldwide 3D Automated Optical Inspection Equipment in PCB Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com