

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting Forecasts 5.45% CAGR for Worldwide Fabric Flame Retardancy Testers Market in 2026–2032

Worldwide Fabric Flame Retardancy Testers Market — Strategic Outlook for 2026 Decision-Makers
PW Consulting’s new market intelligence brief on the Worldwide Fabric Flame Retardancy Testers Market synthesizes operational detail, standards alignment, and strategic foresight into a single advisory designed to inform capital allocation, product strategy, and regulatory readiness in 2026. Built on a 2020–2025 historical base and a 2026–2032 forecast horizon, the report quantifies a steady expansion driven by regulatory rigor, diversified end‑use requirements, and incremental technological upgrades. At a compound annual growth rate (CAGR) of 5.45% across the forecast window, the market’s total size grows meaningfully from a 2025 baseline to our 2032 scenario, underlining a constrained but attractive growth profile for suppliers, laboratory operators, and vertically integrated OEMs.
Worldwide Antireflection Film Market
Why this report matters for 2026 strategic choices
-
Actionable investment lens: The market’s mid-single-digit CAGR signals that 2026 is best approached as a year for selective investment — prioritizing automation, modular product lines, and service expansion rather than broad greenfield capacity plays.
Worldwide Secure DNS Software Market -
Regulatory-first product design: With amendments and clarifications to core standards surfacing in recent years, test equipment vendors and buyers must treat standards alignment as product functionality, not a compliance afterthought.
Worldwide Document Generation Software Market -
Cost and supply chain sensitivity: Upstream material and logistics volatility requires instrument manufacturers and test-house operators to adopt hedging and alternate sourcing strategies; capital expenditure plans should bake in modest raw‑material cost premiums and lead‑time cushions.
-
Aftermarket as a margin lever: Service contracts, calibration, and software updates are the fastest path to higher, more predictable margins in a market where hardware replacement cycles are measured in years.
Macro picture — measured, steady growth with pockets of premiumization
PW Consulting’s topline market model shows growth from an estimated USD 115.8 million in 2025 to USD 167.89 million by 2032 under our central scenario. The near‑term uptick to 2026 (we estimate the market at roughly USD 122.94 million that year) reflects pent‑up CAPEX refresh cycles in testing labs and compliance investments driven by product safety awareness and regional standardization programs. Over the longer horizon, earnings will increasingly be driven by feature differentiation (automation, data capture and analytics, repeatability) and service revenue rather than pure hardware unit volumes.
Importantly, the market is neither a pure commodity nor a narrowly proprietary domain — it is a specialized instrumentation sector where standards credentials, local support, and proven repeatability often trump headline price. That dynamic creates defensible niches for companies that pair product breadth with strong standards alignment and an efficient aftermarket organization.
Core report contents — what executives and procurement teams will use
-
Validated market sizing and forecast model (2020–2032): detailed topline trajectory and scenario‑based sensitivity testing to stress test CAPEX decisions under high/low regulatory and raw‑material outcomes.
-
Standards and compliance matrix: crosswalk of global standards (e.g., ISO 6940/6941, ISO 15025, ASTM series, 16 CFR 1610, NFPA 701, BS5852, EN71-2, ECE requirements), with mapping of which instrument features and test configurations are required for each regime.
-
Commercial and technical product taxonomy: canonical definitions for vertical, horizontal, angled and multi‑purpose testers, with engineering checklists for automation, instrumentation accuracy, calibration cycles, and sample handling.
-
Vendor benchmarking and go‑to‑market playbooks: comparative profiles across product breadth, geographic service footprint, standards certification, and aftermarket capability — with acquisition target screening criteria and valuation multiples tailored to this industry.
-
Procurement-ready decision aids: CapEx/OpEx templates, total cost of ownership calculators, and a five‑year replacement cycle model that reflects both hardware depreciation and software/service monetization patterns.
-
Supply-chain and raw-material risk assessment: scenario planning for cost shocks, supplier concentration, and logistics interruptions, together with mitigation options including strategic stocking, dual sourcing, and localized assembly.
-
Use-case playbooks: tailored recommendations for laboratories, textile manufacturers, automotive suppliers, and public safety institutions on test strategy, lab layout, sample throughput, and staffing.
Competitive landscape — capability clusters and strategic implications
The market exhibits a moderate level of concentration. The top three suppliers account for a material minority share of industry revenues, and the top five expand that position further — an indicator that leading vendors have carved out recognizable footprints without creating impenetrable barriers for well‑capitalized challengers. This structure favors both focused incumbents and new entrants who pair technical differentiation with credible service networks.
-
DaRong (China) — breadth and standards authorship: DaRong offers an extensive series of fabric flame retardancy testers, including vertical, horizontal, 45‑degree and specialized units for niche applications. Significantly, the company has participated in drafting national standards, which confers technical credibility and accelerates market access in jurisdictions that recognize those standards. For buyers, that translates to a vendor that can bundle compliance guidance with hardware — an advantage in markets where local accreditation is a purchase determinant.
-
AVENO Technology (China) — diversified application coverage: Aveno’s portfolio spans automatic vertical and horizontal testers, curtain‑specific propagation setups and dedicated modules for furniture and children’s sleepwear standards. Their positioning is attractive to OEMs and test houses seeking end‑to‑end test suites rather than point tools.
-
GESTER (China) — specialty devices with laboratory ergonomics: Gester’s hanging fabric burning solutions target curtain and hanging fabric testing per NFPA protocols, combining stainless steel construction with operator‑friendly interfaces. Its competitive strength lies in lab‑grade engineering tailored to repeatability and throughput.
-
TESTEX (China) — programmable multi‑purpose testers: Testex supplies multi‑purpose units with PLC control and optical scanning for vertical burn testing across an array of materials. That engineering focus on automation and measurement integration is a useful reference point for test labs that need robust data capture and traceability.
-
FYI Tester (China) — standards breadth: FYI’s assortment includes UL 94 variants and multiple angular testers, making the firm a practical supplier where cross‑standard testing is a procurement requirement.
-
SDL Atlas (USA, with regional operations) — institutional reputation and solution integration: SDL Atlas brings an established brand to markets that value long‑standing test methodologies and strong service support for automotive interior materials and other regulated segments. Their presence underscores the defensive advantage of recognized international brands in certain procurement cycles.
Regulatory and standards dynamics — operational mandates for 2026
Regulatory plumbing will remain the primary demand driver. Notable recent developments include the U.S. CPSC’s amendment to the Standard for the Flammability of Clothing Textiles (16 CFR 1610), effective in 2024, which broadened permissible equipment while preserving the underlying flammability class architecture. Meanwhile, ASTM D6413 and ISO 15025 continue to define test procedures for vertical flame resistance and flame spread, respectively. For equipment vendors and purchasers, these developments mean two things: first, product roadmaps must maintain compatibility with the established test protocols; second, incremental changes to accepted equipment lists can create short windows of procurement opportunity as labs upgrade or replace instruments to stay compliant.
Manufacturing economics and supply‑side noise
Instrument builders should factor recent raw‑material and input price shifts into product pricing and inventory strategy. Movements in steel and aluminum markets, along with transportation cost variability, have compressed manufacturer margins in 2024–2026 and can intermittently influence lead times. Our recommended approach for vendors is pragmatic: prioritize modular designs that permit substitution of higher‑cost components without full redesign, and build service and calibration contracts that smooth revenue volatility arising from hardware pricing pressure.
Strategic recommendations — what to do in 2026
-
Buyers (labs, OEMs): Adopt a lifecycle procurement framework that values calibration, software compatibility and local support as highly as upfront price. Consider multi‑year service agreements to stabilize operating costs and ensure continuity of accredited testing.
-
Vendors: Invest selectively in automation and SaaS-enabled data capture; bundle hardware with analytics and compliance workflows to convert one‑time sales into recurring revenue streams. Strengthen standards‑based credentials and invest in local calibration centers where competitive differentiation is still decided at the service desk.
-
Private equity and M&A players: Target acquisition candidates with defensible service footprints, multistandard product lines, and pipeline opportunities for aftermarket expansion. The moderate concentration in the market creates roll‑up economics if integration can rationalize calibration and spare parts operations.
-
Policy and public labs: Prioritize interoperability and traceability. Funding that supports interoperable data standards will deliver outsized public‑interest benefits by accelerating cross‑jurisdictional acceptance of test results.
What we intentionally withhold — and why
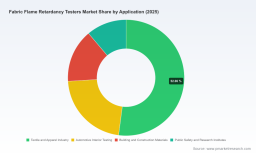
In keeping with the “trailer” principle of this briefing, PW Consulting is deliberately omitting granular regional, application and type‑level share tables from this summary. These subsegment details are central to tactical procurement and M&A execution — and are provided in full within the complete report. Executives and teams that need market split matrices, detailed regional demand drivers, product‑level pricing curves and the vendor scorecard should consult the full dataset and model available from PW Consulting.
Final note — preparing for 2026 with clarity
For companies navigating the fabric flame retardancy testing market in 2026, the strategic challenge is clear: balance disciplined, standards‑aware product development with a service‑first commercial model. The market is neither hyper‑rapid nor static; it rewards those who invest in repeatability, data, and local service. PW Consulting’s full study provides the market‑grade intelligence required to underwrite those investments with confidence. Use 2026 to build the foundations for service scale and standards leadership — and to position your organization for the steady, predictable expansion we forecast through 2032.
For detailed analysis of this topic, please visit the official page: Worldwide Fabric Flame Retardancy Testers Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com