

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Worldwide Smartphone Panel Market Poised to Grow at a 5.19% CAGR (2026–2032) as AMOLED and Flexible Panels Dominate

Worldwide Smartphone Panel Market — Strategic Briefing for 2026 Decision-Makers
Executive summary
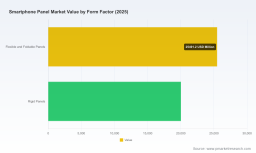
PW Consulting’s new Worldwide Smartphone Panel Market report (base year 2025, historical window 2020–2025, forecast 2026–2032) equips senior executives and investment committees with the forward-looking intelligence needed to make high-consequence decisions in 2026. The addressable market for smartphone panels reached USD 45,520 Million in 2025 and, under our central forecast, expands at a 5.19% CAGR to roughly USD 64,910 Million by 2032. Market concentration remains high at the top of the supplier pyramid, underscoring both strategic risk and opportunity for entrants and incumbents alike.
Ball Coagulometer Market
Why this report matters for 2026 strategy
2026 is a hinge year for the smartphone panel ecosystem. A confluence of technology inflection points (accelerating AMOLED adoption and the maturing of flexible/foldable form factors), raw-materials geopolitics (concentration in critical conductive and specialty substrates), and supply-side capacity reconfigurations is forcing executives to choose between defensive hedging and offensive market capture. The report is designed as an operational playbook — not merely a set of macro forecasts — so that product, procurement, corporate development, and capital allocation teams can translate directional insight into executable moves in the coming 12–24 months.
Human Skin Model Market
Key thematic findings (high-level)
-
Steady market expansion with selective structural winners: The smartphone panel market is forecast to grow at a mid-single-digit compound annual rate (5.19% CAGR) through 2032, driven by replacement cycles at the premium end, increased penetration of AMOLED across mid-range devices, and incremental ASP uplift from higher-value flexible and foldable panels.
Worldwide Career Management Software Market -
AMOLED ascendance and form-factor premiumization: Our analysis confirms an accelerating shift from legacy LTPS/a‑Si LCD architectures to AMOLED technologies, with flexible and foldable designs driving above-market value capture for vendors that can guarantee yield and durability at scale.
-
Supply concentration and strategic bottlenecks: The top-tier suppliers control a disproportionate share of premium panel supply — a structural dynamic that creates both supply-side pricing power and elevated procurement risk for OEMs that rely on a small set of sources for high-end components.
-
Raw-materials and regulatory uncertainty as decision multipliers: Control of critical processing and materials (e.g., indium and specialty substrates like polyimide and UTG) and potential policy actions (including import controls or tariffs) materially affect the timing and location of capacity investments and inventory strategies.
Competitive landscape — what we mapped (and why it matters)
Our competitor map synthesizes primary interviews, technology audits, and plant-level capacity tracking. The firms we profile span the full spectrum of strategic positions: technology leaders in premium flexible OLED and LTPO, high-volume producers with aggressive cost curves, and regional specialists focused on entry-to-mid segments.
-
Samsung Display — technology leadership in premium AMOLED and foldables, demonstrating continued investment posture aligned with strategic OEM programs and next-generation privacy/slidable concepts showcased in early 2026.
-
LG Display — focused on advanced flexible OLEDs and selective wins in flagship displays; provides an alternative premium supply line for OEMs seeking dual-sourcing for critical programs.
-
BOE Technology Group and Chinese suppliers — volume leadership across panel types, rapid activation of higher-generation lines, and increasing ability to supply both mid- and higher-tier devices; their capacity plays are reshaping global sourcing economics.
-
TCL CSOT, Tianma, Visionox, AUO, Innolux, JDI, Sharp, HannStar, and emerging players — a heterogeneous set of regional specialists and technology adopters. Each has distinct positions in price, yield, and specialty capabilities (e.g., small-to-medium AMOLED, generation-specific LCD economics, or advanced UTG process expertise).
We quantify relative competitive positions across technology readiness, scale economics, and supply reliability in the report’s strategic matrices — but to preserve our “trailer” approach we deliberately summarize rather than publish the full segment matrices here.
Recent industry developments that should change 2026 plans
-
Capacity re-allocations and investment signaling: Recent public disclosures and industry reporting indicate new capacity deployments and capacity reviews by major suppliers targeting foldable OLED and Gen‑8-plus lines. These moves affect available commercial slots and should inform negotiation timing and contract durations for OEM procurement teams.
-
Shipment and technology mix shifts: Independent market trackers project continued unit growth in 2026 with rising AMOLED penetration. That mix shift changes supplier bargaining leverage and means that securing AMOLED volume commitments early will be essential for brands launching premium-leaning portfolios.
-
Raw-material geopolitics and policy overlays: Concentration in the processing of critical minerals and active national investigations into processed mineral imports create plausible scenarios where supply chains are disrupted or re-priced. Procurement and legal teams must incorporate scenario-based duties and sourcing permutations into 2026 spending plans.
-
Product engineering advances: Demonstrations of novel UX attributes (privacy, slidable displays) and device-layer innovations (S-stripe high-subpixel counts) signal that product differentiation is migrating from mere pixel counts to integrated display capabilities — reinforcing the need for closer ODM/OEM-panel supplier co-development.
What the PW Consulting report contains (practical, applied deliverables)
We built the report to be a toolset, not just a narrative. Key operational modules include:
-
Market model (2020–2032) with scenario toggles: base, upside (accelerated AMOLED substitution), and downside (material/regulatory shock) views; downloadable datasets in Million USD and unit-equivalent constructs.
-
Supplier playbooks: capability maps, risk matrices, white-space opportunities for dual-sourcing, and contract-clause checklists for yield/quality penalties and capacity guarantees.
-
Supply-chain stress tests: supplier concentration analyses, critical-material exposure scoring (e.g., indium, polyimide, UTG), and contingency levers for inventory and nearshoring.
-
Investment decision frameworks: timing models for line activation, IRR sensitivity to cycle-time improvements and yield uplift, and an M&A playbook for acquiring or partnering with regional capacity.
-
Go‑to‑market and product roadmap tools: segmentation strategies that align panel choices to price bands and differentiation levers (durability, refresh, power efficiency, subpixel engineering).
Each module includes actionable templates and decision gates designed for immediate incorporation into quarterly planning cycles and capex approvals.
Strategic implications and recommendations for 2026
-
Procurement: Move from annual spot buys to multi-year, optioned agreements with capacity guarantees for AMOLED and flexible panels. Layer contracts with performance-based clauses and establish alternative supply lines for critical display types.
-
Product and engineering: Prioritize co-development arrangements with panel suppliers early in the product cycle for any device that incorporates flexible or advanced subpixel designs; factor in substrate procurement lead times for polyimide and UTG.
-
Finance and investment: Re-assess capex commitments through the lens of policy risk and concentration. For companies considering upstream exposure, combine brownfield expansions with strategic minority stakes in regional suppliers to hedge geopolitical uncertainty.
-
Risk and compliance: Implement scenario planning for trade-policy shocks (e.g., tariffs or export controls) and stress-test the impact on landed costs, time-to-market, and warranty exposure for premium devices.
-
M&A and partnerships: Target capability acquisition (e.g., UTG process expertise or Gen‑8 AMOLED lines) that shortens the path to product differentiation while mitigating single-supplier dependency.
How to use this report in your 2026 planning cycle
We recommend a three-step deployment for executives:
-
1) Immediate (0–3 months): Use the report’s supplier playbooks and risk matrices to lock down critical panel allocations for 2026 product programs and to execute contingency supply agreements for high-dependency components.
-
2) Tactical (3–9 months): Integrate the scenario market model into quarterly forecasts, adjust product roadmaps to reflect AMOLED availability and premium-form-factor economics, and begin preparatory steps for any mid-cycle engineering shifts necessitated by supplier capabilities.
-
3) Strategic (9–18 months): Revisit capex and M&A pipelines in light of realized market shifts, and pursue selective investments or partnerships to secure long-term access to advanced substrates and high-yield AMOLED capacity.
Final note — what you will not find in this press briefing
In keeping with our "trailer" principle, this release highlights the report’s strategic value and core insights but intentionally omits granular segment-by-segment numerical tables and proprietary supplier scorecards. Those detailed breakouts — including regional and application segmentations, line-level capacity schedules, and downloadable datasets in Million USD — are available exclusively in the full report and its accompanying data appendix.
Next steps and how to access the full intelligence
For procurement leaders, product heads, corporate development teams, and private investors evaluating exposure to the smartphone display value chain in 2026, the full Worldwide Smartphone Panel Market report provides the empirical foundations and executable toolset that will materially improve decision quality. Visit PW Consulting’s report page to obtain the full dataset, model files, and bespoke advisory packages tailored to your company’s risk profile.
For detailed analysis of this topic, please visit the official page: Worldwide Smartphone Panel Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com