

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Worldwide SGP Interlayer Films Market Set to Expand at a Robust 8.0% CAGR (2026–2032)

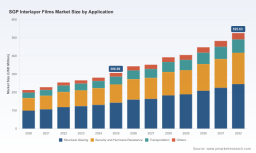
Worldwide SGP Interlayer Films Market — Strategic Outlook for 2026 Decision-Making
PW Consulting’s latest Worldwide SGP (SentryGlas®-type ionoplast) Interlayer Films Market report (base year 2025; forecast 2026–2032) provides a focused, decision-ready playbook for executives evaluating CAPEX, sourcing, M&A and product strategies as the market moves into its next growth phase. After a steady expansion from roughly USD 212 million in 2020 to approximately USD 307 million in 2025, the market is projected to grow at a compound annual growth rate (CAGR) of about 8.0% across the 2026–2032 forecast window. That trajectory — and the structural drivers beneath it — create concrete windows for market entry, consolidation and premiumization in 2026 and beyond.
Worldwide Acoustical Analysis Services Market
Why this report matters for 2026
-
Timing: 2026 is the first post-base year year of the report’s forecast period and the pivotal year for many multi-year capital and sourcing decisions initiated in 2024–2025.
AI Firewalls Market -
Actionability: the report translates technical glazing trends into procurement levers, price-sensitivity thresholds and product roadmaps that procurement, product and strategy teams can implement within 12–18 months.
Automotive RTK GNSS Module Market -
Risk-adjusted planning: with regulatory shifts and raw-material volatility front of mind, the report offers scenario-based financial impacts and mitigation pathways tailored to 2026 budget cycles.
Market dynamics that will shape 2026 decisions
-
Demand drivers: Structural glazing growth (architectural safety, hurricane- and blast-resistant systems) continues to underpin premium SGP adoption. High-strength ionoplast films are increasingly specified where load-bearing performance, post-breakage clarity and thinner glass laminates yield design or cost advantages.
-
Raw-material and input risk: Feedstock pressure is tangible — spot prices for key resins moved materially in late 2024 amid monomer shortages (reported spot increases ~8% to about USD 2.45/kg). Procurement teams must model input-cost pass-through and two-way price clauses for 2026 contracts.
-
Regulatory and compliance constraints: In Europe, the Construction Products Regulation (CPR) has elevated test and marking requirements (CE marking plus pRAVE testing for post-breakage vision clarity in load-bearing contexts). REACH restrictions on certain plasticizers further favor ionoplast-based SGP solutions as non-PVC alternatives — a structural compliance advantage for market incumbents and new entrants that align early.
-
Trade and policy friction: Tariff measures (e.g., US Section 301 duties impacting imports from specific origins) remain a near-term cost factor into 2025 and influence sourcing decisions through 2026. Supply-chain localization or near-sourcing strategies can neutralize tariff exposure but require lead time and capital.
-
Concentration and competitive dynamics: The SGP interlayer market is highly concentrated (top-three and top-five shares are meaningfully high), which confers pricing power to incumbent technology owners while making scale and IP access decisive in deal economics.
Competitive landscape — what the leading players signal for 2026 strategy
-
Trosifol (Wiesbaden, Germany): As the primary commercial face for the SentryGlas® family, Trosifol continues to push value-add product variants (e.g., colored expressions and UV-stable decorative interlayers). Their product launches indicate a shift from purely technical selling to design-led specification capture — an important trend for manufacturers and façade designers.
-
Kuraray (Tokyo, Japan): The technology originator and manufacturer of ionoplast interlayers retains muscle in ultra-thick film manufacturing and certification pathways. Recent certification updates for overhead glazing signal a strategic move to expand application envelopes — a cue for suppliers and fabricators to secure certified supply channels early.
-
Everlam (Halen, Belgium): Capacity expansions in Europe demonstrate how regional demand for structural glazing is tangibly translating into higher lamination throughput. Regional capacity moves are a leading indicator for project pipeline strength and a warning for procurement teams about tightening lead times.
-
Glastrotech (Dallas, TX, USA): As an authorized distributor/processor focused on North America, Glastrotech’s role underlines the importance of downstream integration (pre-laminated panels, supply bundling) to win façade and glazing spec cycles.
Recent product launches, certifications and capacity investments from these players collectively illustrate three strategic realities for 2026: (1) specification mobility toward differentiated SGP variants, (2) certification as an access barrier for premium applications, and (3) regional capacity moves that will govern lead times and margin capture.
Strategic imperatives for executives in 2026
-
De-risk supply: Lock flexible supply with staged contracts that combine floor-price guarantees with indexed pass-through for resin-linked feedstocks. Consider strategic offtake agreements with capacity providers in target regions to neutralize tariff exposure and logistical risk.
-
Prioritize certification and testing early: Where projects require overhead, seismic or post-breakage clarity performance, certification lead times are non-trivial. Allocate budget in 2026 to secure necessary testing (e.g., pRAVE or equivalent) to avoid specification hold-ups.
-
Capture value through product adjuncts: Innovations such as colored interlayers and ultra-thick laminates are becoming procurement differentiators. Roadmap R&D or partnership investments that allow moving up the value chain rather than competing solely on price.
-
Explore consolidation selectively: High market concentration favors bolt-on M&A for mid-size fabricators and distributors seeking scale. Our scenario analysis identifies acquisition targets that improve regional coverage and lamination throughput without diluting margins.
-
Sustainability as a competitive moat: Ionoplast SGP’s non-PVC profile aligns with REACH and green-building requirements. Embed lifecycle and EPD-ready disclosures into product launches to increase spec wins on sustainability criteria.
How to use PW Consulting’s report in your 2026 planning cycle
-
Executive summary + one-page decision trees: Use the condensed playbooks to brief boards on capital prioritization, contract sizing and timeline trade-offs.
-
Scenario models: Run our three base scenarios (conservative, central, accelerated) to stress-test EBITDA under different raw-material and tariff permutations. Each scenario includes sensitivity tables that map margin exposure for typical lamination and fabrication cost structures.
-
Procurement playbook: Deploy the vendor short-listing matrix and negotiation checklists to shorten sourcing cycles and establish contingency inventories for 2026 project pipelines.
-
M&A and partnership filter: Apply our target-scoring framework to shortlist acquisition or joint-venture candidates that deliver capacity, certification or geographic coverage aligned with your 2026 objectives.
-
Regulatory compliance checklist: Use the CE/pRAVE and REACH alignment modules to ensure new product introductions meet regional acceptance criteria before tendering.
What the report contains — practical intelligence you can act on immediately
-
Five-year historical sizing and a line-by-line forecast to 2032, with scenario and sensitivity tables that translate market movements into P&L impact.
-
Commercial segmentation frameworks (application, end-user and regional lenses), supplier maps and buyer-supplier negotiation playbooks. Note: this news release intentionally omits granular split values; the full report contains the detailed segment and regional tables necessary for bid and investment models.
-
Supplier profiles and capability audits (technology, certifications, capacity, go-to-market), including strategic implication notes for each major player.
-
Technical annexes covering lamination tolerances, specification checklists for structural glazing and an abbreviated cost build-up for pre-laminated panels.
-
M&A pipeline analytics, synergy capture estimates and integration roadmaps for buyers targeting consolidation in 2026–2027.
Immediate next steps we recommend
-
For procurement leaders: initiate bilateral offtake and indexing clauses with qualified suppliers before mid-2026; run the report’s sensitivity model against your 2026 project list.
-
For product and engineering leads: align roadmaps with certification timelines; budget testing in Q1–Q2 2026 for any new laminated product families intended for the EU or overhead applications.
-
For corporate development teams: use our M&A filter to identify 2–3 high-fit targets for diligence by H2 2026, prioritizing capacity and regional access over marginal product breadth.
PW Consulting’s Worldwide SGP Interlayer Films Market report equips management teams with the forecasting fidelity, supplier intelligence and regulatory context necessary to make confident 2026 decisions. We deliberately present a high-level strategic view here to surface the critical levers; the full report provides the disaggregated tables, project-level forecasts and supplier scorecards required to convert strategy into signed contracts and executed transactions.
Learn more
To access the complete dataset, segmented forecasts, supplier dossiers and executable playbooks, visit the official report page or contact PW Consulting’s lead analyst team. The full report contains the granular tables and scenario workpapers that boards and deal teams will require to finalize 2026 budgets and negotiation mandates.
For detailed analysis of this topic, please visit the official page: Worldwide SGP Interlayer Films Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com