

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Worldwide Disposable Surgical Electrodes Market Poised for a 6.48% CAGR During 2026–2032

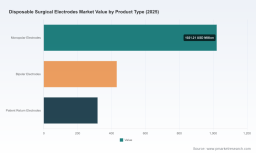
Worldwide Disposable Surgical Electrodes Market — Strategic Preview for 2026 Decision-Makers
Executive summary
PW Consulting’s latest market study on the Worldwide Disposable Surgical Electrodes market provides an evidence‑based foundation for executive decisions entering 2026. The global market is estimated at USD 1,770.45 Million in 2025 and, under the baseline scenario modeled in this report, is expected to expand at a compound annual growth rate (CAGR) of 6.48% over the 2026–2032 forecast window. By 2032, our top‑line projection reaches roughly USD 2,747.6 Million. These headline figures capture trajectory and scale; the body of our report dissects the commercial, regulatory and technology vectors that will determine winners and losers in the next planning cycles.
Algo Trading Software Market
Why this preview matters for 2026 strategic planning
-
Timing and resource allocation. With mid‑single‑digit CAGR and an accelerating shift to single‑use disposables in many surgical specialties, 2026 is a pivot year for investment timing – deciding whether to scale manufacturing capacity, pursue strategic partnerships, or prioritize product development for differentiated disposable technologies.
Wound Stator Shell for Electric Motors Market -
Portfolio design. The market’s growth levers differ between commodity electrodes and value‑added disposables (e.g., PTFE‑coated non‑stick tips, integrated return pads, or procedure‑specific designs). Our study helps leaders prioritize R&D and SKU rationalization without exposing proprietary segment tables in this preview.
Worldwide Integration Software as a Service Market -
Regulatory and go‑to‑market readiness. For firms targeting the U.S. market, the Class II GEI pathway and 510(k) expectations remain central. The report maps practical, compliance‑first pathways and the operational impacts of IEC 60601 series conformance, which are critical inputs to 2026 product launch calendars and CAPEX forecasts.
Key market dynamics shaping 2026 decisions
-
Moderate, sustained growth. The market’s projected CAGR of 6.48% reflects balanced demand drivers: continued surgical volumes in established specialties, incremental adoption in emerging procedures, and substitution of reusable items where clinical or economic rhetoric favors disposables.
-
Product innovation around surgical ergonomics and tissue interaction. Manufacturers increasingly deploy PTFE coatings and non‑stick surface engineering to reduce eschar and improve procedural efficiency—an important trade‑off when evaluating claims for clinical differentiation versus incremental cost.
-
Regulatory environment as a market gatekeeper. Disposable electrosurgical electrodes are typically regulated as Class II devices (product code GEI) in the U.S. and require 510(k) clearance, while IEC 60601‑1, ‑1‑2 and ‑2‑2 electrical safety standards frame global acceptance. Recent approvals in 2024–2026 demonstrate continued regulatory throughput but also underscore the need for robust bench and clinical substantiation.
-
Reimbursement and procurement variability. Electrosurgical consumables are billed under varying CPT codes and influenced by site‑of‑service payment differentials and hospital procurement policies. The commercial implications differ by channel: high‑volume group purchasing organizations (GPOs) push price pressure, while ambulatory surgery centers offer pockets of margin expansion when clinical value can be demonstrated.
-
Sterility and supply‑chain resilience. Sterile, single‑use electrodes are commonly EO gas sterilized and many cleared devices carry multi‑year shelf lives. Manufacturers must design packaging, sterilization workflows and supplier redundancy into 2026 production plans to mitigate regulatory holds and distribution disruptions.
Competitive landscape — what the market structure tells strategic buyers
The disposable surgical electrodes market shows moderate concentration. The top three global players account for roughly 42% of market value while the top five account for approximately 56%. This structure creates a strategic environment where scale delivers procurement leverage but meaningful niches still exist for specialty and regional suppliers.
-
Global incumbents and integrated portfolios. Established medtech majors (examples covered in our report) combine electrosurgical consoles with branded disposable electrodes and patient return systems. These firms pursue bundled value propositions—device‑plus‑consumable models that lock in recurring revenue and influence hospital capital purchase decisions.
-
Specialist and regional players. Companies focused on product specialization (e.g., microsurgical bipolar forceps, PTFE‑coated non‑stick electrodes, or disposable laparoscopic hooks) continue to capture clinical niches. These players can be attractive partners or acquisition targets for larger firms seeking fast access to differentiated IP or lower‑cost manufacturing footprints.
-
New entrants and regulatory momentum. Recent 510(k) clearances for single‑use electrodes and electrosurgical devices in 2024–2026 indicate ongoing entry at the product level. New approvals for dermatologic, arthroscopic and physical‑medicine applications point to adjacent growth corridors that incumbent portfolios may under‑penetrate.
Recent regulatory and product developments to watch
-
In 2024–2026 regulators have cleared a stream of single‑use electrosurgical devices, underscoring FDA expectations around electrical safety, sterilization validation and bench performance data.
-
IEC standard compliance remains non‑negotiable for cross‑market commercialization; our technical appendix details typical test matrices and harmonized evidence packages that shorten time‑to‑clearance when executed early.
-
Material science advances, notably PTFE coatings, are being adopted to reduce eschar and lower procedure times—an important clinical claim that can shift procurement conversations from price to outcome.
What the PW Consulting report delivers — practical, actionable modules
We designed the study as a working toolkit for commercial leaders, product managers and M&A teams. The full report includes:
-
A calibrated market sizing and forecasting model (2020–2032) with scenario toggles for policy, procedure volume and adoption elasticity—exportable to client models.
-
Segment playbooks: decision frameworks for product portfolio prioritization, SKU rationalization, and margin management (note: segment‑level tables and regional application breakdowns are reserved for report subscribers and the online interactive dashboard).
-
Regulatory roadmaps: step‑by‑step 510(k) and IEC compliance checklists, typical test plans, and recommended clinical/bench evidence packages for common disposable electrode categories.
-
Commercial & reimbursement intelligence: mapping of CPT coding implications, payer sensitivities, and procurement negotiation levers by care setting.
-
Competitive profiles: concise fact‑sheets on leading global and regional players, capability matrices, and acquisition targets aligned to strategic themes (scale, differentiation, cost leadership).
-
Supply‑chain and manufacturing playbook: guidance on sterilization partner selection, shelf‑life optimization, and cost modeling for PTFE and other specialty coatings.
Strategic recommendations for 2026 (practical next moves)
-
Define your commercial posture. Decide whether to play scale‑and‑supply (competing on cost and footprint), differentiate by clinical claims (coatings, ergonomics, procedure specificity), or pursue a hybrid model with selective premium SKUs.
-
Prioritize regulatory and technical investments early. Building IEC/510(k) evidence during development reduces time‑to‑market and prevents last‑minute rework that can delay launches into critical fiscal windows.
-
Lock down sterilization and critical‑materials supply contracts. For manufacturers scaling disposable production, EO sterilization capacity and PTFE suppliers are common bottlenecks; secure multi‑year agreements with contingency clauses.
-
Leverage partnerships for channel entry. For market entrants, OEM partnerships, distribution alliances with established clinical sales forces, or tuck‑ins with regionally focused firms are faster routes to adoption than greenfield sales builds.
-
Use value messaging to offset price pressure. Demonstrable OR time savings, reduced instrument changeover, and lower complication rates are the commercial narratives that move GPOs and hospital formulary committees.
How strategic buyers, investors and product teams should use this preview
Think of this preview as a strategic grade card: it quantifies market direction and highlights the structural choices that will determine relative performance through 2026 and beyond. For capital allocation, prioritize investments that either meaningfully lower unit cost at scale or clearly raise clinical value per procedure. For M&A teams, target specialty manufacturers with exportable IP, validated sterilization workflows, and clear regulatory dossiers—these assets compress commercialization timelines.
Accessing the full report and why we withhold certain tables here
In keeping with the “trailer” principle, this release deliberately demonstrates analytic depth and actionable guidance while withholding detailed segment‑by‑region and procedure‑level tables that are included in the full report and interactive dashboard. Those segment breakdowns and downloadable forecast sheets are critical to transaction diligence and in‑market pricing decisions; they are available on our report webpage and through PW Consulting subscription services.
Final note — immediate tactical checklist for 90‑day planning
-
Validate product compliance plans against IEC 60601 series and draft a 510(k) submission timeline if targeting the U.S. in 2026.
-
Map out sterilization capacity options and secure conditional MOUs with at least two providers.
-
Run a quick margin simulation comparing PTFE‑coated premium SKUs versus commodity electrodes to inform SKU rationalization.
-
Engage potential distribution partners in priority markets where clinical adoption curves are favorable.
For the full dataset, competitor fact sheets, downloadable forecast model and interactive scenario tools, visit the PW Consulting report page or contact our industry team to schedule a tailored briefing. Our analysts stand ready to run client‑specific scenarios that translate the market’s projected growth into concrete financial and operational plans for 2026.
For detailed analysis of this topic, please visit the official page: Worldwide Disposable Surgical Electrodes Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com