

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Worldwide Omni‑channel and Warehouse Management Systems Market Set to Expand at a Robust 13.98% CAGR, Reshaping Global Supply Chains

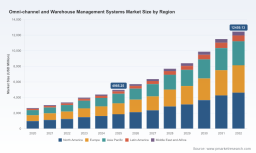
2026 Strategic Brief: Worldwide Omni-channel and Warehouse Management Systems Market — Critical Imperatives for Enterprise Decision-Makers
PW Consulting’s latest market study, Worldwide Omni-channel and Warehouse Management Systems Market, establishes a clear strategic context for enterprise investment decisions in 2026. The sector has transitioned from a specialized operations toolset into a core platform class that underpins customer experience, regulatory compliance, and cost-to-serve economics. Our analysis shows the global market expanding from USD 2.6 billion in 2020 to USD 4.99 billion in 2025, with a projected compound annual growth rate (CAGR) of 13.98% across the 2026–2032 forecast window. By 2032 the market is expected to exceed USD 12 billion, a scale that changes how leadership teams must think about sourcing, architecting, and governing warehouse and omni-channel execution platforms.
Weather Broadcast Services Market
Why this report matters for 2026 decision cycles
-
Capital allocation: As WMS and omni-channel platforms become strategic assets, finance and operations leaders need repeatable frameworks to estimate total cost of ownership (TCO) across cloud and on‑premise models, including migration, integration, and continuous improvement budgets.
Medical Position Gel Pad Market -
Vendor selection and negotiation: With rising consolidation among leading suppliers and a mid‑market of niche specialists, procurement teams require a defensible, use‑case driven sourcing process to avoid functional overlap, integration drift, and vendor lock‑in.
Worldwide Cam Followers Market -
Operational transformation: Warehouse software implementations now deliver measurable throughput and availability improvements that materially offset labor pressures; executives must translate those benefits into headcount planning and fulfillment network strategy.
-
Regulatory and security posture: Stringent traceability and data‑privacy requirements—particularly in pharmaceuticals and food supply chains—necessitate software capabilities that embed auditability, access control, and automated compliance updates.
What the report delivers — practical, transaction-ready intelligence
PW Consulting designed this research as an operational playbook rather than an abstract market brief. Key deliverables included with the full report:
-
Actionable decision matrices that map business use cases (e.g., omnichannel B2C/B2B convergence, high-mix distribution, 3PL monetization) to recommended functional priorities, integration architecture, and deployment models.
-
Vendor evaluation scorecards covering architecture (cloud‑native vs. hybrid), extensibility (APIs, microservices), automation integrations (WCS/WES compatibility), and commercial terms—built for negotiation teams and CIOs.
-
ROI and TCO models with scenario levers for labor cost inflation, throughput improvement, and cloud hosting spend—enabling rapid board-level sensitivity analysis.
-
Implementation roadmaps and risk registers that translate strategic objectives into sequenced workstreams: pilot design, data harmonization, change management, and scale‑up metrics.
-
Compliance and security playbooks addressing traceability, batch/serial control, audit trails, and cloud governance for regulated industries.
Market dynamics reshaping sourcing and architecture choices
Several structural forces inform the strategic recommendations in this edition:
-
Cloud momentum: Cloud‑native offerings have achieved material parity with on‑premise solutions on functionality while delivering elastic capacity, faster update cycles, and lower initial capital outlays—factors driving significant cloud adoption in 2026. That shift changes contracting norms (e.g., subscription economics, shared tenancy) and requires updated finance governance.
-
Labor and productivity pressures: Leading implementations deliver 15–25% throughput improvements and can reduce downtime by as much as 30%, which materially offsets labor shortages and wage inflation. Capturing these gains demands careful process redesign and automation orchestration, not just software deployment.
-
Regulation and traceability: Tighter global rules around drug and food traceability mean that WMS functionality for batch and serial tracking, chain-of-custody, and automated documentation is now a procurement imperative for regulated sectors.
-
Security and data governance: As WMS platforms move to SaaS models, information security, privacy controls, and audit capabilities are table stakes. Organizations must align cloud contracts with their risk appetite and incident response playbooks.
Competitive landscape — who moves markets and why it matters
The market presents a blended competitive structure: a handful of global leaders that command a significant share of enterprise deployments, and a large cohort of specialist and regional vendors that compete on vertical depth, integration agility, and total solution economics. Our concentration metrics indicate a market where the top three providers collectively hold a meaningful but not dominant position, and the top five approach half of the commercial footprint—circumstances that favor both platform consolidation and targeted best‑of‑breed strategies.
Key vendor archetypes and strategic differentiators highlighted in the report include:
-
Platform leaders with broad ERP/SCM ecosystems that emphasize end‑to‑end integration and enterprise governance.
-
Cloud‑native WMS vendors that prioritize rapid SaaS deployment, multi‑tenant scalability, and modern integration fabrics for omnichannel orchestration.
-
Mid‑market specialists and modular players that deliver fast time‑to‑value for specific verticals (e.g., healthcare distribution, 3PLs, food & beverage) and for automation‑heavy DCs.
Notable company developments in the past 18 months include strategic acquisitions that close the TMS–WMS loop, rebrands and portfolio consolidations that bundle WMS with WCS/WES capabilities, and regional expansion partnerships that accelerate deployments in North America and Europe. These moves translate into concrete implications for integration risk, competitive pricing, and the availability of bundled execution suites.
A pragmatic decision framework for 2026
Enterprises evaluating investments this year should adopt a structured, outcome‑oriented approach. We recommend a four‑step framework:
-
Define the business case around discrete fulfillment outcomes (e.g., speed‑to‑customer, fill rate, cost‑per‑order) rather than feature lists. Map these outcomes to measurable KPIs and acceptable payback horizons.
-
Assess architecture fit: identify whether a cloud‑first, hybrid, or on‑premise topology best meets your latency, compliance, and integration needs. Include scenario analysis for cloud hosting cost and data residency.
-
Design a phased deployment plan: pilot in a high‑impact facility, instrument KPIs, then scale using templated integrations to ERP/TMS/OMS and automation controls. Embed continuous improvement cadences tied to operational metrics.
-
Mitigate vendor and program risk: insist on open APIs, clear SLAs, and exit/transition plans. Negotiate performance‑linked commercial terms where possible and validate third‑party automation integrations in scope.
Common risks and recommended mitigations
-
Vendor lock‑in: Prefer modular architectures and contractual rights to data export. Require reference architectures and interoperability certifications for key automation partners.
-
Integration complexity: Allocate budget and governance for data harmonization and master data management upfront. Treat integration as a multi‑quarter program, not a checkbox activity.
-
Underrealized benefits: Avoid “lift and shift” implementations. Ensure process redesign and operator training are part of the core program budget to capture throughput gains.
-
Regulatory drift: Choose vendors that provide automatic compliance updates for regulated workflows and include compliance test plans in acceptance criteria.
Quick wins and a 36‑month roadmap
-
0–6 months: Run rapid use‑case workshops to select pilot sites, secure executive sponsorship, and finalize data contracts.
-
6–18 months: Execute pilots that emphasize measurable KPIs (throughput, downtime, error rates), integrate with ERP/TMS, and validate automation interfaces.
-
18–36 months: Scale templated deployments, monetize 3PL or shared‑services models where relevant, and reset operating models to capture ongoing efficiency gains.
How to use PW Consulting’s full report
The published study is designed to be the working companion to your sourcing and transformation program. It contains the granular segmentation, vendor scorecards, pricing benchmarks, country‑level growth curves, and case studies that procurement, operations, and IT leaders need to finalize strategy and negotiate contracts. In keeping with our preview approach, this briefing highlights the strategic implications and decision frameworks; detailed segmentation tables, provider financials, and vertical breakouts are reserved for the full report.
For executives preparing budgets and procurement cycles in 2026, the strategic choice is no longer whether to modernize warehouse execution—but how to design an architecture and partner ecosystem that locks in flexibility, compliance, and continuous improvement. PW Consulting’s market forecast and implementation playbooks provide the evidence base and step‑by‑step guidance to align spend with outcome, de‑risk transformation, and optimize the cost‑to‑serve across your fulfillment network.
To access the full dataset, vendor evaluations, and operational toolkits, please visit our report page for the Worldwide Omni-channel and Warehouse Management Systems Market.
For detailed analysis of this topic, please visit the official page: Worldwide Omni-channel and Warehouse Management Systems Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com