

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting Forecasts Worldwide Pharma‑Grade Ibrutinib Market to Grow at a 3.88% CAGR from 2026–2032

Worldwide Pharma‑Grade Ibrutinib Market: Strategic Briefing for 2026 Decision‑Makers
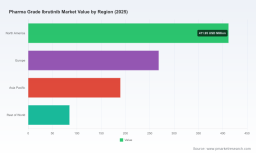
PW Consulting’s newest market intelligence brief on the Worldwide Pharma‑Grade Ibrutinib Market synthesizes five years of historical market behavior and a seven‑year forecast into an operational playbook for commercial, regulatory, and investment leaders. Our model shows the global pharma‑grade ibrutinib market expanding from the mid‑hundreds of millions in 2020 to just under USD 955 million in 2025, and continuing to grow at a compounded annual growth rate (CAGR) of approximately 3.88% through our 2032 horizon. By 2032 the market is expected to approach the low‑to‑mid‑billions (USD 1.25 billion range). This briefing explains why those topline dynamics matter for 2026 strategic choices and where the hidden triggers for share shifts live.
Worldwide Artificial Disc Replacement Systems Market
Why this report matters for 2026 planning
-
Timing of tactical moves. 2026 is a hinge year: reimbursement policy resets, staggered patent expiries in major jurisdictions, and fresh clinical datasets will collectively reframe commercial viability. Executives who align resource allocation with these calendarized inflection points can preserve margin and accelerate uptake of differentiated offerings.
Worldwide Patient Experience Software Market -
Asymmetric downside from pricing shocks. Our scenario work shows that negotiated public payer prices and negotiated Part D ceilings materially compress price tolerance in core markets. Procurement teams, contract negotiators and pricing leads need pre‑mapped contingency plans to avoid margin erosion.
Worldwide Seabuckthorn Pulp Oil Market -
Supply chain and API sourcing risk. With API trade prices exhibiting wide transactional spreads by quantity and destination, procurement and quality assurance must adopt multi‑tier sourcing and validated second‑source strategies to avoid bottlenecks if demand shifts or regulatory inspections displace a supplier.
Market dynamics that will drive boardroom decisions
-
Policy and reimbursement shocks: The market will trade under new reimbursement regimes beginning in 2026 that reduce the maximum Medicare Part D price for a defined 30‑day supply significantly compared with earlier list prices. Payers’ new negotiating power compresses net prices and will prioritize products with clear cost‑effectiveness narratives and robust real‑world evidence.
-
Patent and exclusivity timelines: The product’s composition‑of‑matter patent landscape and stacked secondary patents create a staggered cliff structure across jurisdictions. While composition patents conclude in core markets within the next few years, regulatory exclusivities and later patents extend practical protection in several territories — producing multi‑stage generic entry scenarios that require different responses depending on market exposure.
-
China and local generics: In large, import‑sensitive markets the compound patent lifecycle differs and local generics have already established footholds. These domestic dynamics are a template for how price and access pressure can arrive earlier than global headline expiries.
-
Supply economics: Transaction data for ibrutinib API shows a material price dispersion depending on order size and destination market. This dispersion creates opportunity for arbitrage but also for sudden margin compression if large buyers consolidate volumes with low‑cost suppliers. Manufacturing scale, GMP compliance and backward integration are strategic levers.
Competitive landscape — who matters and why
The market structure is concentrated: the top three firms control a majority share while the top five capture a supermajority—an environment that benefits incumbents with integrated commercial capabilities. Key industry participants to track include branded originators and a broad set of established generic/API manufacturers from India, China and Europe. Representative companies covered in the report include Janssen Pharmaceuticals (Johnson & Johnson) and Pharmacyclics LLC (AbbVie) — the originator co‑developers and primary commercial players — alongside multiple active API and generic formulators from India and Asia, as well as select European producers.
-
Originator strategy: The originator players retain differentiated formulations and global regulatory footprints. Recent label updates and new clinical data presentations have reinforced the therapeutic positioning in core indications. These moves are designed to defend premium positioning and to blunt substitution once generics arrive.
-
Generic and API players: A sizeable and diverse pool of generic developers and API suppliers is operational in parallel — many with GMP capabilities and multiple manufacturing sites. Recent tentative approvals for generic tablets in certain jurisdictions have already altered the competitive calculus for some markets by accelerating potential price competition.
-
Consolidation and partnership vectors: Given the current market concentration, expect strategic alliances, licensing deals and selective M&A to accelerate among mid‑sized players aiming to secure scale, regulatory dossiers, or commercial distribution that shortens time‑to‑market.
What’s in the full report (practical deliverables)
We designed the report to be a working document for 2026 decision cycles. Highlights include:
-
Market modelling: top‑down and bottoms‑up models across historical (2020–2025) and forecast (2026–2032) windows, with transparent assumptions and alternative scenarios reflecting differential patent expiry, payer shocks, and clinical adoption curves.
-
Pricing & procurement playbook: transaction‑level API price benchmarks, tiered supplier matrices, and procurement decision trees to optimize landed cost while maintaining regulatory compliance.
-
Regulatory timelines and exclusivity mapping: jurisdictional patent and exclusivity timelines, plus accelerants and blockers for generics entry under different litigation and licensing outcomes.
-
Competitive dossiers: concise, actionable profiles for originators, leading generic manufacturers and notable API producers — including capability assessments and commercial readiness indicators.
-
Scenario stress tests: four commercial scenarios (Base, Accelerated Generic Entry, Payer‑Downside, and Clinical Differentiation Win) with quantified top/bottom‑line impacts and tactical playbooks for each.
-
M&A and partnership playbook: valuation thesis, integration risk checklist, and prioritized target archetypes for acquirers seeking to accelerate scale or secure supply.
-
Operational checklists: CMC due diligence templates, regulatory submission timelines, and GMP inspection preparation guides tailored to ibrutinib chemistry and formulation challenges.
Strategic implications by stakeholder
-
For originator brands: Prioritize evidence generation and lifecycle management that demonstrably slows payer substitution. Explore authorized generic strategies and selective licensing to preserve revenue while avoiding value‑destroying price wars.
-
For generic/API manufacturers: Focus on validated second‑source positioning, regulatory readiness in jurisdictions with early patent expiration, and scale economics to compete on margin rather than price alone. Consider stepwise capacity expansion with contractual off‑take clauses tied to price thresholds.
-
For payers and hospital systems: Use the timeline clarity in the report to forecast budget impacts and to develop formularies that balance short‑term cost containment with long‑term outcomes — particularly in populations where fixed‑duration regimens may change total cost of care.
-
For investors and M&A teams: Identify targets with defensible manufacturing footprints, strong dossier completeness, and commercial distribution that can be rapidly integrated. Our scenario analysis identifies valuation asymmetries created by different generic entry timings.
How PW Consulting’s intelligence de‑risks 2026 moves
-
Proactive calendarization: We map decision triggers (regulatory, reimbursement, clinical) to calendar quarters so commercial launches, procurement contracts and regulatory filings can be sequenced optimally.
-
Quantified scenarios: Instead of qualitative warnings, we provide modeled P&L impacts under competing assumptions, enabling finance teams to stress test allocations and covenant exposure.
-
Actionable procurement levers: Our vendor scoring and contractual templates allow legal and supply teams to lock in favorable terms that constrain downside in the event of sudden price pressure.
-
Competitive playbooks: Customized tactics for defending market share and for attacking niches where clinical differentiation or formulation innovations create sustainable advantages.
Concluding guidance and next steps
The ibrutinib landscape entering 2026 presents a classic mix of opportunity and disruption: steady underlying demand, concentrated incumbent control, and a calendar of policy and patent events that will create asymmetric winners and losers. Senior leaders who combine a clear read of payer policy, an anticipatory supply strategy, and scenario‑based investment discipline will preserve value and create strategic optionality.
PW Consulting’s full Worldwide Pharma‑Grade Ibrutinib Market report contains the underlying datasets, the full set of scenarios with model files, supplier scorecards, regulatory timelines, and an executive decision dashboard designed for immediate use in board and investor committees. For access to the complete intelligence suite and to schedule a tailored briefing for your executive team, please visit the PW Consulting report page or contact our industry team directly.
For detailed analysis of this topic, please visit the official page: Worldwide Pharma Grade Ibrutinib Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com