

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Worldwide 2D Ablation Catheter Market Valued at USD 552.48 Million in 2025, Poised to Grow at a 4.58% CAGR Through 2032

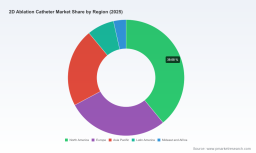
Worldwide 2D Ablation Catheter Market — Strategic Briefing for 2026 Decision-Makers
PW Consulting presents a concise, decision-focused briefing drawn from our forthcoming Worldwide 2D Ablation Catheter Market research. This note is designed as a “trailer” for executives and investors preparing strategy and capital-allocation decisions in 2026: it exposes the analytical depth and actionable lines of inquiry contained in the full report while preserving the proprietary granularity that drives transactional value. Below we summarize the market context, strategic implications, competitive dynamics and the specific ways senior leaders should apply the research to near-term choices.
Worldwide Thermal Conductive Sheet Market
Macro snapshot: size, growth and structure
Our market model — grounded in five years of historical data (2020–2025) and a seven-year forecast window (2026–2032) — estimates the global 2D ablation catheter market at approximately USD 552.5 million in the 2025 base year, expanding at a compound annual growth rate (CAGR) of 4.58% across the forecast period. Under the PW Consulting central scenario, the market continues to grow steadily into the early 2030s as electrophysiology workflows evolve, imaging capability becomes more integrated, and multi-energy ablation options scale clinically.
Photovoltaic Power Installation System Market
Concentration metrics highlight a market dominated by a small group of established medtech leaders: the top three vendors capture a clear majority share, while the top five control a materially larger portion of supplier revenue—an important structural fact for partners and challengers planning entry or defense strategies.
Worldwide Car Code Reader Market
What the full report delivers (practical, executable content)
-
Transparent market model with annualized revenue series (historical and forecast), sensitivity scenarios and an investor-grade methodology appendix — enabling replication of our base case and stress tests for alternative outcomes.
-
Regulatory and reimbursement playbook that maps pathway timelines, pivotal endpoints and coding/pricing implications across the major jurisdictions relevant to 2D ablation and intracardiac echocardiography (ICE).
-
Competitive benchmarking that synthesizes product-level features (energy modality, contact sensing, irrigation, steerability, imaging integration), go-to-market routes and clinical evidence strength for the highest-impact suppliers.
-
Commercialization playbooks for five archetypal entrants: global platform incumbent, regional challenger, focused device innovator, contract manufacturer and digital-imaging adjutant — each with step-by-step launch priorities and KPIs.
-
M&A and partnership heat maps that identify targets, capability gaps and valuation sensitivities across technology categories (e.g., RF, PFA, cryo, ICE, mapping).
-
Clinical adoption and HTA dossier templates to accelerate reimbursement negotiations and hospital formulary inclusion for both single-procedure devices and integrated system offerings.
-
Risk register and mitigation matrix covering regulatory, reimbursement, supply chain, clinical trial, and competitive-intensity risks with suggested monitoring triggers through 2028.
Key strategic imperatives for 2026
-
Prioritize interoperability: Device manufacturers must design catheters and ICE imaging tools to integrate seamlessly with mapping platforms. The commercial winners will be those who reduce procedural friction for electrophysiology labs and facilitate multi-vendor compatibility.
-
Invest in multi-energy R&D selectively: Pulsed field ablation (PFA) is shifting clinical paradigms, but RF and cryo remain essential. A layered portfolio approach — where new energy modalities are introduced without abandoning proven platforms — preserves customer relationships while enabling clinical differentiation.
-
Differentiate on clinical information, not just hardware: Real-time imaging and contact-sensing data increasingly drive value. Firms that bundle analytics, workflow automation and imaging-guided lesion-control capabilities will capture premium share and margin.
-
Plan regulatory sequences strategically: In the US, 510(k) remains the dominant pathway for many catheter products — but device claims, mapping compatibility, and ICE imaging enhancements require carefully scoped submissions. Early engagement with regulators reduces timeline risk.
-
Align coding and reimbursement strategies with clinical evidence planning: Because procedural CPT codes often do not distinguish energy type, commercial success depends on documenting procedure efficiency, safety benefits, and hospital system economics to secure favorable adoption.
-
Use market concentration to your advantage: The high share held by leading incumbents means targeted alliance plays or bolt-on acquisitions can unlock rapid access to installed bases and clinical networks; conversely, prepare for aggressive share-defense by incumbents.
-
Prepare for regional nuance without over-committing: Emerging players and localized regulatory approvals can create pockets of accelerated adoption. A flexible market-entry playbook — emphasizing distributor partnerships and conditional manufacturing capacity — reduces upfront capital risk.
-
Operationalize clinical evidence as commercial fabric: Real-world evidence (RWE) and registries are becoming core sales tools. Commit to post-market data generation to accelerate inclusion in hospital pathways and payer conversations.
Competitive landscape: positioning and near-term catalysts
The sector combines a set of global platform incumbents with technologically focused challengers and regional specialists. Strategic implications flow from product-platform strategies and the recent regulatory events that influence credibility and market access.
-
Biosense Webster (Johnson & Johnson MedTech) — A portfolio leader in RF catheters integrated with high-end mapping systems; the firm’s continued emphasis on imaging integration (recent US launch of an advanced 2D ICE catheter) underscores a platform strategy centered on real-time guidance and workflow harmonization.
-
Boston Scientific — Maintains broad RF capability and is actively participating in pulsed field ablation development. Expect continued product refinement on irrigation and contact-sensing to defend electrophysiology lab footprints.
-
Abbott — Sensor-enabled catheters and new regulatory clearances are reinforcing Abbott’s position in both RF and pulsed-field pathways; tactical CE approvals indicate a go-to-market cadence focused on Europe while protecting intellectual property for broader commercialization.
-
Medtronic — Combining mapping and energy technologies across RF, cryo and emerging PFA; incumbency in cryo for pulmonary vein isolation remains strategic for bundled-system sales.
-
Shanghai MicroPort EP — Rapid local approvals and a multi-energy product set demonstrate how regional champions can scale quickly; partnerships and robotic navigation collaborations are tactical moves to offset global incumbents’ advantages.
-
Specialists and enablers (Biotronik, Japan Lifeline, Osypka, APT Medical, CardioFocus, Stereotaxis) — These firms provide focused technologies (gold-tip designs, disposable diagnostic catheters, balloon PFA, robotic navigation) that are attractive targets for vertical integrators or for strategic alliances with global OEMs.
Recent regulatory and product milestones in late 2025 and early 2026 validate these trends: select ICE catheter launches and device clearances have materially improved image-guided workflows, while robotic and PFA approvals expand the addressable clinical use cases. These events simultaneously lower adoption friction and raise the bar for market entry.
Regulatory and reimbursement dynamics that change the playbook
-
Regulatory predictability: The FDA 510(k) pathway remains the common route for many 2D ablation and ICE devices in the US, but manufacturers must now demonstrate mapping-system compatibility and cross-device safety in submission packages. Early regulatory alignment workshops are essential.
-
Coding realities: Current CPT and MS-DRG structures frequently do not differentiate procedures by energy source. This compresses short-term pricing leverage for novel energy modalities unless vendors can demonstrate measurable gains in procedural efficiency, safety, or total cost of care.
-
Payer engagement: To influence hospital purchasing and procedure mix, device sponsors must prepare HTA-style dossiers that quantify incremental clinical and economic benefits and that anticipate adjustments to practice expense inputs used in physician reimbursement.
How executives should use the PW Consulting report in 2026
-
Portfolio prioritization: Use our scenario outputs to set R&D and commercial-investment gates — timing PFA, ICE and mapping enhancements to regulatory and reimbursement inflection points.
-
M&A and JV diligence: Apply our valuation sensitivities and capability matrices to shortlist assets that plug specific gaps (robotics navigation, multi-energy catheters, imaging analytics) and to construct integration plans that preserve momentum in core markets.
-
Market-entry sequencing: Follow our staged entry playbooks to limit capital exposure while establishing clinical champions and distribution footholds in high-opportunity regions.
-
Commercial model design: Leverage our go-to-market templates to determine the optimal mix of direct sales, distributors and clinical partnerships, and to define field-team KPIs tied to hospital economics rather than device units alone.
-
Risk monitoring: Adopt the report’s trigger-based risk register to monitor near-term regulatory decisions, reimbursement updates and competitor approvals that could materially affect your plan.
Conclusion — what to act on now
For C-suite leaders, 2026 is a year to convert technological momentum into durable commercial advantage. The market is growing at a steady mid-single-digit rate, incumbents retain meaningful advantages, and a cluster of regulatory and clinical events will reshape adoption curves. The practical intelligence in our full report equips product, regulatory, commercial and corporate development teams to prioritize investments, structure alliances wisely, and negotiate access with evidence-based economics.
PW Consulting’s full Worldwide 2D Ablation Catheter Market report contains the models, playbooks and vendor-level benchmarking your team will need to move from strategic intent to executable plans. Use this briefing as a roadmap: the full dataset and tactical appendices will enable rigorous scenario testing and transaction-ready diligence.
For detailed analysis of this topic, please visit the official page: Worldwide 2D Ablation Catheter Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com