

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Worldwide 3D Scanning Wind Lidar Market to Expand at 7.85% CAGR Through 2032

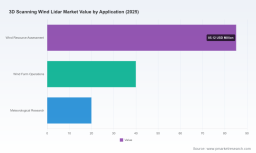
Worldwide 3D Scanning Wind LiDAR Market — Strategic Briefing for 2026 Decision Makers
PW Consulting’s latest market study on the Worldwide 3D Scanning Wind LiDAR market provides an evidence-based roadmap for corporate leaders, project developers, and technology investors preparing strategic moves in 2026. The market is transitioning from niche measurement systems to mission-critical infrastructure for onshore and offshore wind projects. Our study synthesizes historical performance (2020–2025), a focused base-year assessment (2025), and a forward-looking forecast (2026–2032) to quantify opportunity, technology risk, and supplier power as the sector scales.
Worldwide IT Risk Management Software Market
Market snapshot: growth trajectory and what it implies
At the headline level, the 3D scanning wind LiDAR market is established and expanding. PW Consulting’s base-year analysis places the industry at approximately USD 145 million in 2025, with a projected compound annual growth rate (CAGR) of 7.85% across the 2026–2032 forecast window. By 2032 the market is expected to approach the mid‑hundreds of millions of USD, driven by intensified resource assessment activity, operations optimisation, and a material shift toward multi-point measurement architectures for offshore wind developments.
Worldwide Solder Recycling Market
For strategic planners, this growth profile has three immediate implications: (1) addressable demand is large enough to justify product development and strategic partnerships but small enough that first-mover advantages and technological differentiation matter; (2) procurement cycles will increasingly favour bundled measurement and analytics offerings rather than point solutions; (3) capital allocation toward integration with digital twins, IEC-compliant testing, and multi-lidar deployments will generate disproportionate technical and commercial upside.
Worldwide Curry Powder Market
Why 2026 is a pivotal year for corporate strategy
- Procurement windows converge: Several major wind farm pipelines reach FEED and procurement stages in 2026–2027. Organisations that align product readiness and validation evidence (IEC testing, classification) to these windows will gain preferential commercial access.
- Technology validation is maturing: Independent IEC-compliant testing and vendor certification are becoming table stakes. Buyers will increasingly prioritise systems with verifiable measurement uncertainty and classification limits.
- Supply dynamics are tightening: Critical optical and fiber-laser components, typically eye-safe 1550 nm lasers and high-sensitivity photodetectors, have become a strategic supply-line consideration. Early supplier relationships materially reduce lead-time and quality risk.
Key strategic themes uncovered by the report
- From point measurement to 3D situational awareness: The market evolution is driven by a migration from single-line profiling lidars to scanning systems that produce volumetric wind fields. This shift enables improved wake steering, turbine control, and fatigue forecasting—capabilities that make LiDAR a core component of operational O&M stacks.
- Dual and distributed LiDAR configurations: Dual lidar setups and distributed scanning arrays are emerging as best practices for complex offshore layouts and high-turbulence sites. These configurations increase measurement confidence but raise integration and data-processing requirements.
- System validation & regulatory gating: Adoption is influenced strongly by third-party IEC testing and classification. Vendors that invest in transparent, repeatable validation programs reduce procurement friction and shorten sales cycles.
- Supply‑chain specialization: Core laser and detector supply remains concentrated among a few component vendors. Firms that secure supply agreements (or verticalise certain optical elements) will enjoy margin and delivery advantage.
Technology and supply chain: what buyers should watch
- Laser and detector sourcing: 1550 nm eye-safe fiber lasers plus matched photodetectors and optics are the technical backbone. Long lead times or single-source exposure for these components can cascade into project delays—an important procurement risk for OEMs and integrators.
- Software and analytics integration: Raw scans only become operational value when paired with validated analytics, uncertainty quantification, and integration with turbine control systems. Expect procurement decisions to favour vendors offering bundled analytics, APIs, and cloud-ready data formats.
- IEC/testing readiness: IEC-compliant products shorten sales cycles with developers and financiers. Companies that can present independent validation reports and classification certificates will win tier-one projects.
Competitive landscape — what the market structure means for entrants and incumbents
The competitive frame is composed of established meteorological sensor specialists, optics-focused OEMs, and a growing cohort of regional integrators. Market concentration remains moderate: a handful of vendors hold leading positions but nearly half of demand remains addressable to challengers and specialist newcomers.
- Vaisala (Vantaa, Finland): A clear leader with products such as the WindCube Scan family. Vaisala’s strength lies in validated dual-scanning deployments and a broad service footprint—qualities that make it a preferred partner for large-scale offshore resource assessments.
- ZX Lidars (United Kingdom): ZX has focused on ground-based scanning solutions validated to IEC performance classes. Recent product introductions demonstrate a focus on certified performance at economically relevant heights, which improves their position for project developers prioritising compliance.
- Movelaser (Nanjing Movelaser): A rapidly scaling Chinese vendor offering programmable 3D scanning systems. Movelaser’s value proposition centres on configurable scan modes and cost-competitive systems that appeal to price-sensitive markets and regional integrators.
- Halo Photonics (Lumibird): Produces coherent pulsed Doppler systems suited to profiling and scanning; the product portfolio is well matched to wind energy and meteorological research segments requiring high fidelity measurements.
- ZATA and Leonardo: ZATA’s pulse-Doppler offerings and Leonardo’s SKIRON3D target high-end profiling and hazard detection use cases (aviation and turbine hazard assessment), illustrating cross-sector technology transfer and diversification strategies.
- Windar Photonics: Focused on nacelle-mounted and scanning solutions, Windar illustrates the strategic play of bundling with turbine OEMs and nacelle-system integrators.
Recent vendor activity underlines accelerating product maturation: ZX Lidars launched a new ground-based unit with IEC performance evidence in late 2025, and Vaisala rolled out a performance-improved unit aimed at energy and meteorological buyers. These moves validate the market’s technology-driven dynamics—performance claims backed by independent testing increasingly determine procurement outcomes.
What the PW Consulting report delivers — practical, actionable intelligence
PW Consulting’s Worldwide 3D Scanning Wind LiDAR report is designed for executives who need to convert market intelligence into boardroom decisions. Key deliverables include:
- Validated market sizing and scenario-based forecasts (2026–2032) that translate into ARR and TAM considerations for product and M&A planning.
- Vendor scorecards and commercial playbooks: technology maturity, IEC testing status, partner ecosystems, and pricing posture—constructed to support supplier selection and RFP design.
- Procurement-risk frameworks that quantify lead-time exposure from optical component supply and propose mitigation tactics, including dual sourcing and inventory strategies.
- Deployment playbooks for onshore and offshore architectures covering dual-lidar configurations, buoy and nacelle integration considerations, and data-integration templates for control systems.
- Investment due diligence checklists tailored to corporates and private equity: technical validation steps, software IP assessment, and go-to-market scenarios for scaling across regions without exposing sensitive site-level data in this briefing.
How to use the intelligence when shaping 2026 budgets and roadmaps
- CapEx vs. OpEx decisions: For portfolios that prioritize development speed, allocate budget to validated rented LiDAR services for early-stage resource assessment, reserving CapEx for proven, IEC-classified deployments aligned to late-stage procurement windows.
- R&D and partnerships: Invest in analytics and integration rather than purely hardware differentiation. Partnerships with optical component suppliers or co-funded IEC-testing programs de-risk product roadmaps and accelerate market acceptance.
- M&A and ecosystem plays: Mid-sized LiDAR vendors with proprietary scanning modes and field validation records are attractive bolt-on candidates for turbine OEMs, asset managers, and met-service providers seeking vertical integration.
- Operational deployment: Prioritise multi-point measurement strategies for offshore and complex terrain sites; these deliver measurable ops and finance benefits but require advanced data fusion capabilities.
Trailer insight — what we deliberately withhold (and why you should request the full study)
In this briefing we present the macro economics, vendor dynamics, and strategic implications necessary to inform near-term decisions. Per the “trailer” principle, detailed segment tables (regional and application-level shares, deployment-specific pricing curves, and contract-level datasets) are withheld to protect model integrity and ensure clients receive the full, interactive dataset. These details are critical for project-level cashflow modelling, bid preparation, and procurement negotiation strategy—areas where precise segment and pricing information materially alters decision outcomes.
Next steps — how to engage PW Consulting’s analysis
For procurement teams, engineering leads, and corporate strategists preparing 2026 plans, PW Consulting offers tailored briefings and data-room access. Our advisors can map the report’s scenarios to your project timelines, run vendor shortlists against IEC readiness, and model procurement outcomes under supply-chain stress tests.
Request an executive briefing or licensing of the full dataset via PW Consulting’s market reports channel. The full report contains the complete segmentation matrices, vendor financial benchmarking, and downloadable forecast models required to move from strategy to contract.
PW Consulting — translating rigorous market science into pragmatic 2026 strategies for organizations operating at the intersection of renewable energy and real‑time measurement systems.
For detailed analysis of this topic, please visit the official page: Worldwide 3D Scanning Wind Lidar Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com