

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Worldwide Chemical Industry Distributed Control System Market Poised to Hit USD 9.47 Billion by 2032, Growing at a 5.5% CAGR

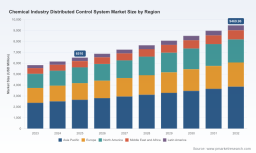
Worldwide Chemical Industry Distributed Control System Market: Strategic Insights for 2026 Decision-Makers
PW Consulting’s latest market study—Worldwide Chemical Industry Distributed Control System (DCS) Market—delivers an actionable intelligence package designed to inform executive decisions in 2026. Anchored on a 2025 base year and projecting through 2032, the study quantifies a clear growth trajectory for chemical-industry DCS deployments, with the global market expanding from USD 6,510.0 Million in 2025 to roughly USD 9,470.0 Million by 2032, at a compounded annual growth rate (CAGR) of 5.5%. This press release outlines the strategic value of the research for manufacturers, C-suite leaders, and technology investors while preserving the report’s detailed segment-level findings to incentivize full access to the source analysis.
E-Methanol Fuel for Marine Market
Why this report matters for 2026 planning
-
Timing and scale: With the market in steady expansion, capital allocation and program sequencing for automation modernization are becoming critical. Our forecast period beginning 2026 captures the window when software-defined architectures, edge-cloud integration, and autonomous operations accelerate procurement and retrofit cycles.
Worldwide Encapsulation & Embedment Compound Mixing & Dispensing Equipment Market -
Risk and compliance alignment: Regulatory dynamics—most notably phased regulatory actions affecting refrigerants and related process equipment—are reshaping operations and capex priorities. The report translates these policy drivers into near-term and medium-term demand implications for control-system upgrades and process reengineering.
Worldwide Yard Scrapers Market -
Vendor transition dynamics: The competitive environment is actively shifting toward software-centric DCS offerings and open, interoperable architectures. This report maps vendor strategy moves and product roadmaps to help buyers reduce migration risk and optimize total lifecycle cost.
What’s in the report: Practical deliverables for executives
-
Commercial forecast and scenario analysis: Our base-case projection (2026–2032) at 5.5% CAGR is complemented by downside and upside scenarios tied to capital cycles, regulatory timing, and technology adoption rates—allowing CFOs to stress-test budget plans.
-
Decision frameworks: A set of board‑level and operational checklists to evaluate build vs. buy vs. migrate choices for DCS, with scoring templates that weigh cybersecurity, interoperability, serviceability, and long-term vendor viability.
-
Procurement and contracting playbooks: Standardized contract language, SLA benchmarks, and a network of negotiation levers informed by market concentration dynamics—helping procurement teams secure predictable upgrade paths and modular pricing.
-
Migration and integration blueprints: Detailed migration roadmaps for legacy-to-modern DCS transitions, including phased cutover approaches, hardware/software coexistence patterns, and testing & validation sequences to minimize production disruption.
-
Operational KPIs & ROI calculators: Role-specific KPIs for plant operations, maintenance, and IT, coupled with ROI calculators that model efficiency gains, yield improvements, and cybersecurity-related loss avoidance.
-
Risk heatmaps and regulatory timelines: Topical overlays that connect evolving environmental regulations and industrial standards to asset refresh schedules and compliance investments.
Competitive landscape: What the vendors are doing—and what it means to buyers
The DCS supplier base for chemical applications is characterized by a mix of large, incumbent automation suppliers and specialized niche players. Market concentration is meaningful—our study finds that the top three suppliers control a substantial share of the market, while the top five capture a clear majority. That concentration has strategic consequences for pricing leverage, long-term support commitments, and the availability of integrated service bundles.
-
Emerson Electric Co. — Continuing to push DeltaV into a software-defined future, Emerson is emphasizing reduced automation costs, improved operational intelligence, and embedded cybersecurity in its latest release. For buyers, Emerson’s strategy signals competitive pressure on migration economics and long‑term lifecycle support for chemical plants.
-
Honeywell International Inc. — Honeywell’s positioning with its Experion platform centers on real-time optimization, safety integration, and AI-assisted operations. Plants prioritizing compliance and process reliability should evaluate Honeywell’s strengths in integrated safety and control logic.
-
ABB Ltd. — ABB’s recent updates focus on enhanced connectivity and field device integration, underscoring its modernization play. For brownfield sites with heterogeneous field assets, ABB’s integration capabilities can materially reduce retrofit complexity.
-
Siemens AG — Siemens continues to prepare customers for broader digital transformation in process industries by investing in cybersecurity-enabled upgrades and efficiency improvements tailored to large chemical production processes.
-
Yokogawa Electric Corporation — With an emphasis on autonomous operations and long-term reliability, Yokogawa’s platform remains attractive to operators seeking endurance and functional safety across distributed sites.
-
Schneider Electric SE — Recent product introductions highlight an industry shift toward open, software-defined DCS architectures. Schneider’s approach aims to deliver flexible modernization paths for hybrid process environments.
-
Rockwell Automation, Mitsubishi Electric, Azbil, Hitachi — These companies round out the competitive set with differentiated strengths in batch processing, integration into broader automation portfolios, process control specialization, or digital integration capabilities. Buyers should match each vendor’s unique capabilities to their operational priorities rather than selecting a supplier purely on brand preference.
Recent vendor developments you need to track
-
Software-defined DCS product launches and major upgrades in early 2026 signal industry-wide prioritization of modular, software-led architectures. These moves materially change procurement models and shift value from hardware to software and services.
-
Enhanced connectivity standards (e.g., OPC UA, edge analytics) and increased support for field-device integration are reducing integration costs for modernization projects—shortening payback timelines for certain retrofit initiatives.
-
Vendors are packaging cybersecurity and compliance as core components of their DCS offerings. For buyers, this reduces the integration burden but increases the importance of detailed service and patching SLAs.
Market dynamics and external risks
Several cross-cutting dynamics are shaping the DCS market for chemical players in 2026:
-
Regulatory shifts: Environmental regulatory actions targeting certain high-global-warming-potential substances are already influencing process equipment decisions and refrigeration system designs. These regulations cascade into automation and controls decisions because compliance often requires process reconfiguration, additional monitoring, and new safety interlocks.
-
Technology migration: The ascent of software-defined automation, industrial AI, and hybrid edge-cloud architectures is increasing the strategic value of software and services relative to hardware. Buyers should recalibrate TCO models to reflect these structural shifts.
-
Concentration and supplier power: The top suppliers hold a meaningful share of the market, which affects negotiation dynamics for multi-plant rollouts and long-term support contracts. Strategic sourcing approaches that foster competitive tension across phases of a rollout will yield better economic outcomes.
-
Service-driven growth: Professional services, lifecycle support, and managed services are becoming an increasingly important revenue stream for suppliers. Chemical operators should assess in-house capabilities against the cost and control trade-offs of outsourcing critical lifecycle activities.
Five strategic actions for 2026
-
Implement a staged modernization pilot: Validate software-defined control modules and edge analytics on a contained production line before scaling. Use the pilot to refine migration playbooks and validate ROI assumptions.
-
Build a cybersecurity and patching governance timetable: Align control-system upgrade windows with regulatory compliance deadlines and vendor patch cycles to minimize operational risk.
-
Negotiate modular contracts with upgrade options: Insist on clearly defined extension paths, interoperability guarantees, and data-portability clauses to reduce vendor lock-in over the next technology cycle.
-
Quantify service vs. capital trade-offs: Use the report’s ROI calculators to compare in-house maintenance against vendor-managed lifecycle services, factoring in productivity gains and risk mitigation.
-
Screen M&A and partnership opportunities: Position technology investments to enable collaborations with specialized AI and analytics providers that can accelerate yield optimization and predictive maintenance returns.
Conclusion and next steps
For 2026 strategic planning, PW Consulting’s study equips decision-makers with a concise growth outlook, a vendor landscape that explains where control-system innovation is concentrated, and practical tools to convert forecasts into executable programs. The market’s journey toward software-first DCS architectures, combined with regulatory pressures and a concentrated supplier base, creates both risk and opportunity. Leaders who pair disciplined procurement with rigorous pilot-and-scale approaches will extract the most value from the coming wave of modernization.
To review the full suite of segmentation tables, vendor scorecards, regional forecasts, and the complete set of practical deliverables, visit PW Consulting’s report page and access the Worldwide Chemical Industry Distributed Control System Market study for the comprehensive dataset and the proprietary decision-support tools referenced here.
For detailed analysis of this topic, please visit the official page: Worldwide Chemical Industry Distributed Control System Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com