

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Worldwide Grinding Machine (Moving Table) Market to Reach USD 4,309.35 Million by 2032 at a 4.62% CAGR, Led by Asia Pacific’s USD 1,384.02M Share

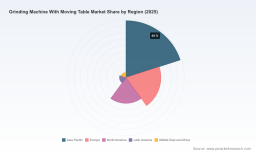
Worldwide Grinding Machine With Moving Table Market: Strategic Preview for 2026 Decision-Makers
PW Consulting’s latest market study on the Worldwide Grinding Machine With Moving Table Market (base year 2025; historical window 2020–2025; forecast period 2026–2032) distills the structural forces, competitive dynamics, and tactical playbook that will shape capital spending and operational choices in 2026. The market is on a steady expansion path, tracking a mid-single-digit compound annual growth rate (CAGR) of 4.62% across our 2026–2032 forecast horizon, with aggregate industry revenue moving from an estimated USD 3,145.5 Million in 2025 to a projected USD 4,309.35 Million by 2032.
Surface Mount Isolator Market
Why this report matters for 2026
- Actionable horizon: Manufacturers and OEM procurement teams preparing 2026 CapEx and modernization plans need a clear, risk-calibrated view of demand, machine lifecycle economics, and automation ROI. Our study provides scenario-tested inputs that translate market projections into unit-level fleet renewal and retrofit guidance.
- Supply-chain sensitivity: Raw material and sourcing volatility has a disproportionate effect on machine OEM margins and lead times. The report quantifies exposure vectors and prioritizes mitigations for procurement and operations teams.
- Competitive positioning: With moderate market concentration (CR3 ~31.4%; CR5 ~46.8%), the landscape is neither a pure oligopoly nor fully fragmented — making 2026 a pivotal year for strategic alliances, selective M&A, and differentiation through digital services. Our firm-level benchmarking supports those choices.
Macro trajectory — what the numbers tell us
Our top-line market sizing shows a consistent, pragmatic growth trend rather than a boom-or-bust cycle. After steady recovery through the early 2020s, the market reached roughly USD 3.15 Billion in 2025 and, under base-case assumptions, grows to about USD 3.28 Billion in 2026 and continues to expand to an estimated USD 4.31 Billion by 2032. This progression reflects ongoing equipment replacement, incremental adoption of CNC and automation-equipped moving-table solutions, and rising demand from capital-intensive end markets requiring high-precision finishing.
Wheeled Medical Cart Market
For strategic planners, the takeaway is clear: demand is durable and predictable enough to support multi-year investment programs, but sensitive to commodity cycles, energy and regulatory drivers, and the pace of digital adoption on factory floors.
The Lightweight Application Server Market
Key dynamics shaping 2026 choices
- Raw material pressure: Iron and steel movements are feeding directly into quoted lead times and list prices for machine frames and tables. Notably, iron reference prices in January 2026 were reported at USD 3,355/MT (China FOB), USD 3,464/MT (India CIF), and USD 3,440/MT (USA CIF). Global scrap prices also climbed across regions from late 2025 to mid-February 2026, raising substitution and sourcing questions for OEMs that depend on recycled steel content.
- Automation and Industry 4.0: The acceleration of IoT, AI-driven optimization, and digital twins is not peripheral — it is core to competitive differentiation. Buyers in 2026 will weigh the premium for connected grinding machines that offer predictive maintenance and unattended operation versus the cost of retrofit for existing fleets.
- Energy and sustainability mandates: Energy-efficiency regulations and decarbonization commitments are driving demand for machines designed with optimized cooling circuits, lower-power drives, and lifecycle emissions accounting. These become non-negotiable procurement criteria for customers in regulated jurisdictions.
- Labour and productivity: Persistent shortages of skilled grinders and maintenance technicians are increasing the value of automated loading, robot integration, and process standardization — factors that influence total cost of ownership (TCO) calculations in our buyer’s models.
Competitive landscape — strategic implications
We profile a broad set of incumbents and specialists in the report, from global groups to regional machine builders. The market exhibits a mix of scale players with hydrostatic and heavy-load platforms and niche suppliers focused on cylindrical, roll, and surface grinding with moving-table configurations. Highlights include:
- Danobat (Elgoibar, Spain): Known for hybrid VG-series vertical machines that consolidate grinding, turning and milling in one setup. Their capability to handle very large-diameter workpieces and sub-micron accuracy positions them well for gear, turbine, and heavy-industry customers seeking single-setup throughput improvements. Recent deliveries such as the March 2026 customer expansion underline continued commercial traction in precision gear manufacturing.
- Herkules (Germany): A leader in roll grinding solutions with automated handling and steady rests — a strategic choice for industrial customers buying high-throughput roll finishing capacity. Their emphasis on traversing grinding saddles and large-format handling is resonant in steel, paper and mining equipment segments.
- Robbi Group, Morara, Gioria and AZ spa (Italy cluster): These firms collectively represent Europe’s depth in cylindrical and railroad-axle-capable machines with moving tables, offering modularity for heavy-duty and mid-sized applications. Their product mix supports both retrofit and greenfield OEM lines.
- JTEKT Machinery and UNITED GRINDING (Mägerle): Positioned for high-volume and high-precision production segments, these players are strategic choices for aerospace, automotive and energy OEMs pursuing throughput and unattended operation.
- HMT Machine Tools, Dowell Machine, Kehren, LGB Scop and Dowell (regional specialists): These manufacturers anchor demand in emerging and price-sensitive markets, and play a critical role in aftermarket parts and local service networks.
From a strategic lens, buyers and investors should evaluate partners and acquisition targets not just on machine specs but on software ecosystems, service networks, and supply-chain resilience. The report cross-references vendor roadmaps against OEM procurement priorities to reveal where partnerships and M&A will be most accretive in 2026.
Report contents that drive 2026 decisions (practical and executable)
- Executive scenarios: Three demand scenarios (conservative, base, upside) with implications for CapEx phasing and inventory management across 2026–2028.
- Fleet economics toolkit: TCO calculators that isolate the impact on operating margins of automation premiums, energy-efficiency retrofits, and predictive maintenance contracts.
- Supply-chain stress tests: Material-price sensitivity analyses (including iron and scrap scenarios), vendor lead-time mapping, and contingency sourcing playbooks.
- Competitive scorecards: Feature-to-price benchmarking across the market’s key OEMs, with emphasis on digital-readiness, aftersales service coverage, and retrofitability.
- M&A and partnership radar: Identification of capability gaps where bolt-on acquisitions or JV structures would accelerate entry into high-growth subsegments.
- Regulatory and sustainability compliance matrix: Practical steps to align procurement specifications with energy and emissions mandates likely to affect large buyers in 2026.
- Implementation roadmap: A quarter-by-quarter guide for procurement, engineering and operations teams to translate strategic choices into deployment timelines and KPI targets.
Practical recommendations for executive teams in 2026
- Prioritize digital-enabled machines for high-utilization cells. For lines where uptime and unattended operation are critical, the incremental CapEx for connected moving-table grinders pays back via higher throughput and lower labor costs.
- Hedge raw material exposure. Negotiate longer-term steel and casting contracts where feasible, and require OEMs to provide bill-of-material transparency to reduce pricing surprises and schedule risk.
- Design retrofit pathways. Not all installations require greenfield replacements — specify modular control systems and mechanical interfaces that allow existing tables and beds to be upgraded with connected spindle and predictive-maintenance packages.
- Use the CR3/CR5 context to inform partner selection. With roughly a third of the market share concentrated in the top three players and under half within the top five, there is room for strategic consolidation but also for specialized vendors to thrive on service differentiation.
- Map service footprints to critical assets. For mission-critical parts (turbine couplings, railway axles, large gear sets), prioritize OEMs offering regional spare part caches and diagnostics SLA that match your production risk tolerance.
Where we hide the details — and why
In keeping with our “trailer” principle, this preview intentionally illustrates methodology, dynamics and strategic implications while withholding fine-grain segment line items and regional/application-specific monetary splits. The full report contains detailed, downloadable datasets (by region, type, and application), modelled P&L impacts at unit level, and vendor-specific price ladders — essential inputs for investment-grade decisions and tender preparation in 2026.
Next steps
PW Consulting invites procurement directors, plant managers, private equity teams and strategic buyers to request the complete report package, which includes the master datasets (USD, revenue in Million), editable TCO models, and a confidential supplier risk matrix. For teams preparing 2026 budgets, the timing is critical: the market’s steady CAGR of 4.62% and the evolving cost structure driven by raw-material movements and digitalization mean that acceleration or delay in procurement can materially change ROI and lead-time exposure.
To access the full report and the data tools that power 2026 decision-making, please visit PW Consulting’s report page or contact your PW Consulting account representative for a tailored briefing.
For detailed analysis of this topic, please visit the official page: Worldwide Grinding Machine With Moving Table Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com