

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Worldwide Ceramic Wafer Boat Market to Rise from USD 542.8 Million in 2025 to USD 937.53 Million by 2032 at 8.12% CAGR — Asia Pacific and SiC Lead Growth

PW Consulting Releases Strategic Brief: Worldwide Ceramic Wafer Boat Market — A 2026 Decision-Maker’s Guide
As semiconductor capacity expansion accelerates into 2026, PW Consulting’s latest market research — the Worldwide Ceramic Wafer Boat Market report (base year 2025, forecast 2026–2032) — delivers the focused market intelligence that procurement leaders, fab architects, equipment OEMs, and investors need to convert uncertainty into competitive advantage. Our analysis synthesizes longitudinal market sizing, competitive positioning, supply-chain risk mapping, and actionable scenario playbooks to inform capital allocation and operational choices in the year ahead.
Worldwide On-Demand Catering Software Market
Executive snapshot: Growth trajectory and market structure
The ceramic wafer boat market is entering a sustained growth phase driven by multi-regional wafer fabs, advanced packaging expansion, and a shift toward high-temperature, contamination-sensitive processes. On a macro basis, PW Consulting’s model projects the global market to climb from the 2025 base to a materially larger footprint through 2032, reflecting a compound annual growth rate (CAGR) of 8.12% over the 2026–2032 forecast window (revenues reported in USD, unit: Million). This trajectory underscores durable demand for high-performance ceramics optimized for diffusion, oxidation and CVD families of processes.
Current Shunt Resistors Market
Market concentration metrics reveal a moderately consolidated vendor landscape: the top three suppliers account for roughly 48.5% of market share while the top five approach 62.3%. This concentration profile has significant implications for supply risk, price elasticity and M&A dynamics — themes we unpack in the body of the report.
Dust Optical Analysis Instruments Market
What the report delivers — practical, decision-grade chapters
- Market sizing & methodology: Transparent, bottom-up revenue modeling with reconciled demand signals from fab buildouts, tool installations and replacement cycles (historical period 2020–2025; forecast 2026–2032).
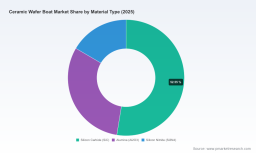
- Segmentation framework: Material-type, process-application and regional demand drivers mapped to technology lifecycles and wafer-fab roadmaps (note: detailed segment-level tables and supplier allocations are reserved for the full report).
- Supply-chain heatmap: Tiered supplier maps, raw-material dependencies, single-source exposures and logistics chokepoints — including vulnerability scoring for critical inputs such as silicon carbide (SiC) feedstock and ultra-pure quartz.
- Competitive benchmarking: Product-performance matrices, manufacturing footprint overlays, and supplier-grade scoring across quality, lead-time, customization capability and contamination control.
- Cost and margin analysis: Unit-cost decomposition, component-level cost drivers, and sensitivity scenarios that quantify the impact of raw-material swings and capacity ramps on price stability.
- Regulatory & trade risk playbook: Assessment of export-control trends and their practical ramifications for sourcing strategies and contract design.
- Procurement playbooks: Category-specific sourcing strategies, qualification checklists for new supplier onboarding, and negotiation levers tailored to different concentration scenarios.
- Strategic scenarios & investment briefs: Three executable paths for OEMs, fabs and private-equity investors — conservative hedging, capability-driven vertical integration, and targeted M&A — each with quantified outcomes under alternate demand trajectories.
Competitive landscape: Who matters and why
Our vendor analysis combines product audits, patent visibility checks, manufacturing-capacity reconnaissance, and recent go-to-market activity. The report profiles established multinational suppliers and emerging regional specialists; below are high-level positioning notes on key players featured in our benchmark.
- Kyocera Corporation (Kyoto, Japan) — Recognized for fine-ceramic wafer boats using high-purity sapphire and advanced ceramics, Kyocera emphasizes plasma and heat resistance with low particle generation. Their long-standing reputation in high-reliability ceramics positions them as a preferred supplier for high-mix, low-defect fabs.
- CoorsTek, Inc. (Golden, Colorado, USA) — A leader in engineered ceramics, CoorsTek is notable for thermal stability and chemical resistance solutions for high-temperature processes. Their global footprint and engineering depth make them a strategic partner for OEMs seeking materials science integration.
- Ferrotec Corporation (Santa Clara, CA; operations in Japan and Taiwan) — Supplies quartz and SiC wafer boats with product suites optimized for thermal stability and chemical wear resistance. Ferrotec’s cross-border manufacturing and strong tooling interface expertise are a differentiator for process-centric collaborations.
- Semicorex (China) — Focused on customized SiC-coated and SiC ceramic boats, Semicorex serves vertical and horizontal configurations frequently used in diffusion and oxidation. Their customization capability targets Western and European demand pockets needing specialized carriers.
- Semicera Semiconductor Technology Co., Ltd. (Ningbo, China) — Produces SiSiC, recrystallized SiC and silicon carbide boats with a focus on high-temperature applications and bespoke carrier designs for complex process stacks.
- 3X Ceramic Parts Company Limited (China) — Offers SiC ceramic boats in varied geometries and high-temperature resilience (product ranges often include high-purity alumina options), positioning them for cost-sensitive and high-volume replacement markets.
- VeTek Semiconductor (China) — Supplies SiC and coated variants with emphasis on durability and throughput optimization — attractive for large-scale fabs seeking robust, long-life carriers.
- Shenyang Starlight Advanced Ceramics Co., Ltd. (Shenyang, China) — With multi-decade experience in SiC, Starlight’s exhibition presence and product roadmap reflect an engineering-led approach to recrystallized SiC solutions.
- Gorgeous Ceramic (GGSCERAMIC) (Xiamen, China) — Delivers both custom and standard SiC/advanced ceramic boats; their market position favors OEMs and sub-suppliers demanding contamination resistance and flexible manufacturing scale.
- Hunan DeZhi New Material Co., Ltd. (Hunan, China) — Manufactures corrosion-resistant SiC boats, including CVD SiC-coated variants, relevant to processes with aggressive chemistries.
PW Consulting’s scoring framework ranks these suppliers not only by product performance but also by qualification speed, geographic redundancy, and regulatory compliance posture — critical evaluation axes for 2026 sourcing decisions.
Recent market movements and contextual drivers
- Product introductions and catalog refreshes among leading ceramic houses in 2025–2026 indicate supplier investments in RSiC (recrystallized SiC) and CVD-SiC coating options to meet advanced-process cleanliness and lifespan requirements.
- Participation at regional advanced-ceramics exhibitions and updated product lines in early 2026 reflects heightened competitive activity — suppliers are rapidly iterating to capture growth from new fab projects and replacement cycles.
- Raw-material dynamics continue to shape supply strategy: SiC remains the primary material for high-performance boats (thermal stability >1600°C and lower contamination risk versus quartz), while ultra-high-purity quartz still maintains relevance in less-demanding thermal processes.
- Policy and trade realities, including refinements to export-control frameworks, add a layer of complexity to cross-border procurement — particularly for advanced ceramic components and associated tooling.
Strategic implications for 2026 decision-makers
PW Consulting’s scenarios translate market projections and supplier intelligence into concrete recommendations for three principal stakeholders:
- Fab procurement teams: Prioritize dual-sourcing of critical ceramic carriers from geographically diversified suppliers and adopt multi-year contracts with indexed pricing clauses tied to raw-material indices to mitigate short-term cost shocks.
- Equipment OEMs: Build tighter co-engineering relationships with high-reliability ceramic suppliers. Incorporate supplier performance clauses tied to particle generation and lifetime endurance, and invest in shared qualification rigs to reduce time-to-qualify for new process nodes.
- Strategic investors and M&A teams: The moderately concentrated market (top-three and top-five share metrics) creates windows for bolt-on acquisitions to achieve vertical integration or to secure technology differentiation in SiC coating and recrystallized SiC processing.
Why readers should consult the full report
This release outlines the strategic contours — growth pace, concentration profile, competitive positioning and high-impact dynamics — that will matter in 2026. The full PW Consulting report contains the granular segmental tables, supplier allocation matrices, unit-cost decompositions, and scenario modeling that support executable decisions: everything from precise supplier scorecards to contract templates and capex timing maps. In keeping with our “trailer” approach, we have intentionally withheld detailed segment-level allocations and sensitive supplier revenue breakdowns to ensure readers consult the source document for complete intelligence and raw data downloads.
Next steps and how to engage
Organizations planning capital commitments, supplier rationalizations, or strategic partnerships in 2026 should treat this research as a decision-enabling toolkit. PW Consulting clients receive bespoke briefings that translate the report’s insights into tailored action plans — from tactical 90-day procurement plays to multi-year technology roadmaps aligned with capacity expansion scenarios.
Contact PW Consulting to schedule a tailored executive briefing and to obtain access to the full Worldwide Ceramic Wafer Boat Market report and its complete dataset, supplier scorecards and scenario models.
For detailed analysis of this topic, please visit the official page: Worldwide Ceramic Wafer Boat Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com