

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Worldwide Information Technology Market Poised to Grow at 8.25% CAGR from 2026–2032, New Insight Report Finds

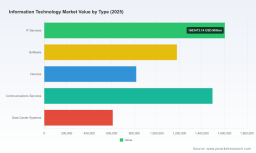
PW Consulting Strategic Brief: Worldwide Information Technology Market — 2026 Planning Playbook
Introduction
As enterprises finalize their 2026 investment roadmaps, the Worldwide Information Technology Market Report from PW Consulting offers a focused, practice-oriented briefing designed to convert market intelligence into actionable decisions. This executive release highlights the report’s strategic value for C-suite and business-unit leaders while following a “trailer” approach: we reveal high‑confidence macro trends and decision implications to support planning, while preserving detailed segment and supplier-level tables to encourage readers to consult the full report for transaction-ready figures and proprietary scenario models.
New Energy Box-type Substation Transformer Market
Executive snapshot
-
Market trajectory: Our analysis shows the global IT market expanded rapidly through the early 2020s — rising from approximately $3.9 trillion in 2020 to roughly $5.7 trillion in 2025 — and is projected to continue this momentum into the 2026–2032 forecast window.
Worldwide Website Optimization Tools Market -
Forecast dynamics: We model a compound annual growth rate (CAGR) of 8.25% across the 2026–2032 horizon, producing near‑term and medium‑term growth pathways that materially alter investment return profiles for core infrastructure, software platforms, and services.
Worldwide Boiler Feed Pumps (BFP) Market -
Market structure: Concentration remains modest at scale; the three‑firm and five‑firm concentration ratios are consistent with a market where hyperscale leaders coexist with broad ecosystems of specialized vendors and regional champions—creating both partnership opportunities and competitive threats.
What the full report delivers
The PW Consulting Worldwide IT report is built for decision-makers who must translate macro momentum into executable strategies. Key practical deliverables include:
-
Integrated market sizing and validated forecasts (base year 2025; historical analysis 2020–2025; forward view 2026–2032) with alternative scenario runs reflecting macro shocks and technology inflection points.
-
Vendor benchmarking and capability heatmaps across cloud, edge, AI stack, enterprise software and managed services—scored on technical depth, go‑to‑market reach, vertical expertise and partnership openness.
-
Investment playbooks with ROI templates for AI infrastructure, migration-to-cloud programs, data center refresh cycles, and device lifecycle strategies (including capex vs opex modeling and TCO comparators).
-
Go‑to‑market frameworks and commercial negotiation tactics for enterprise procurement teams, including contract levers, migration staging and supplier risk‑mitigation clauses.
-
M&A and partnership heat maps identifying attractive pockets for inorganic growth, carve‑outs and joint ventures, accompanied by valuation sensitivities tied to technology adoption curves.
-
Regulatory and supply‑chain risk matrices that translate tariff, export control and regional policy pressures into procurement and localization action items.
Market dynamics shaping 2026 decisions
-
AI infrastructure as a primary growth vector. Independent market trackers and our own scenario work converge on AI-related compute and platform investment as the single-largest driver of incremental IT spend in 2025–2026. This creates a two-tier planning imperative: accelerate compute and data capability where it yields product advantage, and rationalize legacy spending that does not align to monetizable AI outcomes.
-
Hardware cycle and semiconductor tailwinds. External forecasts point to elevated semiconductor revenue and a refresh-driven uplift for servers, storage and networking. For procurement and capital planning, this means earlier-than-usual refresh windows for data center infrastructure and a premium on secured supply lines.
-
Cloud and hybrid architectures continue to mature. Hyperscalers extend platform breadth while enterprise buyers prioritize hybrid architectures that balance performance, compliance and cost. Organizations must shape architectural roadmaps that treat cloud as an operational model as much as a vendor choice.
-
Regulatory fragmentation and supply‑chain resilience. Tariff policy volatility and geopolitical constraints are prompting firms to diversify manufacturing and sourcing, adopt cloud-based inventory visibility tools and increasingly model supplier shock scenarios as part of capital allocation.
-
Talent and operating-model reshapes. Demand for machine learning engineers, site reliability engineers, and cloud-native architects will outstrip supply in the near term. Workforce strategies that combine strategic hiring, targeted reskilling, and partner-led delivery models will preserve execution velocity without ballooning fixed costs.
Competitive landscape: how to read the field in 2026
The industry is defined by interplay among hyperscalers, platform incumbents, semiconductor and accelerator specialists, and global systems integrators. Our vendor analysis (summarized here at a strategic level) clarifies where each class of player matters to enterprise decision-makers:
-
Hyperscalers and cloud platforms (examples include providers with comprehensive cloud stacks and AI services) are the primary sources of scale, platform innovation and managed services. They set pricing dynamics for core IaaS/PaaS, accelerate enterprise AI adoption, and enable new vendor partnerships.
-
Hardware and accelerator leaders (notably suppliers of GPUs and purpose-built AI silicon) control performance inflection points. Their product cadence and availability drive capital timing for data center and edge investments.
-
Enterprise software and ERP specialists remain critical for business-process modernization; their roadmaps are increasingly tied to embedded AI capabilities and openness to hyperscaler ecosystems.
-
Global integrators and regional IT services firms are the execution engines. Their ability to deliver complex transformation at scale—combining systems integration, change management and managed services—differentiates outcomes for large enterprises.
For procurement and strategy teams, the choice of partner should be calibrated to your program’s primary objective: speed to market, cost efficiency, or differentiated IP. In many cases, blended partner models—hyperscaler platform + specialist hardware + systems integrator delivery—produce the best risk-adjusted outcomes.
Actionable recommendations for 2026 planning
Turn the market picture into a pragmatic 12–18 month plan by following these five steps.
-
Prioritize value-driven AI pilots. Select two high-value use cases with measurable KPIs and reserve budget for scalable infrastructure if pilots meet thresholds.
-
Run a supplier-concentration and resilience stress test. Model tariff scenarios and supplier outages; identify alternate sourcing and/or cloud-based fallbacks.
-
Rebalance capex/opex allocations. Where hyperscaler PaaS can deliver faster time-to-value, prefer opex; reserve capex for performance-sensitive, proprietary compute needs.
-
Reskill selectively and partner widely. Invest in T-shaped talent and short-term delivery partnerships to avoid over-hiring while retaining strategic capabilities.
-
Create a vendor disengagement playbook. For contracts with locked-in legacy costs, define staged exit or coexistence strategies to avoid value traps.
Why PW Consulting’s report matters to boards and exec teams
Our report combines longitudinal market measurement (2020–2025 historical baselines), a rigorous 2026–2032 forecast framework, and vendor-level intelligence derived from primary interviews, contract-level market signals and cross‑validated third-party forecasts. We triangulate public market indicators, trade‑show discovery (notably industry themes emerging from recent events), and authoritative market forecasts to produce a practical roadmap rather than an academic exercise.
Next steps and how to obtain the full intelligence
This briefing outlines the strategic levers and decision frameworks enterprises need to act in 2026. The full report contains the granular segmentation tables, regional and application breakouts, vendor scorecards and downloadable models that finance, procurement and transformation teams require for execution. For transaction-ready detail, scenario exports and bespoke advisory workshops, access the complete report through the PW Consulting publications portal or contact your account lead to commission a tailored briefing.
For detailed analysis of this topic, please visit the official page: Worldwide Information Technology Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com