

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Worldwide Aneurysm Coiling Market Poised to Reach USD 2.29 Billion by 2032, Growing at a 6.91% CAGR

PW Consulting Releases Strategic Brief: Worldwide Aneurysm Coiling Market — Why 2026 Is the Pivotal Year for Commercial and Clinical Strategy
PW Consulting today publishes an executive briefing drawn from its forthcoming Worldwide Aneurysm Coiling Market report (base year 2025; historical 2020–2025; forecast 2026–2032). The brief synthesizes market-scale trajectories, regulatory and reimbursement inflections, and competitor movements that will materially influence program and portfolio choices in 2026. Our analysis shows a resilient expansion path — underpinned by product innovation, shifting procedure settings, and concentrated competitive dynamics — with the market growing from a 2025 baseline into a multi‑billion-dollar opportunity by the end of the forecast window at a compound annual growth rate (CAGR) of 6.91% (2026–2032). This announcement frames the strategic value of the full report for corporate leaders, investors, and health system strategists considering near-term investments, launches, or consolidation.
Industrial Inverted Microscopes Market
Why this briefing matters for 2026 decision-makers
- Time-to-market and regulatory positioning: 2026 will be a year when new device approvals and EU/US regulatory progress materially change competitive access. Companies that align clinical, regulatory, and commercialization plans now can capture premium access during limited windows following product launches.
- Reimbursement and hospital economics are tightening: Procedural and inpatient payments are significant determinants of adoption pace and site-of-care economics. Our report models how physician fee schedules and DRG reimbursement translate into hospital margin signals for coiling procedures and adjacent neurovascular solutions.
- Portfolio prioritization under concentration: The market is led by a relatively small set of entrenched neurovascular players. That concentration raises both barriers and opportunities: incumbent distribution networks and clinician relationships matter, but differentiated technology or compelling commercial propositions can accelerate share gains.
Market trajectory at a glance
PW Consulting’s device-level demand model quantifies a steady recovery and expansion from the 2020–2025 historical window into the 2026–2032 forecast period. After the 2025 baseline, the market is projected to expand at ~6.9% CAGR through 2032, reaching a substantially larger size by the end of the forecast horizon. This expansion reflects a mix of factors we quantify in the full report: population and procedure incidence trends, device mix evolution (detachable vs. bio‑active vs. coated solutions), pricing dynamics, replacement cycles, and the commercialization of new entrants.
Worldwide Screencast Software Market
What the PW Consulting report delivers — practical modules
- Independent market sizing and growth drivers: A transparent, device‑level model covering historical activity and a 2026–2032 forecast, with sensitivity analyses for incidence, pricing, and channel mix.
- Competitive landscaping and capability mapping: Detailed profiles of incumbent manufacturers, emergent entrants, and adjacent technology suppliers, with go‑to‑market posture, IP posture, and clinician adoption levers.
- Regulatory and reimbursement playbook: Actionable assessments of EU MDR impacts, US regulatory timelines, Medicare fee schedule implications for physicians, and inpatient DRG economics for hospitals.
- Commercial and pricing strategies: Scenario-based guidance for hospital contracting, distributor engagement, and site-of-care transition strategies between inpatient and ambulatory settings.
- M&A and partnership screening: Transaction-ready themes identifying biologics/technology pairings, geographic expansion priorities, and consolidation targets aligned with clinical differentiation.
- Clinical adoption pathways: Evidence generation roadmaps customized to product archetypes (framing vs finishing vs bioactive), incorporating trial designs, KOL engagement strategies, and registry approaches.
Key dynamics shaping vendor strategy in 2026
Several adjacent dynamics will determine who captures disproportionate value next year:
High-Density PCBs Market
- Regulatory momentum: Recent EU MDR certifications have enabled new commercial entries in Europe and prompted incumbents to accelerate post‑market commitments. Companies that finalize regulatory dossiers and align clinical claims with payers will shorten commercialization cycles.
- Reimbursement mechanics: PW Consulting’s reimbursement mapping highlights two practical benchmarks that influence margin: physician payment for the CPT-coded coiling procedure and hospital DRG payments for ruptured‑aneurysm admissions. These inputs materially affect provider willingness to adopt higher‑cost devices or to shift cases to ambulatory care settings where appropriate.
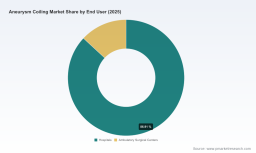
- Provider economics and site-of-care migration: Hospitals remain the predominant setting for complex aneurysm care, but ambulatory surgical centers and hybrid neurointerventional suites are growing as a function of throughput optimization and cost pressures. Commercial plans and suppliers must model differing adoption curves by site to appropriately price and support new products.
- Clinical differentiation and evidence: The fastest routes to adoption combine superior ease of use with robust clinical or real‑world outcomes. For certain product classes, surrogate endpoints and registry data will unlock hospital formulary inclusion faster than comparative randomized trials.
Competitive landscape — who to watch
The competitive field is anchored by multinational medical device companies and specialized neurovascular firms. Our competitive assessment focuses on capabilities, product families, distribution strength, and recent strategic moves that will matter to buyers in 2026.
- Medtronic (Dublin, Ireland) — A global incumbent offering a broad family of detachable coil solutions for endovascular embolization; strength lies in deep clinician relationships and integrated neurovascular portfolios.
- Stryker (Kalamazoo, MI, USA) — Competes with the Target family of detachable coils and leverages strong commercial channels in key markets.
- Terumo Neuro / MicroVention (Aliso Viejo, CA, USA) — Offers a full range of coil options and maintains technical breadth across platinum and specialty coil designs.
- Penumbra, Inc. (Alameda, CA, USA) — Markets an embolization system that pairs coils with adjunct technologies; integration of system components is a notable commercial differentiator.
- Johnson & Johnson MedTech — Cerenovus (New Jersey, USA) — Focuses on a family of coils spanning framing to finishing, supported by global neurosurgical sales forces.
- Regional and emerging players — Companies such as Kaneka (Japan/Europe launch), Balt Group (France), Phenox (Germany), MicroPort NeuroTech (China), and several U.S. and European specialists maintain focused portfolios, niche clinician relationships, and regional regulatory advantages.
- Disruptor watch: Neuravention (U.S.) — An early-stage innovator with plans for a 2026 FDA submission and potential commercial activity. If regulatory progress is realized, the company could become a strategic target for partnerships or acquisitions.
Notable recent developments underscore this dynamic: Kaneka’s i‑ED COIL secured EU MDR certification and launched commercially in Europe, demonstrating the speed at which an MDR‑cleared product can be monetized in core neurovascular markets. Separately, Neuravention’s planned FDA submission in early 2026 signals potential near‑term product evolution in the U.S. market that incumbents and investors should monitor closely.
How purchasers and investors should use the full report
PW Consulting designed the report as an operational tool, not just an academic exercise. Use cases include:
- Portfolio leaders: Reprioritize R&D and clinical investments against modeled adoption curves to optimize spend across framing vs finishing coil designs and next‑generation bioactive options.
- Commercial executives: Build pricing and contracting scenarios tied to hospital DRG economics and physician reimbursement, and construct a time‑phased launch playbook keyed to regulatory milestones.
- Business development and M&A teams: Screen targets against capability gaps, and size near‑term revenue uplift and integration effort for bolt‑on vs transformative deals.
- Health systems and payers: Anticipate supply‑side innovations and align internal protocols, procurement strategies, and site‑of‑care plans to maintain quality while managing cost-per-case.
- Private capital: Calibrate valuation assumptions to market growth, competitive concentration, and potential disruption from late‑stage entrants.
Methodology and confidence
PW Consulting’s projections combine device‑level demand modeling, primary interviews with clinicians and hospital procurement leads, regulatory timeline analysis, and payer reimbursement mapping. The report presents base, upside, and downside scenarios and includes sensitivity analyses for incidence rates, pricing trajectories, and substitution between device classes. Where granularity matters for commercial execution — e.g., hospital formulary thresholds, payer prior‑authorization drivers, or clinician training requirements — the full report offers actionable matrices and playbooks. Our confidence intervals and assumptions are documented to facilitate adaptation to company‑specific forecasts.
What we are deliberately withholding in this briefing
To preserve the report’s value as a transaction and strategy resource, we have intentionally omitted detailed regional and end‑user revenue splits, specific device‑class revenue breakdowns, and granular competitive share tables. These elements are key deliverables in the full report, and they are provided to paying subscribers to support confidential strategic planning, competitive benchmarking, and investment underwriting.
Next steps and how to access the full analysis
For executive teams preparing 2026 product launches, M&A pipelines, or commercial realignment, the full Worldwide Aneurysm Coiling Market report provides the granular intelligence needed to move from insight to action. PW Consulting offers tailored briefings that overlay your product portfolio or acquisition target on our model to produce transaction‑ready financials and a prioritized execution plan.
To request the complete report or to schedule a customized executive briefing, visit our report page or contact our industry practice leads. PW Consulting will run a limited number of confidential deep‑dive sessions in Q1 2026 to support clients preparing regulatory submissions, commercial launches, or strategic transactions in the aneurysm coiling space.
For detailed analysis of this topic, please visit the official page: Worldwide Aneurysm Coiling Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com