

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Worldwide Prescription Diet Pet Food Market to Reach USD 28,387.13 Million by 2032 at a 7.12% CAGR, with Top 3 Firms Holding 68.45%

Worldwide Prescription Diet Pet Food Market: Strategic Imperative for 2026
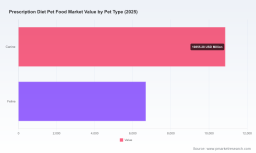
PW Consulting today releases a targeted industry briefing derived from our comprehensive Worldwide Prescription Diet Pet Food Market report (base year 2025, forecast period 2026–2032). For executives planning 2026 initiatives, the market’s macro trajectory is clear: the global prescription diet segment reached USD 17,540.0 Million in 2025 and is projected to expand at a compound annual growth rate (CAGR) of 7.12% through 2032, with the base-case model pointing toward roughly USD 28.4 Billion by 2032. The next 12–18 months will determine which players consolidate leadership, which channel models win veterinarian endorsement, and which supply chains remain resilient under inflationary raw-material pressure.
Ceiling-mounted OT Light Market
Why 2026 Is a Pivotal Year
-
Accelerating patient-level demand: Demographics of pet ownership (aging companion animals, higher spend per household) and stronger clinical adoption of therapeutic nutrition are sustaining long-term volume growth. That underlying demand, combined with premiumization in developed markets, is driving above-average category expansion versus conventional pet food.
Wheelchair Scale with Armrests Market -
Channel dynamics are intensifying: Prescription diets are still primarily dispensed via veterinary channels. Regulatory clarity—especially FDA rules requiring veterinary authorization in the U.S., AAFCO nutritional standards, and EU registration requirements—means go-to-market strategies must embed compliance and clinician engagement from product conception through commercialization.
Worldwide Electric Scooter Batteries Market -
Cost and supply-chain stressors: Raw-material volatility is an immediate operational risk. For example, chicken meal prices rose materially year-over-year, reflecting disease and supply disruptions; producers that lock in diversified sources or implement hedging and formulation flexibility will protect margins.
-
Market concentration and competitive pressure: The top commercial groups hold a significant share of the prescription diet market, creating high barriers to entry for new national brands but opening white-space opportunities in niche therapeutic formulations, value channels, and services that complement veterinarian workflows.
What PW Consulting’s Report Delivers (Practical Deliverables)
-
Proprietary market model: Transparent annual revenue series (historical 2020–2025; forecasts 2026–2032) with scenario toggles for demand elasticity, raw-material inflation, and channel mix, enabling CFOs to stress-test P&L outcomes for 2026 planning cycles.
-
Commercial playbooks: Actionable frameworks for veterinary engagement, sample and trial programs, field force deployment, and pricing strategies tied to reimbursement behavior and clinic economics.
-
Regulatory and quality checklist: A stepwise compliance roadmap covering FDA/CVM expectations, AAFCO labeling requirements, FSMA preventive controls, and EU registration constraints—mapped to commercial launch milestones.
-
Supply-chain and procurement playbook: Sensitivity analyses for key commodity inputs, supplier-risk heatmaps, recommended hedging instruments, and a contract-manufacturing versus in-house decision matrix.
-
Competitive benchmarking and capability scorecards: Comparative assessment of clinical portfolio breadth, veterinary channel strength, evidence-generation capabilities, brand trust metrics, and manufacturing footprint—designed for M&A screening and alliance decisions.
-
Innovation and R&D prioritization guide: Clinical differentiation strategies (e.g., renal, dermatology, weight management, gastrointestinal), required evidence thresholds for veterinary adoption, and recommended trial designs to shorten time-to-recommendation.
-
Risk register and mitigating actions: Actionable mitigations for regulatory shifts, recall scenarios, ingredient shortages, and reimbursement changes—mapped to trigger points for executive decision-making.
Competitive Landscape: Strategic Takeaways
-
Incumbent leaders maintain scale advantages. Core global players have built portfolios that span multiple therapeutic areas and maintain exclusive veterinary distribution relationships. These firms combine clinical trial capacity, long-standing clinician trust, and extensive cold-chain and co-packing capabilities. Their ability to bundle clinical nutrition with practice-level services (training, diagnostics integration, loyalty programs) is a key defensive moat.
-
Recent product and portfolio moves signal incremental innovation rather than category disruption. Several leading firms refreshed renal and wet-formula offerings, broadened pack-size options, and showcased line updates at major industry expositions—moves that optimize shelf productivity and clinician convenience rather than rework channel economics.
-
Mid-sized specialist players are focusing on focused therapeutic niches and faster clinical evidence generation to gain clinician mindshare. These companies are attractive M&A targets for larger groups seeking to plug portfolio gaps without the integration friction of a full-scale R&D acquisition.
-
Concentration metrics: The market shows a high degree of top-tier concentration, reinforcing that strategic plays in 2026 should either align with incumbents (partnerships, co-branding, distribution alliances) or be laser-focused on under‑served therapeutic areas and service models.
Operational and Commercial Priorities for 2026
-
Vet-first commercialization: Invest in repeatable clinician engagement programs—clinical champions, continuing education, and evidence-sharing platforms—rather than broad consumer advertising for prescription categories.
-
Regulatory-first product development: Embed regulatory and labeling requirements into early-stage formulation decisions; failing to demonstrate conformance to AAFCO/FDA/EC expectations will delay launches and erode market window opportunities.
-
Hedged sourcing and formulation flexibility: Given recent commodity shocks (e.g., notable year-over-year increases in chicken meal pricing), companies should pursue multi-sourcing, flexible formulations, and locked-price procurement to stabilize gross margins.
-
SKU rationalization and portfolio economics: Prune low-throughput SKUs, optimize pack-size tiers that improve clinic inventory turnover, and align product formats (wet vs dry) with clinic dispensing economics.
-
Service and data monetization: Integrate nutrition plans into clinic practice management systems and telehealth modules to create recurring revenue streams and capture real-world adherence data—an emerging differentiator in clinician purchasing decisions.
Investment and M&A Lens
-
Target capabilities should include clinical-evidence pipelines, strong veterinary distribution contracts, and manufacturing scale for wet formulas. Buyers seeking near-term returns should prioritize targets that add defensible clinician relationships and cost-saving manufacturing synergies.
-
Joint ventures with veterinary networks and strategic minority stakes in diagnostic companies can accelerate route-to-recommendation by bundling therapeutic nutrition with point-of-care diagnostics.
-
Private-label and contract-manufacturing partnerships represent lower-capex routes to expand distribution footprint while mitigating supply-chain risk—an attractive play for regional players aiming to scale quickly.
How to Use This Report for 2026 Decision-Making
-
Board and investor briefings: Translate scenario outputs into funding requests, capex prioritization, or defensive measures (e.g., supplier contracts) required to protect 2026 margin targets.
-
Commercial launch planning: Use our evidence thresholds and clinician engagement playbooks to de-risk product launches and compress the time from launch to clinic adoption.
-
Procurement and manufacturing strategy: Apply the supply-chain sensitivity dashboard to set procurement policy, negotiate fixed-price contracts, and decide on internal manufacturing investments versus CMOs.
-
M&A screening: Leverage capability scorecards and concentration analysis to identify targets that deliver immediate clinical access or add differentiated therapeutic formulations.
PW Consulting’s briefing is intentionally crafted as a decision-ready executive summary. It demonstrates the analytical depth and practical orientation that senior teams need to act in 2026—while preserving the granular segmentation matrices, detailed regional and application splits, and downloadable datasets that underpin our models. Those datasets, including the full breakouts and interactive forecast model, are available in the full report and data annex on the PW Consulting report page.
To discuss tailored scenarios for your organization, license the full dataset, or arrange a bespoke advisory session to translate these findings into a 90‑day action plan, contact PW Consulting’s Strategic Insights team.
For detailed analysis of this topic, please visit the official page: Worldwide Prescription Diet Pet Food Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com