

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Pearls Market Outlook — Asia Pacific Commands USD 1,873.6 Million Share, Underscoring Regional Dominance

Pearls Market 2026 Preview: Strategic Playbook for Decision‑Makers — PW Consulting Releases Pearls Market (Base Year 2025) Intelligence Brief
Executive summary
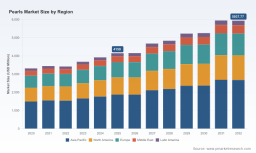
PW Consulting today unveils the Pearls Market report (base year 2025), an action‑oriented market intelligence product designed to equip corporate strategists, retailers, supply‑chain leaders and investors with the insights required to make high‑stakes decisions in 2026. The global pearls market — valued at approximately USD 4,150 Million in 2025 — is poised for steady expansion through the forecast window (2026–2032), driven by a projected compound annual growth rate (CAGR) of 5.25%. Our analysis combines macro forecasting with practical playbooks on sourcing resilience, premiumization, sustainability compliance and channel economics.
Spironolactone Drugs Market
Why this report matters for 2026 planning
-
Timing: As market growth accelerates into the latter half of the decade, 2026 will be a pivot year for strategic repositioning — between value and luxury segments, between vertically integrated incumbents and nimble disruptors, and between traditional distribution and digital experiential commerce.
Network Monitoring Tools Market -
Policy & reputation risk: The industry is undergoing rapid institutionalization of standards and sustainability metrics. Recent sector initiatives and expanded classification guidance are reshaping provenance claims and consumer trust landscapes.
Reinforced Modified Polyethylene Market -
Fragmented supply structure: Measured concentration ratios indicate a distinctly fragmented industry structure, which creates opportunities for consolidation, niche differentiation and value chain capture.
Market trajectory — headline macros
Our bottom‑up model projects the market moving from a 2025 base of roughly USD 4.15 billion to an anticipated market size approaching USD 5.94 billion by 2032 under the central forecast path. That trajectory reflects a 5.25% CAGR across the 2026–2032 forecast window, with demand patterns shaped by premium jewelry purchases, evolving bridal and gifting cycles, and differentiated product narratives (provenance, sustainability, and rarity).
Key industry dynamics shaping 2026 decisions
-
Standards and science‑based sustainability: Institutional developments in 2025 — notably the launch of a global development community and the expansion of industry technical guides — are accelerating the adoption of standardized sustainability reporting and classification frameworks. For operators and brands, this raises the bar for traceability systems, eco‑labelling and consumer communication strategies.
-
Geopolitical and trade friction: Trade measures and tariff discussions affecting certain major producing regions create tangible supply and pricing volatility. Companies that proactively diversify procurement and build hedged inventory strategies will reduce margin erosion and maintain customer continuity.
-
Channel evolution: Luxury verticals continue to favor integrated product storytelling and provenance checks, while mid‑market channels are experimenting with compelling value propositions grounded in design rather than raw rarity. Digital‑first experiences and hybrid omnichannel models remain decisive battlegrounds for customer acquisition in 2026.
-
Fragmentation as strategic opportunity: With leading concentration metrics indicating a low degree of concentration among the top firms, scale plays and targeted consolidation remain high‑impact levers for those aiming to control premium supply or to access specialized farming networks.
Strategic implications for corporate decision‑makers
-
Supply chain resilience and sourcing playbooks: Build layered sourcing strategies that combine long‑term partnerships with high‑quality farms, contingency inventory buffers, and flexible procurement contracts. Invest in provenance technologies (e.g., blockchain anchoring, independent third‑party verification) to transform traceability into a commercial advantage.
-
Premiumization versus market expansion: Use a dual product architecture — a premium, provenance‑led line for luxury channels and a design‑ and value‑led line for broader audiences. Pricing architecture should reflect not just gem characteristics but storytelling and sustainability credentials.
-
Regulatory and standards readiness: Anticipate rising compliance costs related to expanded classification and disclosure requirements. Early alignment with newly published standards will reduce rework and accelerate market access, particularly in high‑value export markets.
-
M&A and partnership criteria: Target acquisitions that deliver either upstream security (controlled farming capacity) or downstream reach (retail and e‑commerce platforms). Given the fragmented market, bolt‑on deals and strategic JV structures remain more attractive than large scale roll‑ups in 2026.
-
Branding and consumer education investments: Allocate marketing spend to third‑party verification and narrative development — particularly on sustainability outcomes and farm‑to‑finger metrics that resonate with premium customers.
Competitive landscape — who matters and why
The pearls sector is characterized by a mix of century‑old luxury houses, family‑owned producers and large manufacturing clusters. PW Consulting’s competitive analysis synthesizes capability maps, ownership models and route‑to‑market strategies of the industry’s most consequential players:
-
Mikimoto (Tokyo, Japan) — an archetypal luxury house and early pioneer of cultured pearls. Its brand equity and product craftsmanship remain a benchmark for premium Akoya positioning; strategic action for challengers includes investing in signature design narratives and selective collaborations to erode heritage advantage.
-
Tasaki (Kobe, Japan) — a vertically integrated luxury jeweler controlling stages from farming to final design. Tasaki’s full‑stack model highlights the commercial value of upstream integration for quality control and margin capture.
-
Paspaley (Darwin, Australia) — a family‑owned leader in Australian South Sea pearls emphasizing sustainable, high‑quality farming. Its model spotlights sustainability as a premium differentiator and a protective moat in luxury channels.
-
Jewelmer (Makati, Philippines) — specializes in golden South Sea pearls with integrated cultivation and high jewelry development. Jewelmer’s positioning underlines the commercial potential of color‑led niche specializations and storytelling rooted in a single provenance.
-
Atlas Pearls (Subiaco, Australia) — a major producer and distributor demonstrating scale in white and silver South Sea categories; its distribution footprint is illustrative for companies focused on B2B wholesale expansion into global jewelry supply chains.
-
Chow Tai Fook (Hong Kong) — a dominant regional retailer with strong market access across Asia. The firm exemplifies how retail reach and promotional velocity can influence demand patterns at scale.
-
Zhejiang Grace Pearl Jewelry Co., Ltd (Zhuji, China) — emblematic of the freshwater production and manufacturing cluster, where manufacturing scale and verticalized supply chains drive affordability and rapid product iteration.
Across the competitive set, winners in 2026 will be those who combine provenance credibility, supply security and consumer platform mastery. The report profiles each firm’s strategic assets and offers comparator benchmarks for performance and positioning.
Recent sector developments — what changed in 2025 and why it matters
-
Industry initiative launch: The formation of a Global Pearl Development Community in late 2025 is a structural shift toward coordinated sustainability, standards and innovation across saltwater and freshwater sectors. Companies engaged early will influence standards and gain reputational credit.
-
Expanded technical guidance: The expanded industry classification guide introduced in 2025 elevates the rigor of producer claims. This has downstream consequences for labeling, retail disclosure and cross‑border trade approvals.
-
Market reporting and scientific monitoring: Updated sector reports and scientific monitoring initiatives strengthen the evidentiary basis for provenance and environmental claims — useful for premiumization and risk mitigation strategies.
-
Trade policy noise: Ongoing tariff discussions affecting certain sourcing channels introduce cost and lead‑time uncertainties. Scenario planning for alternative sourcing and pricing pass‑through will be essential for margin protection.
What the Pearls Market report contains — practical deliverables
PW Consulting’s Pearls Market report is structured to be operationally useful. Key deliverables include:
-
Market sizing and seven‑year forecasts (2026–2032) with scenario variations and sensitivity analysis.
-
Industry structure and concentration diagnostics, including CR3/CR5 analysis and implications for consolidation strategy.
-
Competitive intelligence dossiers for leading producers, retailers and manufacturer clusters, with capability matrices and strategic options.
-
Actionable go‑to‑market playbooks for premiumization, volume expansion, omnichannel distribution and licensed partnerships.
-
Supply‑chain resilience frameworks, procurement templates and a decision toolkit for inventory hedging and diversification.
-
Regulatory and standards readiness checklists aligned to the latest industry guidance and sustainability reporting expectations.
-
M&A target screening criteria and valuation heuristics tailored to the fragmentary structure of the industry.
Methodology and credibility
The report synthesizes primary interviews with producers, dealers and retailers; trade data; on‑site farm and manufacturing visits conducted during the 2020–2025 historical window; and a proprietary forecasting model calibrated to observed demand cycles and price elasticity patterns. Our approach balances quantitative rigor with qualitative industry knowledge to deliver prescriptive recommendations rather than abstract forecasts.
How to use this intelligence in 2026
-
Board-level strategy: Use the sizing, scenarios and concentration diagnostics to validate inorganic growth options, capital allocation and risk appetite.
-
Commercial leadership: Deploy the pricing and channel playbooks to optimize assortment and promotional calendars aligned to proven consumer triggers.
-
Supply‑chain teams: Implement the procurement templates and traceability frameworks to protect margins and satisfy evolving regulatory disclosure requirements.
-
Investors and acquirers: Leverage the M&A screening and valuation heuristics to prioritize targets that offer upstream security or downstream market access.
Call to action
PW Consulting’s Pearls Market report provides the strategic scaffolding required to act decisively in 2026. The document demonstrates the evidence base and the tactical playbooks; to access the granular segment tables, regional breakdowns, and downloadable data appendices that underpin our conclusions, please visit the full report page.
For detailed analysis of this topic, please visit the official page: Pearls Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com