

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Worldwide Portable Gaming Consoles Market Reaches USD 16.5 Billion in 2025, Set to Expand at 8.98% CAGR Through 2032

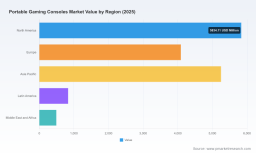
Worldwide Portable Gaming Consoles Market 2026: Strategic Imperatives from PW Consulting
As portable gaming consoles transition from niche enthusiast gadgets to a mainstream pillar of interactive entertainment, 2026 will be a watershed year for strategic decision‑makers. PW Consulting’s latest market study—anchored on a 2025 base year and projecting through 2032—maps the structural shifts, technology inflection points, and competitive dynamics that will determine winners and laggards in the years ahead. This press release highlights the report’s strategic value for corporate leaders and institutional investors while preserving the granular segment-level intelligence for subscribers.
Worldwide Magnesium Hydroxide Fire Retardant Additives Market
Executive snapshot: scale, pace and market structure
The portable gaming consoles market has more than doubled in five years, expanding from roughly USD 8.45 billion in 2020 to USD 16.5 billion in 2025. PW Consulting projects continued expansion across the 2026–2032 forecast window at a compound annual growth rate of approximately 8.98%, with the total market approaching the low‑30 billions (USD) by the end of the period. These topline dynamics are underpinned by ongoing product innovation—hybrid handheld/home forms, Windows‑based portable PCs, cloud‑first handhelds, and foldable/expandable displays—paired with accelerating consumer uptake in both core and adjacent gamer cohorts.
Worldwide Brake Relining Service Market
Market concentration remains high: the top three manufacturers account for the bulk of industry value, and the top five intensify that dominance. Such concentration creates both barriers and opportunities: incumbent IP and service ecosystems can sustain premium pricing and margins, while agile entrants can capture niche share through price, design differentiation, or platform partnerships.
Worldwide Application Protection Market
Why this study matters for 2026 corporate decisions
- Investment prioritization — The report converts macro momentum into actionable capital allocation guidance by linking device adoption curves to likely revenue trajectories for first‑party software, hardware upgrades, and subscription services.
- Supply chain strategy — We quantify the sensitivity of device economics to component cost drivers—including advanced DRAM, OLED/POLED displays, and semiconductor availability—and offer mitigation pathways (dual sourcing, strategic inventory, long‑term contracts, and co‑development agreements).
- Platform and content roadmaps — For platform owners and first‑party studios, the study models trade‑offs between backward compatibility, cloud streaming, and native performance to inform 18–36 month content investment plans.
- M&A and partnership scouting — Subscribers gain a prioritized target list and a clash‑tested integration playbook to accelerate time‑to‑market for complementary hardware, middleware, or cloud service assets.
Report deliverables: practical tools inside
PW Consulting’s report is structured for immediate operational use by corporate strategy, product, and supply chain teams. Key deliverables include:
- Top‑line market forecasts and scenario analyses (base, constrained supply, and aggressive adoption) calibrated to 2025 baseline demand.
- Component cost sensitivity models linking semiconductor, DRAM, and display pricing to device BOM and margin outcomes.
- Risk maps covering regulatory compliance (battery safety and energy efficiency), geopolitics (export controls), and raw material exposure.
- Commercial go‑to‑market playbooks for OEMs, platform holders, and retail channels covering pricing, bundling, and service monetization.
- Competitive positioning matrices, strategic fit assessments, and M&A diligence checklists.
To preserve commercial value for stakeholders, the report deliberately withholds granular regional and application‑level revenue splits in this release; subscribers can access the full segmentation datasets and downloadable models on PW Consulting’s report portal.
Competitive landscape: what the leaders are doing
The portable gaming ecosystem in 2026 is defined by a coexistence of distinct value chains: proprietary hybrid consoles with deep first‑party libraries, PC‑centric handhelds optimized for AAA titles, cloud‑native devices targeting lower upfront cost, and a broad long‑tail of retro/enthusiast hardware. Key strategic moves by industry participants illustrate divergent but complementary plays:
- Nintendo Co., Ltd. — Building on legacy strengths, Nintendo’s hybrid device released in mid‑2025 reinforces the company’s dominance through backward compatibility and an entrenched first‑party software catalog. Strategic takeaways: Nintendo’s moat remains content and user experience; competitors will need unique value propositions (performance, cross‑platform integration) to peel off core gamers.
- Valve Corporation — Valve’s Steam Deck design philosophy prioritizes open PC access and modder friendliness. Ongoing development of a next‑generation model highlights the technical trade‑offs between silicon upgrades and battery life. Strategic takeaway: Valve plays to ecosystems and platform flexibility—partners or rivals that enable a richer PC game experience on handhelds can unlock high‑value niche segments.
- ASUS ROG & Microsoft (Xbox partnership) — Windows‑based high‑performance handhelds launched with AMD Ryzen AI Z2 series silicon represent a premium performance play and a clearer Xbox/PC ecosystem push. Strategic takeaway: This collaboration signals an aggressive bid to capture AAA portable gamers who demand native Windows compatibility and Game Pass integration.
- Lenovo — Experimentation with form factors, most visibly a foldable POLED concept, signals an exploratory innovation agenda aimed at expanding use cases beyond gaming (productivity, streaming). Strategic takeaway: Manufacturers focusing on form factor and multi‑use propositions can open new TAM adjacent to pure gaming.
- Sony & Microsoft (streaming and ecosystem strategies) — Sony’s handheld streaming approach and Microsoft’s device ecosystem partnerships show that cloud streaming is now a complementary, not entirely substitutive, route—especially where high‑latency reliability improves. Strategic takeaway: Content owners should view cloud as an extension of device strategy that can accelerate monetization in markets with constrained hardware access.
- Specialist OEMs (AYANEO, GPD, Anbernic, Powkiddy) — These firms address enthusiast and budget segments, though they face margin pressure from component cost volatility. Strategic takeaway: Success here depends on tight BOM control, targeted feature sets, and community engagement.
- Peripheral & cloud device players (Logitech, Razer) — Positioning ranged from cloud‑first handhelds to accessory ecosystems. Strategic takeaway: Hardware accessory companies can monetize cross‑platform compatibility and service partnerships without owning the full stack.
Industry dynamics and near‑term risks
Several cross‑cutting themes will shape 2026 outcomes:
- Component cost pressure — Demand for high‑density DRAM and advanced display panels, coupled with semiconductor export controls, has raised BOM volatility. Companies must model scenarios where component inflation persists and plan protective procurement and pricing strategies accordingly.
- Battery and regulatory compliance — Evolving regional battery safety and energy efficiency standards require proactive certification roadmaps, especially for devices integrating higher‑capacity batteries or new fast‑charge tech.
- Geopolitics — US‑China trade tensions and controls on advanced silicon exacerbate sourcing complexity, making flexible manufacturing footprints and alternative supplier development strategic imperatives.
- Form factor innovation — Foldable displays and hybrid designs present an opportunity to broaden use cases, but they also raise cost and reliability risks that require staged commercialization plans.
Practical recommendations for 2026 strategy
Based on our analysis, PW Consulting recommends the following actionable measures for executives planning for 2026:
- Prioritize supply resilience — Establish dual‑source relationships for critical components, lock in key long‑lead items through strategic pre‑orders, and create modular BOMs that allow feature‑level downgrades without reengineering.
- Align device strategy with content economics — If you control first‑party content, favor hardware decisions that maximize lifetime value (backward compatibility, cross‑buy incentives). Platform players without owned content should pursue partnerships and service bundling to capture recurring revenue.
- Differentiate via UX and ecosystem — Performance alone will not guarantee share. Invest in storefront UX, cross‑device saves, and cloud‑assisted features that lower friction for users moving between devices and living rooms.
- Embed regulatory and sustainability costs early — Factor battery certification, take‑back programs, and energy labeling into early cost models to avoid late‑stage compliance shocks.
- Leverage strategic M&A — Pursue tuck‑ins for middleware, display supply relationships, or cloud streaming partners to accelerate capability building without multi‑year in‑house development timelines.
Next steps and where to access the full intelligence
PW Consulting’s Worldwide Portable Gaming Consoles Market report delivers the forecasts, scenario models, and competitive playbooks executives and investors need to make confident 2026 decisions. The report contains the full segmentation datasets, regional analyses, channel breakdowns, and downloadable financial models that are intentionally summarized here to preserve commercial value.
For immediate access to the comprehensive dataset, subscriber‑only appendices, and bespoke advisory engagements (including a tailored 90‑day action plan and supplier risk audit), please visit PW Consulting’s research portal and request the full report package.
Prepared by PW Consulting’s Global Head of Industry Analysis, this market study combines proprietary shipment tracking, supplier interviews, and scenario modelling to deliver pragmatic recommendations—bridging boardroom strategy with factory‑floor decisions.
For detailed analysis of this topic, please visit the official page: Worldwide Portable Gaming Consoles Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com