

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Worldwide Methylparaben Market Poised to Grow at a 4.5% CAGR Through 2032

Worldwide Methylparaben Market — Strategic Insights for 2026 Decision‑Makers
Executive teaser
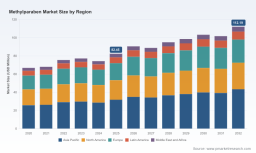
PW Consulting’s latest Worldwide Methylparaben Market report (base year 2025) synthesizes commercial, regulatory and supply‑chain intelligence designed to inform high‑stakes decisions in 2026. The market has expanded from a 2020 baseline into a mid‑market chemical with rising strategic importance across cosmetics, pharmaceuticals and selected food applications. Our analysis projects steady expansion through the end of the decade — a compound annual growth rate (CAGR) of 4.5% across the 2026–2032 forecast window — and provides the playbooks companies need to preserve margin, limit regulatory exposure, and capture growth where it matters most.
Dry Flexible Termination Market
Market snapshot — what the headline numbers mean for strategy
Using 2025 as the anchoring year, PW Consulting’s modeled market sizing shows recovery from short‑term cyclical swings and momentum into the mid‑term: the global methylparaben market grew noticeably from 2020 and is forecast to continue upward, reaching a materially larger market by 2032 under our base case. The market exhibits moderate concentration: the top three suppliers account for roughly 42% of global supply, while the top five control about 59%. These dynamics create both opportunities for scale players to defend margins and for challengers to exploit niche, specialty and geography‑specific openings.
Worldwide Insulated Yard Hydrant Market
Drivers, headwinds and structural signals (what to act on in 2026)
- End‑market resilience in personal care and pharmaceuticals. Continued demand for preservative functionality in cosmetics and certain pharmaceutical formulations underpins steady underlying consumption. Growth is differentiated by product grade and regulatory acceptability, making grade strategy a commercial priority.
- Regulatory intensity is now a business variable, not just compliance cost. Longstanding EU rules that cap methylparaben concentration in cosmetics and require explicit labeling have shifted product formulation and procurement strategies. Newer national restrictions, such as limits on use in pediatric oral care, and country‑level trade remedies have increased the cost of doing business in some jurisdictions.
- Feedstock pressure and input cost volatility. P‑hydroxybenzoic acid — a key feedstock — experienced a notable price uptick in late 2024 driven by upstream phenol tightness. This has amplified margin pressure across the value chain and increased incentive to optimize inventory and hedging strategies.
- Trade policy and duties matter for sourcing. Recent anti‑dumping measures on certain imports have altered viable sourcing lanes and merit strategic supplier diversification, nearshoring or reshoring evaluations in 2026 procurement plans.
- Consolidation and specialty differentiation. Degree of concentration suggests acquisitions remain an attractive route to bolt on technical capabilities (e.g., low‑impurity grades) and secure capacity. At the same time, small and medium suppliers can win by focusing on regional responsiveness and certification stacks favored by end users.
Competitive landscape — how incumbents are positioned
The competitive set balances global chemical majors with regional specialists. Supply leadership is split between large, integrated producers and smaller, more focused manufacturers that emphasize USP/food/cosmetic grades and export capabilities. Recent public developments underscore the strategic postures we track:
Pizza Prep Tables Market
- Eastman Chemical Company (USA) — A portfolio player supplying methylparaben for personal care and pharmaceutical applications. Recent REACH compliance updates signal a sustained commitment to European markets and regulatory alignment; use this as an indicator of where Eastman will prioritize capex and customer engagement.
- Spectrum Chemical Mfg. Corp. (USA) — USP/NF grade production and laboratory‑scale supply make Spectrum a go‑to for pharmaceutical customers and R&D partners. Their strength lies in quality certification and volume flexibility for regulated applications.
- Celanese Corporation (USA) — With capabilities in cellulose derivatives and specialty chemistries, Celanese has expanded its low‑impurity methylparaben portfolio — a signal that premium, regulatory‑conscious grades are a focal growth path for established majors.
- Nippon Shokubai Co., Ltd. (Japan) — High‑purity product focus and regional reach position Nippon to serve the demanding Asian cosmetic and personal care segments where certification and supply reliability are decisive.
- Shanghai Trustin Chemical Co., Ltd. (China) — Export‑oriented manufacturing and cost competitive positioning make Trustin a primary supplier for cost‑sensitive channels; trade remedies and raw material volatility will be key risk vectors for their customers.
- Wanxiang Jingliu Chemical Co., Ltd. (China) — A specialist in paraben preservatives including methylparaben, Wanxiang competes on product breadth and close ties to downstream formulators in food, pharma and cosmetics.
Taken together, these players illustrate two structural routes to competitiveness in 2026: scale + regulatory compliance (majors) versus flexibility + proximity (specialists).
What the full report contains (operational, actionable deliverables)
PW Consulting’s report is designed as a decision‑support toolkit for executives, commercial leaders and supply‑chain teams. The package includes:
- Robust market sizing and forecasting methodology with scenario and sensitivity testing (base, upside, downside) across the 2026–2032 horizon.
- Supply‑side mapping and capacity atlas showing plant locations, vintage, technical grades and likely expansion candidates.
- Raw material cost model that quantifies margin impact from feedstock swings and presents hedging and contract strategies.
- Regulatory impact assessment modeling the commercial effects of concentration limits, labeling mandates and national restrictions (with a graded risk matrix by use case).
- Commercial playbooks tailored to grades and end markets: price‑to‑win frameworks, tender strategies, and certification roadmaps for cosmetic, pharmaceutical and food customers.
- Supplier scorecards and go‑to‑market templates for procurement, including suggested KPIs (lead times, certification coverage, quality defect density, cost‑to‑serve).
- M&A heatmap and integration checklist highlighting targets that deliver grade capability, regional market access or feedstock integration.
- Client workshops and executive briefings with scenario walk‑throughs, tailored to strategic planning cycles in 2026.
Note: detailed regional and application splits, market share tables, and full numerical segmentations are intentionally reserved for the full report and interactive dashboards to preserve the “trailer” effect and direct stakeholders to our platform for raw datasets and downloadable models.
Strategic playbook for 2026 — prioritized actions
- Immediate (Q1–Q2 2026) : Lock in 2026 purchase contracts for critical feedstock to mitigate carryover price shocks; refresh compliance checklists for product portfolios sold in regulated jurisdictions; run a rapid supplier stress test for single‑source exposures.
- Near term (6–12 months) : Reassess product grade mix and commercialization strategy — invest in low‑impurity grades where premium pricing is achievable; pilot reformulations for high‑risk cosmetic SKUs to reduce regulatory friction; evaluate inventory optimization and dynamic pricing pilots.
- Medium term (12–36 months) : Pursue targeted M&A or JV opportunities to secure capacity in favorable geographies or to add technical grade capabilities; consider nearshoring or localized blending hubs to de‑risk trade remedies and shorten lead times.
- Cross‑cutting governance : Implement a regulatory early‑warning KPI, embed feedstock cost scenario models into monthly commercial reviews, and institute decision gates for any price/contract commitments above defined thresholds.
KPIs and decision triggers to include in 2026 planning
- Input cost pass‑through percentage and days‑to‑cover for raw materials.
- Share of sales compliant with highest‑risk jurisdiction requirements (tracked by grade).
- Supplier diversification index (weighted by spend and lead time variability).
- Product reformulation pipeline velocity (number of SKUs reformulated and time‑to‑market).
- Commercial margin delta by grade and by geography (monthly rolling).
Why this report is strategically valuable for 2026
2026 will be a year where regulatory pressure, raw material volatility and trade policy interact to create uneven opportunities across grades and geographies. PW Consulting’s report converts these macro trends into executable strategies: it helps procurement teams secure resilient sourcing, guides R&D and product management on where to invest in reformulation, and equips M&A and corporate development with a prioritized target list aligned to commercial value. Our integrated pricing and raw material model allows firms to stress‑test scenarios before committing capex or launching new product lines — turning uncertainty into competitive advantage.
Next steps & access
For procurement, R&D and strategy teams preparing 2026 plans, the next step is a focused briefing to align our scenario outputs to your P&L and risk tolerances. The PW Consulting report package includes interactive dashboards, downloadable models and an optional client workshop to translate insights into a 90‑day action plan. Visit our report landing page to access the full dataset, download the executive summary, or schedule a tailored briefing with our senior analysts.
For detailed analysis of this topic, please visit the official page: Worldwide Methylparaben Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com