

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Worldwide Automotive Fuel Level Sensor Market to Grow at 3.2% CAGR (2026–2032), Reaching USD 1,184.35 Million by 2032 as Asia Pacific Leads with USD 413.08M

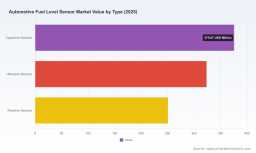
Worldwide Automotive Fuel Level Sensor Market: Strategic Imperatives for 2026
Executive summary
PW Consulting’s latest market study on the Worldwide Automotive Fuel Level Sensor market positions firms to make high-confidence strategic choices in 2026. The global market reached approximately USD 950 Million in 2025 (base year) after a period of volatility between 2020–2025, and our outlook projects steady expansion at a compound annual growth rate (CAGR) of 3.2% across the 2026–2032 forecast window — with the market approaching roughly USD 1.18 billion by 2032 under the base-case scenario.
Worldwide Information Stewardship Applications Software Market
This briefing synthesizes the study’s most actionable insights without disclosing the granular regional, application or type-level splits that are reserved for the full report. The objective is to give executives, product leaders, procurement heads and investors enough high-grade intelligence to prioritize decisions in 2026, while encouraging direct access to the full dataset and decision tools for execution.
Virtual and Hybrid Meeting Solutions Market
Why this market matters for 2026 decisions
-
Regulatory acceleration: Tightening emissions and fuel monitoring requirements are raising the technical bar for fuel-level sensing in internal-combustion and hybrid platforms. OEMs and suppliers that can demonstrate precise, robust measurement and integration will win platform-level design slots starting in 2026.
Worldwide Electromechanical Slip Ring Market -
Technology differentiation: Sensor technology choices (capacitive, ultrasonic, resistive and hybrid approaches) now have direct procurement and cost implications across fuel-system module sourcing, ECU integration and warranty exposure. IP in calibration and multi-fuel compatibility is a strategic asset.
-
Market structure and scope: The market is concentrated — the top three and five vendors capture a meaningful portion of revenue — creating both an opportunity for scale players to defend margins and for specialized suppliers to seek premium niches or acquisition exits.
-
Transition risk and offsetting demand: While electric vehicle adoption reduces long-run demand for ICE fuel-system components, near- and mid-term factors — regulatory requirements, heavy-duty and commercial fleet dynamics, aftermarket replacement and multi-fuel compatibility — sustain a positive revenue trajectory that requires nuanced planning rather than binary bets.
Key drivers and dynamics shaping 2026 strategy
-
Regulatory push: New regional emission standards introduced around 2025 have made granular fuel-level monitoring part of combustion optimization strategies. For OEM powertrain teams, this elevates fuel sensors from commodity line items to control-system enablers that affect fuel-management algorithms.
-
Supply-chain stress: Semiconductor supply tightness in 2022–2023 materially extended lead times for sensor ICs. Our analysis shows that procurement and manufacturing lead-time risk remains a top-three operational vulnerability for sensor suppliers and OEMs; contingency sourcing and IC-design-for-availability are mandatory program activities.
-
Technology bottlenecks: Capacitive sensing technology has emerged as the most widely adopted approach in recent platforms due to accuracy in plastic tanks, while ultrasonic solutions offer non-intrusive advantages but require sophisticated calibration for foaming and fluid-surface effects. Suppliers that combine sensing hardware with calibration algorithms and diagnostics will secure superior OEM position.
-
Safety and durability: Updated crashworthiness and fuel-system integrity standards require sensors to sustain severe mechanical events and to report failure modes meaningfully to vehicle diagnostics. This expands the supplier scope to include crash-grade sealing, diagnostic messaging, and certification services.
Competitive landscape — what top suppliers are doing
The competitive set is a mix of global Tier-1s, specialized sensor houses, and electronics integrators. Below are concise strategic readings on the leading players covered in the study.
-
Robert Bosch GmbH (Gerlingen, Germany) — Strength in integrated modules and OEM systems engineering. Bosch’s product breadth (capacitive, float-based and ultrasonic offerings) and deep integration in fuel-tank modules make it a preferred partner for program-level supply. Strategy implication: Bosch will leverage systems presence to lock in module-level margins; competitors should target component-level differentiation or platform-specific niches.
-
Continental AG (Hanover, Germany) — Focused on sender units with integrated thermal sensing and strong OEM ties. Recent supplier nominations on mainstream platforms underscore Continental’s program pipeline. Strategy implication: Suppliers seeking program wins should map Continental’s platform footprint and prequalify thermal and diagnostic features.
-
Denso Corporation (Kariya, Japan) — Close OEM relationships with Asian automakers and a portfolio spanning reed-switch and capacitive sensors for ICE and hybrid vehicles. Strategic partnerships and JDAs with OEMs enable early specification influence.
-
BorgWarner Inc. (Auburn Hills, MI) — Emphasizing multi-fuel compatibility following integration of legacy Delphi assets; strong presence in North America and Europe. Strategy implication: Multi-fuel capability is a differentiator for fleet and commercial programs.
-
Visteon Corporation (Van Buren Township, MI) — Moves to integrate fuel-level sensing into cockpit and cluster offerings create new value propositions where sensor data is used for driver information and fuel-economy feedback.
-
Sensata Technologies (Attleboro, MA) — Rapid product innovation; a recent launch expanded fluid-property sensing with fuel-level detection capability. Sensata’s focus on heavy-duty and industrial interfaces positions it well for commercial-vehicle aftermarket and OEM segments.
-
CTS Corporation (Lisle, IL) — Specializes in resistive/variable-resistor electronic sensors and has completed validation programs with heavy-engine OEMs, which is critical for credibility in commercial powertrain applications.
-
TE Connectivity (Schaffhausen, Switzerland) — Known for ruggedized float and non-contact solutions for off-road and marine-adapted applications; strength in harsh-environment reliability.
-
Gill Sensors & Controls (Southampton, UK) — Niche leader in ultrasonic and capacitive technologies for motorsport and specialized commercial vehicles; non-intrusive measurement capabilities provide opportunities in retrofit and motorsport segments.
-
Methode Electronics (Chicago, IL) — Hall-effect-based sensors positioned for light-duty truck pump-module integration; expertise where electro-mechanical coexistence is required.
Recent vendor moves to watch (selected)
-
Sensata’s late-2024 product launch expands fluid-property sensing into level detection — a potential platform for bundled sensing solutions aimed at heavy-duty OEMs and aftermarket providers.
-
Continental’s supplier nomination on mainstream vehicle platforms during 2024 strengthens its program book and raises the competitive bar for entrants seeking MQB-like architecture wins.
-
CTS’s validation with major engine OEMs evidences its ability to meet heavy-duty reliability requirements — an endorsement that shortens procurement cycles for commercial programs.
-
Denso’s joint development pacts with OEMs for capacitive sensing point to early-stage design wins in hybrid platforms where fuel measurement precision interacts with electrified powertrain management.
Strategic playbook for 2026 — concrete actions
Based on our scenario analysis and supplier benchmarking, PW Consulting recommends the following priorities for organizations active in or entering the fuel-level sensor space in 2026:
-
OEMs / Tier-1s: Treat fuel-level sensing as a systems enabler. Specify diagnostic-to-ECU requirements up front, require supplier calibration IP transfer, and include crash and durability criteria in RFP workstreams. Align supplier selection with platform-level BOM targets and warranty cost models.
-
Sensor suppliers: Invest in calibration and diagnostics software, and modularize hardware to support multi-platform reuse. Secure alternative IC suppliers or integrate semi-custom ASIC strategies to mitigate lead-time volatility. Consider partnerships with cockpit integrators to embed sensor intelligence into HMI value propositions.
-
Procurement: Build dual-sourcing roadmaps for critical semiconductors and calibrate safety-stock policies to cover extended lead-time scenarios. Use supplier scorecards that weight calibration IP, multi-fuel capabilities and certification history.
-
Investors / M&A teams: Target niche providers that own calibration and diagnostics IP, ruggedized sensor houses with proven crash certifications, and aftermarket specialists serving commercial fleets. Our valuation scenarios prioritize recurring-program revenue and differentiated intellectual property over raw volume plays.
-
Aftermarket & Fleet operators: Prioritize retrofit options that minimize downtime and provide diagnostic outputs compatible with telematics systems. For fleets, longer-term TCO and serviceability matter more than first-cost; this opens premium service-led business models.
Scenario sensitivity and risk management
Our models include scenarios that stress-test two key risks: faster-than-expected EV penetration (dampening ICE demand) and prolonged semiconductor bottlenecks. In the near term, regulatory-driven precision and commercial/fleet demand are sufficient to preserve positive market growth despite EV headwinds. However, suppliers must maintain strategic optionality: re-purpose sensor platforms for non-ICE fluid-level uses, pursue retrofit channels, and restructure cost bases to withstand unit-volume contraction should accelerated electrification materialize.
What’s in the PW Consulting report — practical deliverables
The full Worldwide Automotive Fuel Level Sensor Market report includes an operational toolkit designed for 2026 decision cycles:
-
Comprehensive market sizing (2020–2025 history) and detailed forecasts (2026–2032) with customizable scenarios and sensitivity levers.
-
Supplier profiles and scorecards with program exposure analysis, supplier concentration metrics, and capability heatmaps.
-
Technology assessment comparing accuracy, packaging, calibration needs and BOM implications for capacitive, ultrasonic, resistive and hybrid sensors.
-
Procurement playbook: dual-source strategies, lead-time mitigation templates, and long-lead-item risk matrices.
-
Regulatory impact matrix tying emissions rules and crashworthiness standards to sensor specifications and compliance timelines.
-
BOM-level cost models and margin simulations for OEMs and Tier-1s; use these to run supplier negotiation and make-or-buy analyses.
-
M&A screening framework and a short list of acquisition targets by strategic theme (calibration IP, ruggedization, multi-fuel capability).
Closing — the 2026 decision horizon
The fuel level sensor market in 2026 sits at the nexus of regulation, technology differentiation and supply-chain risk. With a global market base of roughly USD 950 Million in 2025 and a modest but resilient CAGR of 3.2% through 2032, organizations that combine hardware excellence with calibration software, supply-chain resilience and platform-level integration will capture outsized value.
PW Consulting’s full report contains the granular regional, application and technology splits, downloadable financial models, supplier negotiation scripts and an executable 90-day plan tailored to buyers or sellers preparing for program decisions in 2026. For program-level specification sheets, BOM templates and pre-screened M&A targets, consult the complete research package.
For detailed analysis of this topic, please visit the official page: Worldwide Automotive Fuel Level Sensor Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com