

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Worldwide Offshore Riser Systems Market at USD 4,120.0 Million in 2025, Forecast to Reach USD 6,410.84 Million by 2032 at a 6.52% CAGR

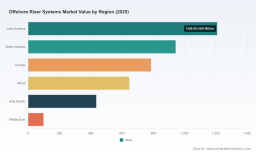
Worldwide Offshore Riser Systems Market: Strategic Imperatives for 2026 Decision‑Makers
As upstream capital discipline tightens and offshore project selection becomes more surgical, riser systems — the technical and commercial bridge between subsea reservoirs and surface facilities — are reasserting themselves as a determinant of project FID timing, contractor selection, and long‑term field economics. PW Consulting’s latest Worldwide Offshore Riser Systems Market report, with a 2025 base year and a forecast through 2032, shows an industry recovering and re‑rating: the market expanded from roughly USD 3.11 billion in 2020 to USD 4.12 billion in 2025 and, under our mid‑case assumptions, is projected to grow at a 6.52% CAGR through 2032 to reach approximately USD 6.41 billion. For executives preparing 2026 strategy, this trajectory is not just arithmetic — it signals where capability, capacity and commercial models must adapt.
Worldwide Clinical Research Services (CRS) Market
Why riser systems matter in 2026
-
Technical gatekeeper for deepwater value: Riser selection and design remain among the most consequential technical choices in offshore engineering — affecting field layout, FPSO/floating system type, fatigue life, and long‑term maintenance cost profiles. The growing share of high‑complexity developments in deep and ultra‑deep waters elevates riser engineering from commodity procurement to strategic asset design.
Worldwide Automobile Electric Power Steering Systems Market -
Contractor and supply chain leverage: The market’s moderate concentration (CR3 ≈ 41.8%; CR5 ≈ 58.4%) indicates a balance: a handful of global integrators and specialized suppliers dominate major EPCI packages, while niche players and OEMs retain bargaining power in components and services. This structure shapes negotiation dynamics for large tenders and the sourcing of long‑lead items.
Worldwide Spiral Ore Washing Machine Market -
Cost and schedule sensitivity: Riser systems combine long lead times, specialized manufacturing, and offshore installation risk. Volatility in steel supply and evolving standards mean that procurement timing and contract design materially affect project economics.
Key market dynamics shaping 2026 decisions
-
Project pipeline and selective capex: Macro forecasts show upstream E&P capital expenditure contracting modestly in 2026 amid oil price uncertainty. That implies buyers will prioritize fewer, higher‑return offshore projects — and suppliers will compete for concentrated waves of work. Firms must plan capacity utilization and bidding strategy around smaller numbers of larger, technically complex packages rather than broad, low‑margin volume.
-
Standards and integrity expectations: The third edition update of API Standard 2RD (Oct 2025) and continued reliance on ISO 13624 and API Spec 16F raise the bar for dynamic riser design, integrity monitoring, and lifecycle management. Compliance is now a contractual pass/fail item in many FIDs; companies that integrate updated standards into early design stages reduce execution rework and warranty exposure.
-
Raw material pressure: Benchmarks point to persistent price and supply risk in steel inputs — for example, Chinese carbon steel pipe export pricing and regional rebar indices show ongoing volatility entering 2026. Indexation clauses, hedging strategies, and localized sourcing will be necessary to manage margin risk on long‑lead fabrication contracts.
-
Tendering cadence: Large tenders have reappeared and are influencing market shaping — notably a major tender issued by Petrobras in early 2026, signaling material demand for rigid and flexible risers and umbilicals. Such tenders compress supplier selection windows and favor organizations that can demonstrate robust delivery track records, scalable fabrication capacity and integrated EPCI capability.
Competitive landscape — What the leading players are positioning for
The riser ecosystem blends global EPCI houses, subsea systems integrators, tubular manufacturers and specialized services firms. Our analysis of core players finds distinct competitive archetypes:
-
Full‑life SURF integrators (e.g., TechnipFMC, Subsea 7, Saipem) — These firms leverage integrated SURF/EPCI capability to capture higher‑value packages that bundle risers with umbilicals and flowlines. Recent contract wins (e.g., major EPCI awards for flexible flowlines and risers in deepwater projects announced in late 2025) demonstrate continued client preference for single‑integrator responsibility on complex deepwater campaigns. Their competitive edge is installation fleet access and integrated project risk allocation.
-
Subsea systems specialists and JV platforms (e.g., OneSubsea/SLB–Aker–Subsea7 JV, Aker Solutions) — These organizations focus on subsea production systems including high‑HP/HT riser technology and fatigue‑resistant solutions. Their value proposition centers on technology depth and manufacturing know‑how for demanding reservoir environments, making them preferred partners on wells with atypical operating envelopes.
-
Drilling and running equipment specialists (e.g., NOV, Oil States, Aquaterra Energy, Balmoral) — These players dominate the marine drilling riser, riser running and buoyancy modules segment. Their agility in developing compliant, API Spec 16F‑aligned modules and field‑proven connectors keeps them central to rig operators and drilling contractors.
-
Materials and component suppliers (e.g., Vallourec) — Premium tubular and metallurgical capability remains critical for steel catenary and hybrid risers. Control of qualified tubular supply chains is a strategic enabler for both manufacturers and operators navigating long‑term integrity requirements.
-
Service enablers (e.g., Baker Hughes, Weatherford) — These suppliers offer fatigue‑resistant riser systems, connectors, and mechanized running services that reduce offshore risk and time on station — increasingly relevant where schedule is a primary cost driver.
Recent contract awards in late 2025 and early 2026 — including large EPCI packages and deepwater export pipeline installations — confirm that incumbents with fleet access, integrated engineering and strong fabrication networks are most likely to convert the near‑term project pipeline into backlog.
What PW Consulting’s report delivers to support 2026 decisions
Our report is built for commercial and technical leaders who need operationally relevant intelligence rather than abstract market commentary. Key deliverables include:
-
Top‑line demand model and scenarios (base, upside and downside) through 2032 that translate project pipelines and capex assumptions into riser system volumes and replacement cycles.
-
Supplier scorecards and capability maps that highlight fabrication capacity, fleet access, IP strengths and contract levers — enabling buyers to shortlist partners for pre‑qualification in large tenders.
-
Procurement playbook and contract templates — recommended commercial structures (price indexation, milestone payment design, performance security) calibrated against steel input volatility and long fabrication lead times.
-
Risk matrices for technology and integrity (including compliance pathways for API 2RD updates and ISO/API drilling riser specs), plus recommended OPEX‑focused inspection and monitoring strategies to extend riser lifecycle value.
-
M&A and partnership screening criteria identifying where bolt‑on acquisitions or industrial partnerships create access to capacity, premium tubular supply, or specialized fatigue‑resistant technologies.
To honor the “trailer” principle, this note deliberately preserves the granular segment tables, region/application splits and supplier revenue details that are included in the paid report — those proprietary exhibits are what materially change bid/no‑bid and sourcing decisions and are therefore gated to report subscribers.
Actionable 90‑day checklist for 2026
-
Run a rapid scenario re‑pricing of any open fabrication RFQs to incorporate updated steel input projections and hedge where feasible; insert clear escalation formulas tied to recognized price indices.
-
Pre‑qualify at least two SURF integrators and two specialized riser fabricators for any project likely to FID in 2H‑2026; emphasize track record on dynamic risers and API 2RD compliance in pre‑qualification metrics.
-
Audit riser integrity programs against API 2RD (third edition) and ISO 13624 checklists; prioritize digital monitoring upgrades on existing dynamic riser fleets to reduce unplanned maintenance and insurance exposure.
-
Map long‑lead procurement against the 2026 tender calendar (including national champions and NOC timelines); where tenders are imminent (e.g., large regional pipelines or SURF programs), secure options for fabrication slots early.
-
Assess M&A targets that provide tubular qualification or capacity relief; small, focused capacity purchases can be more accretive in 2026 than large transformational deals.
Concluding perspective
The riser market’s mid‑decade inflection — moderate growth, concentrated major contractors, renewed large tenders and higher technical standards — creates both pressure and opportunity. For operators, the imperative is to de‑risk contractor selection and procurement design; for suppliers, the path to growth runs through demonstrable compliance, fleet availability and the ability to manage input‑cost volatility. PW Consulting’s Worldwide Offshore Riser Systems Market report synthesizes these forces into operational guidance and commercial tools crafted to inform FID‑level choices in 2026.
For teams preparing bid strategies, procurement frameworks, or portfolio repositioning this year, the full report contains the segment‑level demand analytics, supplier financial profiles and contract templates necessary to move from strategy to execution. Contact PW Consulting or visit our website to access the gated exhibits and tailored advisory options.
For detailed analysis of this topic, please visit the official page: Worldwide Offshore Riser Systems Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com